Cleared a tough government competitive exam, celebrated with family, secured an IDBI job—only to face the sudden threat of privatization, job insecurity, and shattered futures. This is unfair to banking aspirants and employees who served with dedication.
#IDBI#IDBINotForSale
PSU बिके,
रेलवे बिका,
BPCL और LIC बिके,
एयरपोर्ट और एयर इंडिया भी बिके,
और अब बैंकों के निजीकरण की तैयारी है...
देश की संपत्ति का इस तरह सौदा करना उचित नहीं है !!
#SaveIDBI
चाय बेचने की ऐसी लत लगी है कि देश की संपत्ति बेचने लगा!
जो IDBI बैंक 5 साल में ₹28,768 करोड़ का शुद्ध मुनाफा कमा रही है, जिसका मुनाफा हर साल बढ़ रहा है, उसी को सरकार कौड़ियों में बेच रही है!
₹25,000 करोड़ जनता का पैसा डालकर बैंक को खड़ा किया, अब जब ₹9,513 करोड़ सालाना कमाने लगी तो अपने कनाडाई मित्र प्रेम वत्सा को ₹81 प्रति शेयर में थमा दिया!
ये विनिवेश नहीं, देश के मुनाफे की लूट है!
Post No.248 #GOBACKFAIRFAX
WE, THE EMPLOYEES OF IDBI BANK, OPPOSE PRIVATISATION!
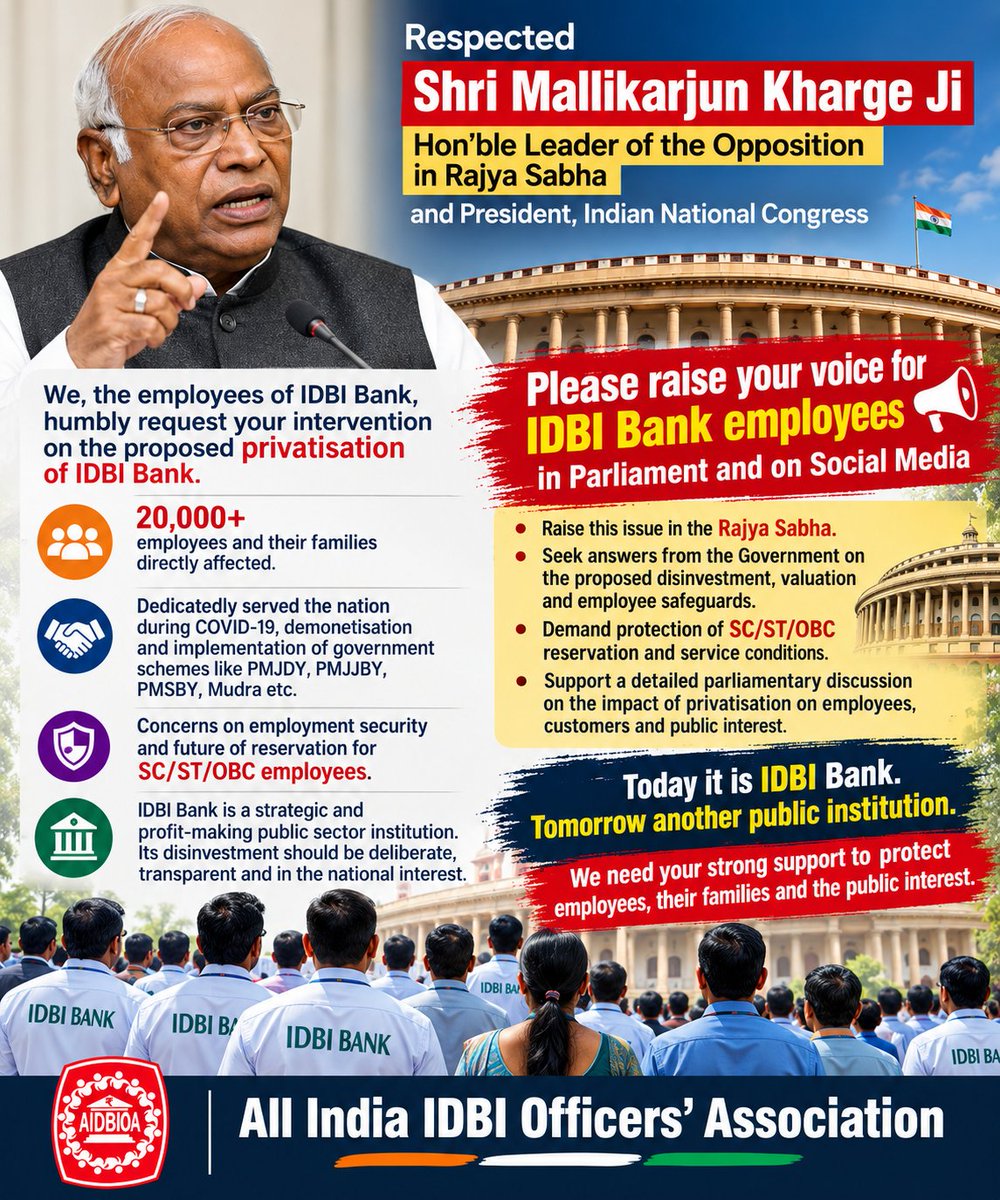
IDBI Bank is not just a financial institution,it is our livelihood, our professional identity, and a legacy built through decades of dedicated service @kharge
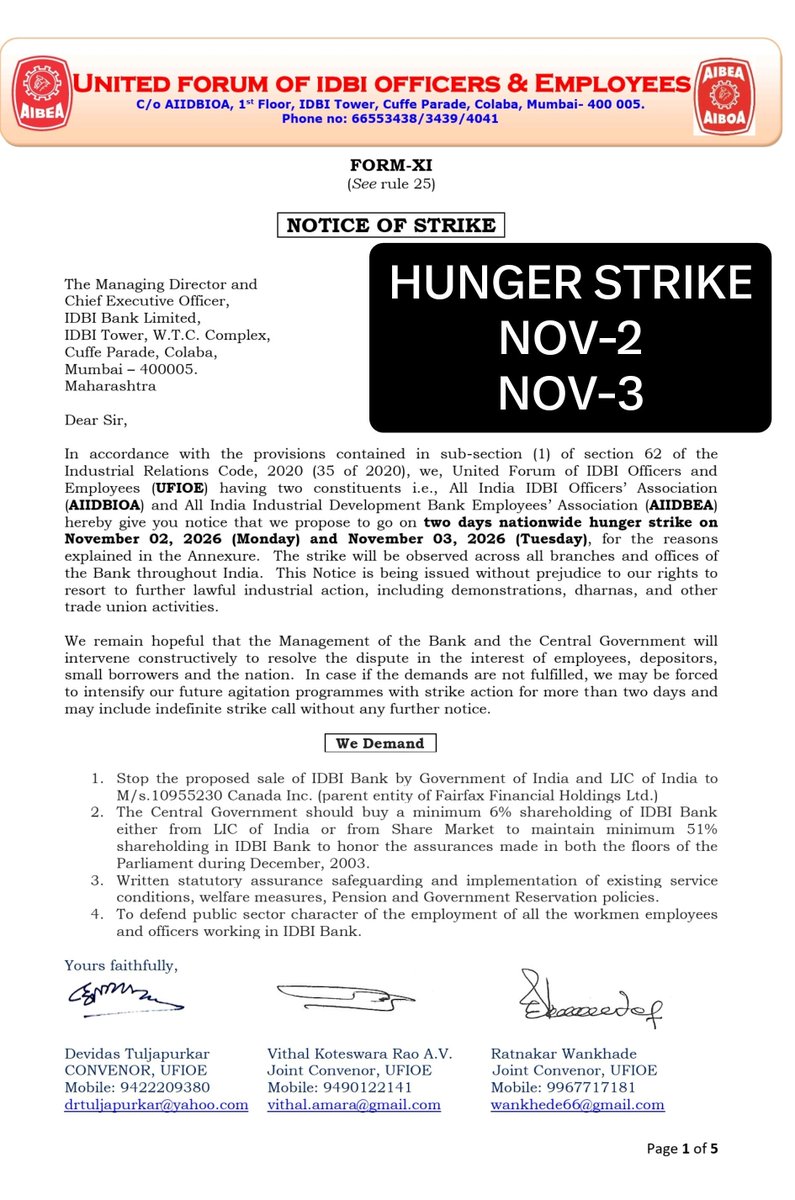
A two-day hunger strike is announced on November 2 and 3 in response to the Cabinet's approval for selling stake to Canada's Fairfax.
https://t.co/SCXH0yorQN
जो ढोल पीट रहा था 7.8% GDP का वो आज बैंक बेच रहा है...
Make in India से शुरू हुआ सफ़र, आत्मनिर्भर भारत के रास्ते अब ‘बेचो इंडिया’ तक पहुँच गया
राष्ट्रीय संपत्तियाँ बेच कर मोदी सरकार मना रही 'अमृतकाल'..
🚨 IDBI बैंक की 60.72% हिस्सेदारी ₹52,878 करोड़ में बिकेगी, मोदी सरकार ने दी मंजूरी।
केंद्र सरकार अपनी 30.48% और LIC अपनी 30.24% हिस्सेदारी कनाडा की Fairfax Financial Holdings को बेचेगी। सौदे के बाद सरकार के पास 15% और LIC के पास 19% हिस्सेदारी बचेगी। विदेशी बैंक Fairfax को प्रबंधन नियंत्रण मिल जाएगा।
(जय हो भक्तों के भगवान मोदी की..)
क्रोनोलॉजी समझिए : जब बैंक डूब रहा था, तब जनता के पैसे से सुधारा। जैसे ही बैंक मुनाफे में आया, सरकार ने इसे विदेशी हाथों में सौंप दिया
बीमार बैंक का इलाज जनता के पैसे से, और तंदुरुस्त होते ही मलाई कनाडाई बाबू को।
एक चाय बेचने वाले ने पहले नारा दिया था कि - 'मैं देश नहीं झुकने दूँगा', अब लग रहा है - 'मैं पूरे देश को बेच दूंगा!'
जो खुद को 56 इंची सीने वाला बताकर सत्ता में आया, उस महामानव के राज में सरकारी संपत्तियाँ निजी हाथों में जा रही हैं।
मोदी द्वारा पहले ही 13 से ज़्यादा पब्लिक सेक्टर कंपनियों को बेचे जा चुके हैं और अब रेल बेचने, एयरपोर्ट बेचने, जंगल बेचने के बाद अब बैंक बेचने के साथ ही भारतीय कंपनियाँ और सार्वजनिक संपत्तियाँ यूँ ही बिकती रहीं, तो आने वाले कल जनता के हिस्से में सिर्फ़ महँगाई और निजीकरण बचेगा।
सब कुछ बिक रहा है धीरे-धीरे, जनता आँखें बंद किए बैठी है,
आम जनता के पैसे से खड़े किए गए सरकारी संस्थान अब निजी हाथों में जा रहे हैं। और अंधभक्तों के महामानव (paw - paw) बड़ी बेशर्मी से मंच पर आकर विपक्ष को कोसता है, गुस्सा दिखाता है...लेकिन पूंजीपतियों के हाथों इस बिकी हुई सरकार ने आखिर देश की संपत्ति बेचने नफरती कानून लागू करने और नई शिक्षा नीति से शिक्षा व्यवस्था को बर्बाद करने के अलावा किया ही क्या है?
नालायक देश चला रहा है या सेल लगा रखी है?
'वोट चोरी' और प्रोटेस्ट की ख़बरों के बीच अयोध्या के राम मंदिर की चंदा चोरी और एपस्टीन फाइल का मुद्दा पूरी तरह दब चुका है. बीफ कंपनियों से चंदा, इलेक्टोरल बांड घोटाला और अब IDBI बैंक का बड़ा हिस्सा बिकने की ताजी खबर भी चर्चा से बाहर है. भाजपा की यही तो खासियत है। आपको बांग्लादेश और पाकिस्तान के मुद्दे पकड़ाकर कोई बड़ा घोटाला चुपचाप कर जाता है।
जय हो अंधभक्तों की... @kharge@kcvenugopalmp@INCHaryana@DeependerSHooda@INCIndia@raonarenderinc@SanjaySDutt@AdvRajendraPal@LambaAlka@RahulGandhi@TeamDeepender@MahilaCongress@INCSCDept@VinodJakharIN@Haryana_YC@JitendraBaghel_@Dr_Uditraj@INCOBCDept@ObcCongressHr@priyankagandhi@gurdeepsappal@TikaRamJullyINC@Kumari_Selja@KRajuINC@HaryanaPMC@RaoDanSinghHR@BhupinderShooda@VardhanYaadav@rssurjewala@BrijendraSpeaks
@rashtrapatibhvn honourable President… request you to please review IDBI Bank disinvestment… there is lot of irregularities observed in the process… if sold without reviewing, the dent on our country will be irreparable
EAS Sarma Urges President to Review IDBI Bank Disinvestment
Read More: https://t.co/SwLt7FisZV
#EASSarma has urged the President of India to review #IDBIBank’s #Disinvestment and order an independent inquiry into the sale of a 60.72% stake to Canada-based Fairfax Financial Holdings for ₹52,878 crore. He raised concerns over the valuation process, transparency, bidder participation and the interests of LIC policyholders and bank depositors.
#SaveIDBIBank
Post no.229 #idbinotforsale
WE, THE EMPLOYEES OF IDBI BANK, OPPOSE PRIVATISATION!
IDBI Bank is not just a financial institution,it is our livelihood, our professional identity, and a legacy built through decades of dedicated service
हमारी मेहनत, हमारा समर्पण और वर्षों की सेवा IDBI Bank की ताकत हैं। बैंक के निजीकरण से कर्मचारियों के भविष्य, नौकरी की सुरक्षा और सेवा शर्तों पर पड़ने वाले संभावित प्रभावों को नज़रअंदाज़ नहीं किया जाना चाहिए।
✊ आइए, एकजुट होकर अपनी आवाज़ बुलंद करें और सरकार से निजीकरण का फैसला वापस लेने की माँग करें।
एकता हमारी ताकत है — IDBI Bank हमारा सम्मान है!
#IDBINorForSale #SaveIDBI #StopPrivatisation
#IDBINotForSell
Post no.201Hungerstrike NOV 2&3
WE, THE EMPLOYEES OF IDBI BANK, OPPOSE PRIVATISATION!
IDBI Bank is not just a financial institution,it is our livelihood, our professional identity, and a legacy built through decades of dedicated service.@nsitharaman@rashtrapatibhvn@narendramodi
Post no.201Hungerstrike NOV 2&3
WE, THE EMPLOYEES OF IDBI BANK, OPPOSE PRIVATISATION!
IDBI Bank is not just a financial institution,it is our livelihood, our professional identity, and a legacy built through decades of dedicated service.@nsitharaman@rashtrapatibhvn@narendramodi
हम चुप न बैठेंगे सरकार की इस निर्णय को वापस लेना ही होगा ।
हमलोग सरकारी बैंक के अपना योगदान दिया था तो हमें सरकारी बैंक में ही काम करना है ये सरकार की मनमानी नहीं चलेगी ।
मोदी हाय हाय
#IDBINotForSale
Dear @DFS_India, awaiting for your reply to additional questions..
@yadavakhilesh , in addition to your valid questions , 12 other points also to be raised considering Larger interest of Public ,
1. FCNR(B) — Preferential treatment?
Why are banks offering attractive interest rates to attract NRI deposits while domestic depositors face different rate conditions? Who bears the cost and currency risk of the special RBI swap facility?
2. FCNR(B) — Leverage and returns
What is the actual lending and leverage structure against FCNR(B) deposits? If claims of 9–19 times leverage and 15–25% returns are being made, will DFS publish the underlying calculations, funding costs, hedging arrangements and risk exposure?
3. Priority Sector Lending — Who actually benefits?
Why can loans classified under priority-sector lending carry effective annual borrowing costs of 20–30% for poor , middle class borrowers? When banks route eligible lending through NBFCs and other intermediariesHow does such expensive credit serve the objective of affordable priority-sector lending?
4. Branch Expansion — Why are PSBs lagging?
Why has public-sector bank branch expansion not kept pace with private banks and Small Finance Banks? Will DFS publish comparable RBI branch figures for March 2026 for PSBs, private banks and SFBs?
5. SFB and NBFC Lending — Who bears the cost?
Why are Small Finance Banks and NBFCs playing an increasingly prominent role in credit delivery while PSB branch expansion remains limited? What safeguards ensure that middle-class families, poorer households and small businesses are not pushed towards more expensive credit?
6. Bank Consolidation — What is the policy rationale?
Why were 15 PSBs merged while 11 Small Finance Banks were approved? What measurable benefits have consolidation and the changing banking structure delivered in competition, financial inclusion, employment and customer service?
7. Banking Charges — Are customers paying more?
Will DFS publish bank-wise revenue from service charges, the cost of providing those services and the impact on low-income customers who have limited banking alternatives?
8. Repo Rate and Liquidity — What is the impact?
How are changes in the repo rate and the cost of attracting deposits affecting bank margins, lending rates and household borrowing costs? Will DFS publish its assessment of these effects?
9. Rupee Depreciation — What is the strategy?
What has been the scale and outcome of RBI’s foreign-exchange interventions? Will the authorities disclose relevant intervention data and explain the strategy for managing rupee volatility while protecting reserve adequacy?
10. Recruitment — Gross numbers versus net employment
DFS cites nearly five lakh recruitments over 10–12 years. If overall bank staff strength has reportedly declined by more than 80,000, why DFS not publishing net increase and publishing selectively
11. Insurance Mis-selling — Why does it continue?
What action has been taken against mis-selling and pressure on bank employees to sell third-party products? Publish complaint numbers, penalties and enforcement outcomes.
12. IDBI Bank — Public purpose and strategic sale
Has IDBI Bank’s contribution to financial inclusion and government-backed social-sector schemes been considered in the strategic-sale valuation? Why was a strategic sale to a Canadian investor associated with Prem Watsa preferred over alternative methods of reducing government ownership? Will DFS publish the valuation methodology, alternatives examined and safeguards for employees, reservations and the bank’s public role?
Dear Shri @yadavakhilesh ji, please raise these additional issues too.
Public-sector banking is not merely about balance sheets and profits. It is also about affordable credit, accessible branches, employment, financial inclusion and accountability.
Dear @DFS_India, the public deserves specific, data-backed answers to these questions, not merely claims and announcements.