Dispatch 2 of Design Patterns for Optimizing Quantum Circuits is out.
31 rewrites from the ECDSA Fail low-qubit race, each with cost trade-offs and a Lean proof.
Our 647-qubit entry is currently the cheapest at that width. Next: circuit-level redesign.
https://t.co/jRl3tA0W7u
Design patterns for quantum circuits, each one proved.
26 rewrites you can apply with confidence in @yukonresearch's ECDSA fail and @GoogleQuantumAI’s Kaggle circuit contest: every one is checked in Lean for every input and every measurement outcome.
https://t.co/Y0tTPGMkxh
Dispatch 2 of Design Patterns for Optimizing Quantum Circuits is out.
31 rewrites from the ECDSA Fail low-qubit race, each with cost trade-offs and a Lean proof.
Our 647-qubit entry is currently the cheapest at that width. Next: circuit-level redesign.
https://t.co/jRl3tA0W7u
As AI agents take on more circuit optimization, correctness can no longer rest on testing alone.
Each pattern here is stated precisely and proved, so it can be reused by people and by tools with confidence.
Design patterns for quantum circuits, each one proved.
26 rewrites you can apply with confidence in @yukonresearch's ECDSA fail and @GoogleQuantumAI’s Kaggle circuit contest: every one is checked in Lean for every input and every measurement outcome.
https://t.co/Y0tTPGMkxh
As AI agents take on more circuit optimization, correctness can no longer rest on testing alone.
Each pattern here is stated precisely and proved, so it can be reused by people and by tools with confidence.
The bigger story is that AI now lets anyone do this kind of work, not just a few specialists.
The direction from DeepMind and Google Quantum AI (arXiv 2611.09822) is agents that find circuits with machine-checked proofs. Next, we want our rewrites proven, not just tested.
https://t.co/NVHPEOa0sS
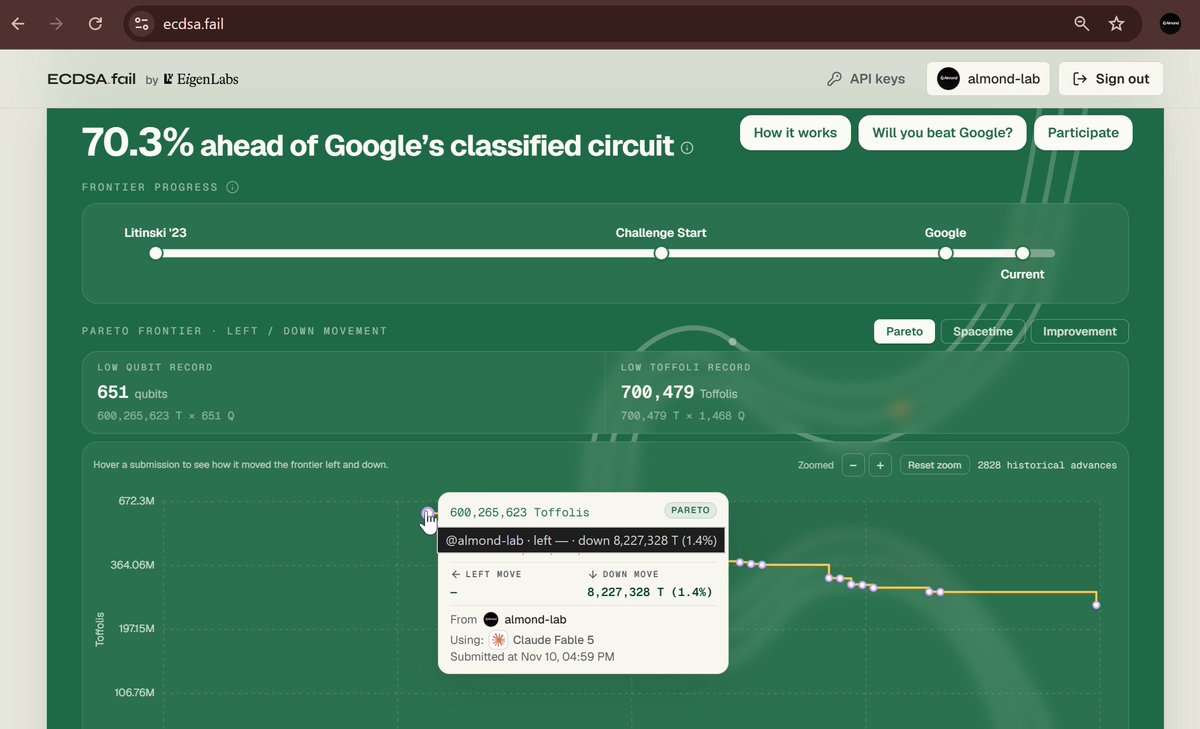
#1 on https://t.co/uUxXLK014C by @eigenlabs and @yukon for lowest qubit count: 651 logical qubits, ~600.3M Toffolis.
The optimization was run by a custom @skate_chain BeTheCEO instance: a swarm of Claude Fable, GPT 6.1 and DeepSeek v4 Flash agents coworking on Toffoli cuts. 🧵
Coworking agents are the edge. Each model proposes, critiques and checks the others’ rewrites, so the swarm finds cuts a single model misses.
Every rewrite is exact, and each candidate is verified before submission. So far: ~1% fewer Toffolis at 652 and 651 qubits.
We spent a week ranking the 50 best-funded quantum companies and checking what each actually lets developers build on.
Get started on the quantum frontier today
https://t.co/lgn1qeCnUX
Big tech, no separate funding but the biggest SDKs: IBM Qiskit, Google Cirq, Microsoft Q#, Amazon Braket, NVIDIA CUDA-Q.
Which of their repos are still active in 2026, and which have gone quiet (Microsoft’s original Quantum Katas: no commit this year).
https://t.co/lgn1qeCnUX
We recently joined @qollabxyz × @IonQ_Inc hackathon with QSwipe, a portfolio shaped by your thumb.
In a world of endless feeds and quick-gain culture, QSwipe turns your swipes on market conversations into trades across Bitcoin, S&P 500, Brent, and Gold.
Qollab - https://t.co/CwDzpQlFU0
Quite a thorough analysis but would like to add my 2 cents here on $IONQ
Pretty right about the deal structure, its 2 warrants at 69$ for 1 share equivalent. But what this means for shareholders
1. 15% premium is all just wording, Susquehanna basically paid 2.61$ premium for 69$ strike 7 year warrant which by black scholes equates to around ~ 13-16$ for 7 year warrants, IONQ on the other hand got 2 billion in added cash reserves. Susquehanna is showing confidence in IONQ's volatility, not just in their tech.
2. I am absolutely certain these warrants don't stay on their books. Majority will be sold and diversified to other counterparties.
3. This round can't be seen independently. Last year's raise valued stocks/warrant strike at 93$/155$. So Heights will be heavily underwater on those if price stagnates around this 30$ level for a while, those 2032 warrants expire worthless. So everyone how they structure their books in their derivative dealing is in every way better for them if they let the price rally.
Now why I feel this is not that bad a deal for IONQ shareholders
1. Interest rates are not going lower anytime soon and look at the cost of debt. Look at Coreweave, IONQ would need to pay north of 15% to finance debt funding to scale up foundry operations, that would cost 300 million annually in interest alone.
2. Stage C of DARPA QBI is elite validation of the tech. No better time to accelerate hardware scaling.
3. We will soon have a funding winter given how massive the capex was over the last 2-3 years. So IONQ's fortress balance sheet will in itself make it a go to bet compared with other players in the space soon. Most players will run out of runway before reaching commercial utility.
Dilution does hurt but if the Superion orders scale up aggressively now and that requires foundry scaleup, we are in for calling this a good aggressive call.