Former equity research sell-side & long-only investor turned corporate. Packaging, insurance, special situations but dabble in everything. Not investment advice
One of our staff members walked into my office earlier.
He has a very good friend who is a quantitative analyst at Blackrock.
Told him off record that Blackrock is having them stress test everything with a 10 year treasury at 9% for an extended period of time.
Said "worried" is an understatement.
7% mortgage rates
4% unemployment
5% bond yields
4% cash yields
$100 oil
$5 gas prices
3.4% inflation
Basically all-time highs in the stock market
Basically all-time lows in consumer sentiment
Something for everyone right now
Strange times
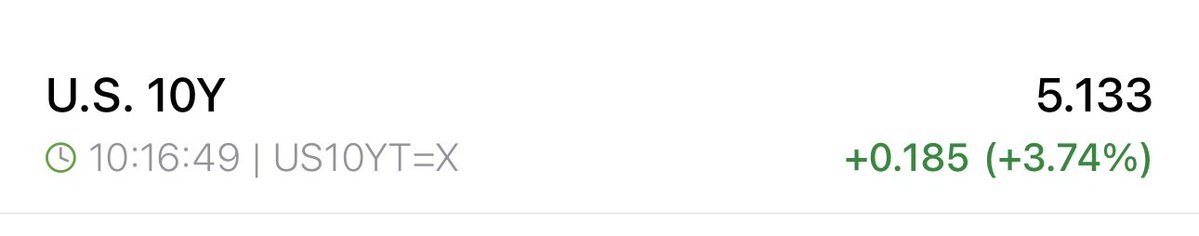
The US 10Y Note Yield is now moving in a literal straight-line higher, up to 5.13%.
This is no longer an issue that we have months or years to address.
This is unsustainable.
At what point does this become a race to the bottom on price? Not sure how much each will have enough product differentiation to justify much different cost. So then at some point, who becomes the and actor to go for market share by lowering prices
@CousinGraig Any thoughts on $BRO or $RYAN here? Have been interested in these two and maybe $AJG. Just hard for me to tell where we bottom out on pricing. Guess if we have an active cat season, that could help. But not sure when to step in. E&S secular themes seem more interesting to me
@ShakerBall_Cap@k3ithmccullough Agreed. It seems like there’s not as much solid fundamental analysis anymore. Lots of just reactions to current news (mostly AI). Guess it’s hard to do good short form analysis with limited character count though
@rich_toad@FundamentEdge At what point do we pass the inflection point where actually reading the filings is alpha-positive again though? AI will summarize how it wants. But I’ve found a lot of random key nuggets and anecdotes from reading an S-1 that were very helpful I’m sure AI wouldn’t surface
$BRO has been on my radar a while. A few concerns were their acquisition around peak multiples during a hard cycle (same with Marsh) and the current softening cycle. But with the huge drawdown and hard market over (?), might be worth a shot
$BRO
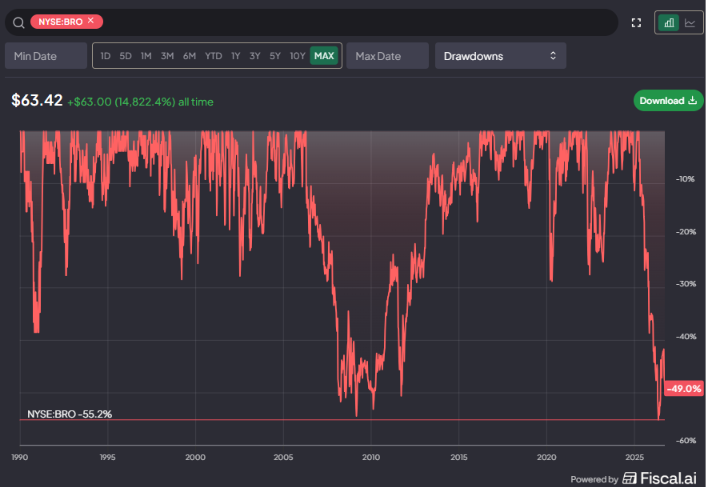
Brown & Brown having one of the largest drawdown in the past 36 years.
In a recent interview by @DrewCohenMoney , Chris Mayer explains why he likes Brown & Brown
1. He views commercial insurance brokers sector as having structural advantages, reliable and durable foundation for growth.
2. He thinks Brown & Brown has demonstrated an ability to compound capital effectively over a long period. Mayer values companies that do not rely on excessive leverage and that can consistently reinvest in their own success.
3. Chris Mayer views AI as a potential tailwind rather than a threat for companies like Brown & Brown because the largest expense for insurance brokers is labor, AI offers significant opportunities to automate tasks and enhance the efficiency of brokers.
4. He notes that other companies in the industry, such as AJ Gallagher $AJG , have publicly projected that AI initiatives could help increase profit margins by as much as six percentage points over the coming years.
Source: https://t.co/vDXXHBQKH9
@SignaStrategies@red_dog_capital Definitely didn’t say it was ASML. But average service contract length is 4 years, 90%+ retention, and the industry’s largest service portfolio. Just because it isn’t as hard as ASML doesn’t mean there isn’t a lock in/competitive advantage. High ROIC also implies there’s a moat
@Restructuring__ I used to be quite bullish on the stock once it got to mid teens EBITDA. Was sad it got taken out. Think they have a really good business with an enduring moat (surprisingly). But this is one way to kill it for a quick payout vs. letting it ride and dominate the market
This is really interesting. I wonder if the future of asset management looks more like star PMs with mostly agents around them or a lot more single PM hedge funds will come up. Lowers the barrier to running your own fund and really allows the star investors to shine
CNBC just filmed a hedge fund where every employee is an AI agent.
Payroll: $40,000 a year, all 4 of them. His last team cost $5,000,000 and burned him out of the business.
Watch him introduce the staff.
> Houston runs the place.
> Doocey is the red team. His only job is to break every trade idea before money touches it.
> Steffi, yes, Steffi Graf, marks up the charts. >Desmond runs the quant strategies over the weekend.
The human kept one job. He calls it the meat in the chair. Pressing the button.
7 or 8 people in New York, Hong Kong and California could not cover a crypto market that trades at 3am.
4 bots do. He started them on Claude Opus 4.6 and they have not slept since. 10x the output, his number, not mine.
527,000 people watched this in 8 days. Your timeline skipped it.
His forecast for Wall Street, on camera: one hedge fund manager, 1 or 2 humans under him, a swarm of agents under them. And for himself: "Maybe someday old BK will just have to be at the beach"
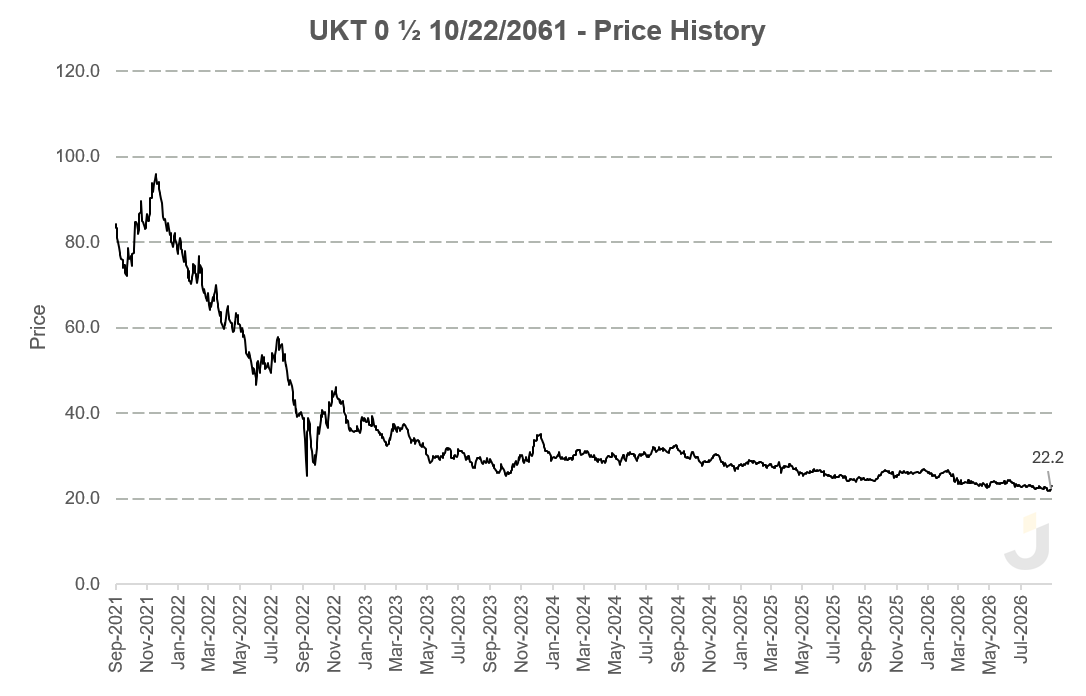
Haha this is wild. Even if they pull to par and get paid off in full by 2061, that’s a 5x return excl the coupon over 30+ years 😂. Guess you’re not playing to wait that long for it to pull back. But I’d be scared holding these long term
Love seeing this and I can understand the appeal.
Bankers in London are loading up their PAs with gilts, which are exempt from cap gains tax.
The 2028s are the most popular. With a 0.125% coupon, almost all the return is tax-free pull to par. Also, why they trade ~68bps rich vs. comps.
Want more juice? The 2061s are trading at ~22p...
Amazon blocks Muse.
Sure, they will blame it on "security". But Amazon made $76 billion in the last 12 months on advertising.
Agents don't look at ads. A new age of agentic battle has begun.