Someone complimented me in the comments today, then signed off with something more interesting. They had a feeling I haven’t actually made money investing yet.
I thought about that all afternoon. Fair point.
I’m new to investing. There are no returns I can show you today that prove I’m a good investor. A year means almost nothing, five years starts to tell you something, and a real career is measured over decades.
I made my money a different way. I built a startup from an idea into a 50 person company and eventually sold it (arguably too early). I’ve always been a very unorthodox person and, for better or worse, I’ve gone through life believing I could do almost anything.
What I’ve learned is pretty simple. Courage, charm and being a good person will get you further than 99% of people.
Add a bit of mongrel, discipline and perseverance and you become very hard to stop.
I think those traits should serve me well here. But “should” is doing a lot of work in that sentence.
Mindset is only half the battle. Judgment, experience and time still have to prove the rest.
So this is probably the most important disclaimer I can give you. Don’t take my posts as gospel. I haven’t been doing this long enough to have earned that.
What I will do is show you what I own, what I think, where I’m wrong and what it costs me. Then time can decide whether I’m any good at this.
One of my mentors used to tell me:
“Don’t be so humble. You’re not that great.”
The way this ends is 15% inflation for a decade.
Anybody on a fixed income is destroyed.
$500 for date night
Socialism grows.
Weath Tax imposed.
AI Tax assessed.
Equity P/E ratios drop
The rich leave for Singapore, Switzerland, Dubai.
Bitcoin becomes the safe haven.
Other coins suck liquidity, attention and people from $XMR
You need to become a toxic Monero Maxi for the sake of this coin.
Monero only and shame those shilling shitcoine
"so you staked your ETH on the Ethereum blockchain to earn yield?"
"yes, Dave"
"except you didn't want your capital to be locked up so you actually staked it with a liquid staking protocol called Lido?"
"that's correct, Dave"
"and Lido gave you a liquid staking receipt token called stETH in return?"
"yes, Dave"
"and then you didn't think that was enough, so you juiced the yield even further by depositing your stETH receipt tokens into a restaking protocol called Eigenlayer?"
"you are correct, Dave"
"and now you didn't want to lock up your capital, so you actually restaked with a liquid restaking protocol called KelpDAO who provided you with a liquid restaking receipt token called rsETH?"
"you got it, Dave"
"and then that was surely not enough juice, so you then deposited your rsETH tokens into a lending protocol called AAVE so that you could open a leveraged looping position that borrows ETH against the rsETH collateral and restakes the ETH into rsETH which is then deposited as collateral, except it turns out rsETH used a cross-chain bridge called LayerZero whose security is held together by a 1/1 toothpick, which was obviously hacked by north koreans causing rsETH to become undercollateralized and now these looping positions are stuck and unprofitable, and everyone is pointing fingers at each other, and also DeFi is a very serious industry"
"you are 100% correct, dave"
jfc.
> be me watching the american empire speedrun its own collapse in 2026
household formation dragging at pathetic levels like 1.41 million last year while underbuilding piles up a 4 million plus home deficit
boomers checking out en masse
birth rates stuck at 1.58 kids per woman
zoomers and millennials still basement dwelling or roommate maxing
15 million vacant homes collecting dust anyway who the fuck is buying when nobody can afford shit
chinese treasury holdings dumped down to 683 billion lowest since the financial crisis after years of steady selling now barely third place
treasury doing record buybacks trying to hold their own debt market together like its 2008 2.0
mortgage defaults climbing back to pre pandemic numbers 30 year rates hitting 6.46 percent after five straight weeks of pain locking out another generation
private credit house of cards starting to wobble hard
blackrock blue owl morgan stanley apollo ares all slapping gates on withdrawals with trillions in illiquid garbage
boomer retirements funneled into this mess through insurance companies
these firms straight up bought
treasury calling emergency meetings with regulators worldwide because this offshore reinsurance spiderweb is too big for state rules
energy shock going full send
gas just cracked 4 dollars a gallon nationwide highest since 2022 thanks to the iran strait of hormuz fuckery
global oil in transit dropped 300 million barrels in march
strait of hormuz turning into a floating parking lot for empty tankers
when those inventories finally draw down its gonna feel like 1973 had a baby with 2008
western inventories pretending nothings wrong
when the real physical hit lands diesel fertilizer and everything else goes parabolic
fink already said 150 dollar oil means global recession
food and supply chain death spiral kicking in
walmart recession indicator screaming near gfc peaks
fertilizer diesel both exploding from the energy mess
resin prices up 70 percent ytd with fresh hikes rolling in 5 cents jan 10 cents mar 20 cents april another 20 cents may same shit for plastics and packaging
average pound of ground beef now more expensive than federal minimum wage for the first time ever
ag getting absolutely railed
57 percent of winter wheat area under drought new record and overall wheat planted acreage on track for lowest since 1919
pfizer dropping a new lyme vaccine right as farmers find boxes of ticks in pastures yeah totally organic coincidence
grids falling apart labeled national security risk by jp morgan
world uncertainty index smashing records over 106k higher than covid 9 11 iraq war and gfc put together
energy feeding straight into fertilizer diesel costs then food goods inflation then more pressure on everything
stagflation on easy mode
plants out here blooming early yelling spring is here
everything else yelling winter is coming faggot
whos left holding the bag when the music finally stops
not me im already ngmi
multifamily households just hit all-time record
everyone stacked like sardines in apartments because solo living is a richfag meme now
zoomers out here choosing pet rocks and therapy dogs over kids or mortgages
consumer debt maxed out while savings rate still in the toilet
credit card delinquencies creeping up like they smell blood in the water
yield curve uninverting in the most retarded way possible
classic recession signal but markets still pretending its different this time
farmers straight up giving up on wheat like its 1930s dust bowl cosplay
corn and soy not looking much better with fertilizer costs doing the needful
bread prices about to make wonder bread a luxury good
its a beautiful circle of hell
@R0GER_B1@_dt777@Yannix_1337@LayoffAI Got 2 WL spots and like 10 top 5’s and got absolutely nothing. The only place they listed WL claim instructions was the bowels of some bullshit discord chat.
You can’t tax unrealized gains without hurting average Americans, and retirement funds.
But, you *DON’T* need to tax the gain, you can tax **the loan**
Interest is charged on loans.
Whenever someone takes a loan against a company that they:
-own more than 10% of
-sit on the board of
-a c-suite executive of
-or it’s a fund where the owner is a beneficiary who meets these criteria
-AND the company is worth more than $100M
-THEN: simply add a 25% surcharge to the interest that goes to the government, and require that these loans are at minimum the prime rate.
If the loan had 4% annual interest, it now has 5% annual interest with that extra 1% paid to the government as a tax.
Now governments get income from those who take loans on corporate equity but:
-It doesn’t hurt startup employees with stock options
-It doesn’t break temporary liquidity borrowing
-It doesn’t hurt small business owners
-It doesn’t break unrealized tax loss/capital gain accounting
-It doesn’t risk pension funds
-It doesn’t break venture funds creating new jobs
-It prevents tax cheats, but also prevents unfairly taxing non-existent capital
-It ensures the US market is still liquid and innovative to help the economy.
In this model if someone takes out a $100M loan, on $200M in assets, the government is charging $1M/year in interest.
If thar $200M stayed worth $200M for 3 years, or had write offs of capital losses, an unrealized wealth tax of 1% would have been $0 (and risk breaking stuff)
Whereas 1% interest annually on the borrowed amount, for 3 years, is $3M and doesn’t break things.
So this model likely also brings in *more* capital, while not breaking the economic system, and closing the abuse without closing the functionality.
Banks earn 4.4% on reserves parked at the Fed...
They pay you 0.01% on your savings account.
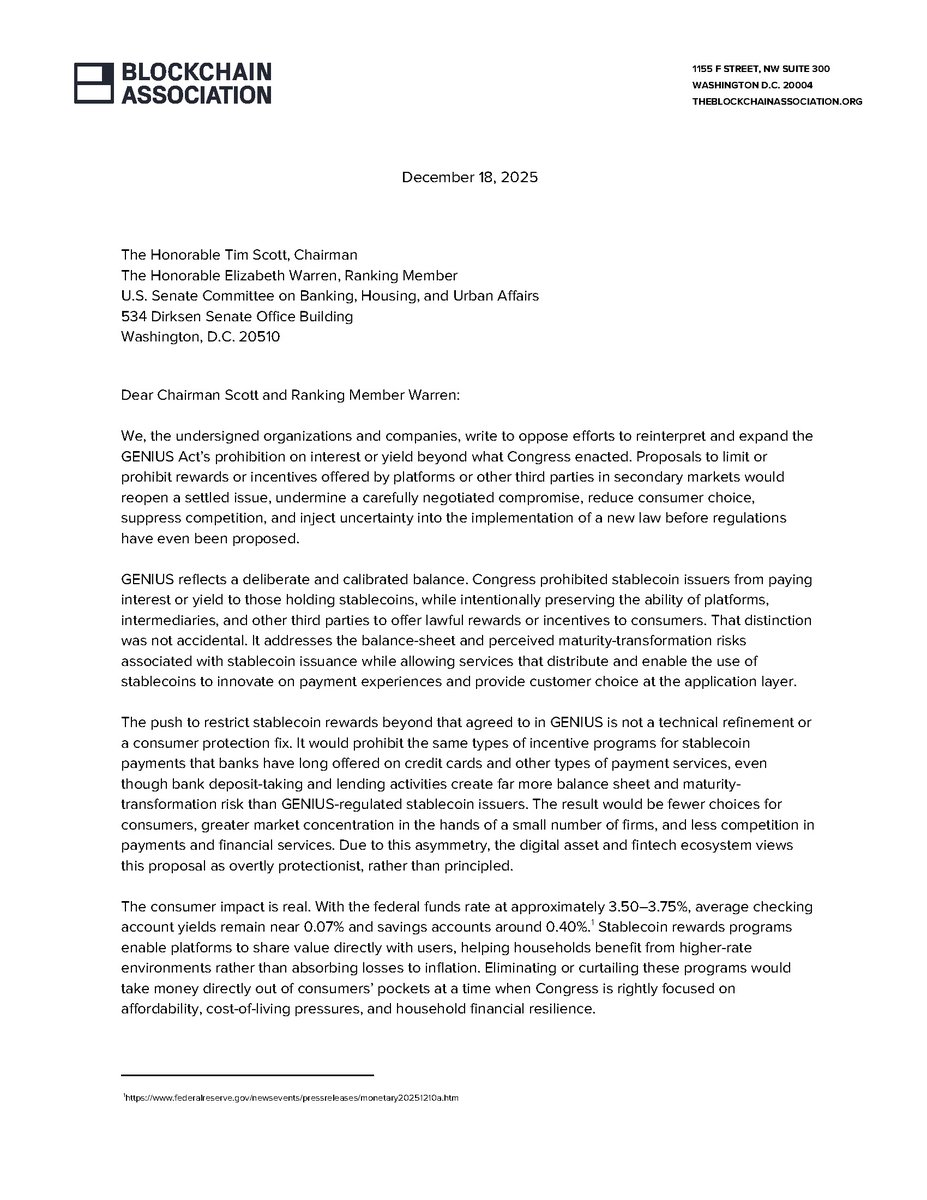
And now they're lobbying Congress to make sure stablecoins can't offer you anything better.
The GENIUS Act already settled this. Congress spent months hashing out a compromise. Stablecoin issuers can't pay interest directly, but platforms and third parties can offer rewards. Done. Finished. Everyone shook hands.
That was a few months ago.
Now the banking lobby wants to reopen it. They're calling it a "safety concern." They're worried about "community bank deposits."
Independent research shows zero evidence of disproportionate deposit outflows from community banks. Meanwhile, the big banks are sitting on trillions in reserves, collecting interest from the Fed, passing almost none of it to customers.
How this plays out for the most part is that your bank takes your deposit, parks it at the Federal Reserve, earns 4%+ on it, gives you basically nothing. A stablecoin platform wants to share some yield with you and suddenly that's a threat to financial stability?
We saw three different lobbying pushes on this bill in the last year & every single time, the framing is consumer protection, but in reality, every single time, the actual effect would be protecting big banks and incumbent margins.
What you should actually watch for:
-Any amendment that bans "rewards" broadly rather than just direct interest payments from issuers.
-Whether the same legislators worried about stablecoin yields have ever questioned why bank savings rates haven't moved in fifteen years.
-Who's funding the "community bank protection" messaging (Usually not community banks lol)
If Congress caves on this, it sets a (not good) pattern. Pass a framework, let the incumbents lobby it back open, chip away until the new entrants can't compete, and crypto companies aren't the only ones watching. Every fintech considering U.S. markets is taking notes on whether legislation here actually sticks.
We signed on to this letter to show our support and conviction in moving the industry forward in the United States. The next six months will show whether the U.S. wants competitive payments infrastructure or protected banking margins under the guise of "stability"
as always, thanks to @BlockchainAssn for their hard work in the industry alongside @standwithcrypto & @na_blockchain
special shoutout to @TBC_Jessi@512mace & @wadepreston for pushing this along as well
2022: No salary increase
2023: No salary increase
2024: No salary increase
2025: No salary increase
2026 :
Employee: Please accept my resignation.
Boss: You’re doing great. Why are you resigning?
Employee: I accepted an offer with a 95% base salary increase and guaranteed yearly salary cycles as long as I meet my performance goals set by my manager.
48 hours later...
Boss: We will match the 95%, please stay, we need your work!
Employee: Unfortunately, it’s too late. Friday is my last day.
Leaders of organizations need to understand their teams’ motivation every month. Every employee is motivated by different things in different periods. Take care of your good employees before it is too late