There are three great opportunities in quality growth investing.
1. Low revenue growth companies with the potential for high FCF growth through significant margin expansion. E.g. $ICE $BR
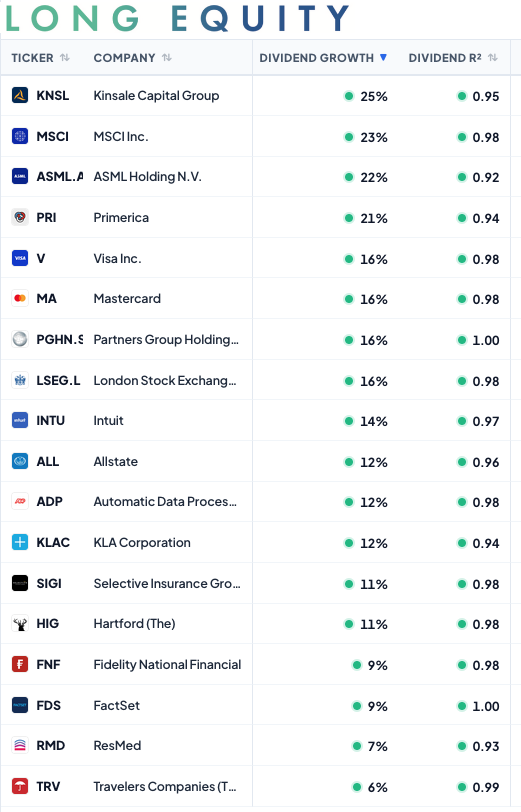
2. High return on capital companies with the potential for high FCF growth through buybacks. $MSCI $FTNT $KLAC $LRCX
3. High FCF growth companies with the potential for a significant contraction in FCF yield (in other words, a re-rating). $MSCI $BR
I aim to have a portfolio where all three are in play.
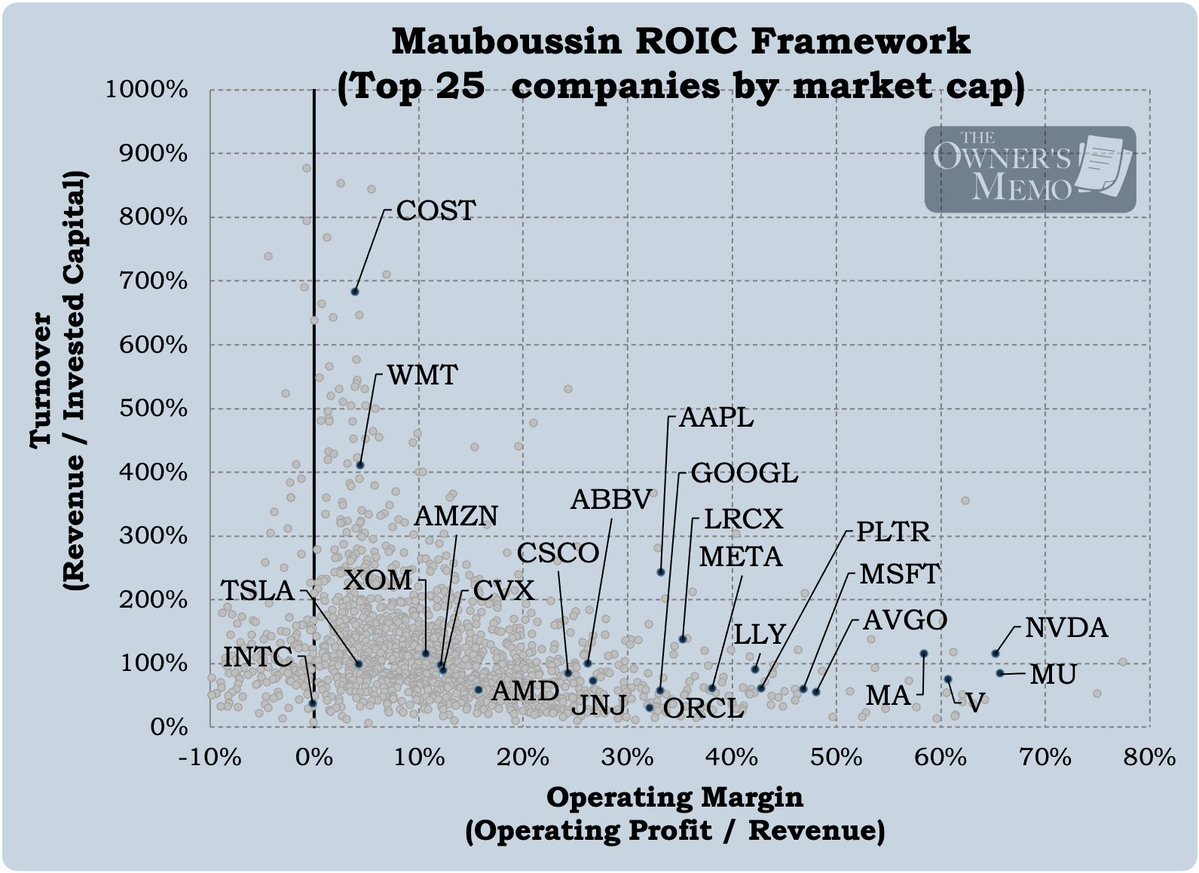
The very best companies in the world have the highest returns on invested capital.
Michael Mauboussin and Dan Callahan break that down by charting the two components of ROIC: operating margin and invested capital turnover.
I updated their work with the results from US companies over the trailing twelve months. At the highest levels above a pre-tax ROIC of 45% sit 44 companies out of 1,769.
Some are the names you would expect, like Nvidia, Visa, Mastercard and Apple, which earn their returns through high operating margins, while others, like McKesson, get there by turning over their invested capital dozens of times a year on very thin margins.
To make the list manageable, I focused on the companies whose operating margins had risen consistently for the past year and a half.
The cheapest was Clear Secure, trading at 11.3x P/FCF, a company whose operating margin has gone from -48.2% in late 2021 to 29.9% last quarter, with revenue up 26.6% year-over-year.
The Owner's Memo #25 is out today. Link in the comments.
cc: @mjmauboussin@dcalz
These five videos are an absolute masterclass for investors.
1. Aswath Damodaran - Corporate Finance class
This covers everything you need to know about how a company should manage its money. Essential listening.
https://t.co/P945gFATnH
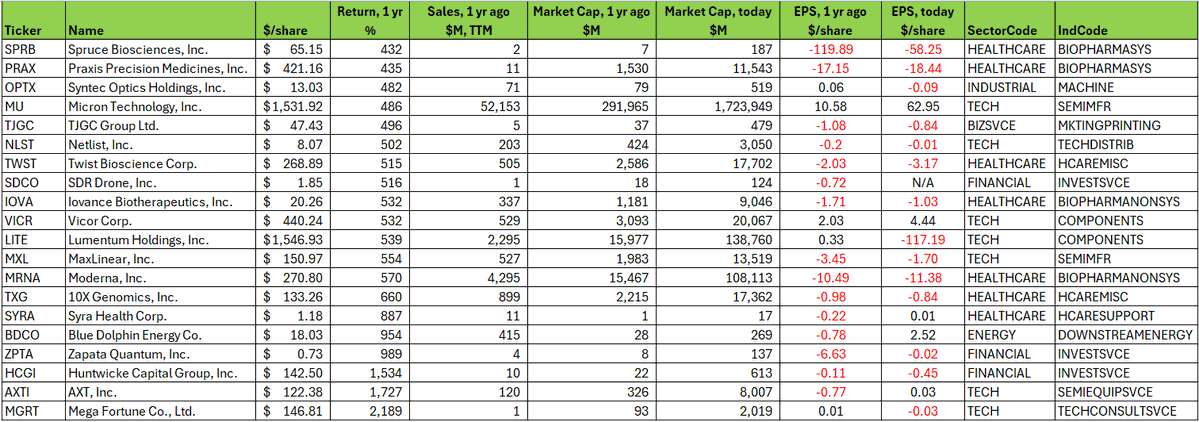
10Bagger Portfolio is now in English: 6 FREE deep dives, 8 paid ones and last quarter's follow-ups. A ❤️ or repost helps me reach more people and, who knows, maybe get the chance to talk with more management teams around the world. 🔗 and a sneak peek in the first reply.
Multibaggers 5X or greater in the last year 🇺🇸
They don't usually look like multibaggers at first:
20 names total*
👉75% started unprofitable - several are now less unprofitable
👉50% started as microcaps
👉35% biotech/healthcare
*of 4,300 starting with revenue, >$0.1/share
Warren Buffett once said there are 3 people that he would let manage his money.
1. Seth Klarman
2. Li Lu
3. Greg Alexander
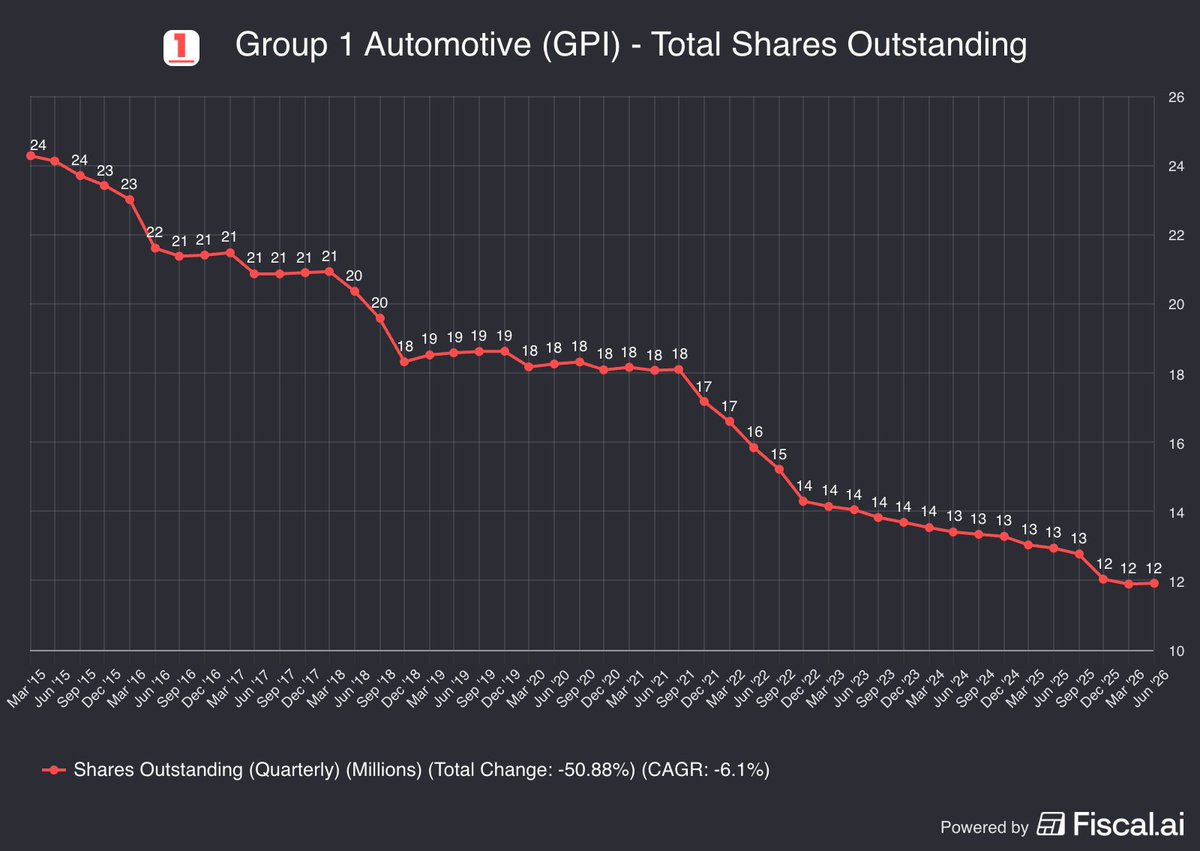
Greg Alexander just made this auto dealer 46% of his portfolio.
$GPI
Ahora que conoces los subsectores...
Vamos a ponerles nombre.
Cada uno tiene compañías líderes con modelos de negocio muy diferentes.
Y entender quién domina cada nicho ayuda muchísimo a comprender el sector.
$OTIS DCF valuation model
Nobody gets excited about elevator companies. Yet perhaps every second person uses OTIS equipment or services every single day. That kind of boring can become very interesting at the right price.
Key assumptions:
Explicit average 5Y/5Y growth @ 5%/3.8%
Long-term growth in perpetuity @ 2.6%
Initial EBITDA Margin 16.7% -> 18.6%
WACC @ 7.5%
Adj. EBITDA exit multiple of 13.4
Tax rate 25% - in line with historical average
The input that drives reinvestment is the most recent Sales to Capital ratio = 3.17