@mikealfred at Bitcoin Treasury
“If Bitcoin doesn’t rise in the next 3-4 years, I will be apologizing for being wrong. It will mean politicians and central bankers are good at their jobs and CARE about the public by adopting austerity…. “
Bitcoin’s SuperCycle
A supercycle is more than a long bull market. It is a structural re-rating, usually lasting at least five years, in which an asset’s role in the global economy changes so profoundly that the old valuation framework no longer applies.
Commodity supercycles emerge when a new source of demand meets constrained supply. China’s entry into the World Trade Organisation in 2001 is the modern example. China did not invent steel, copper, oil or coal. It unlocked a vast new market for them.
The commodities did not change. The market around them did.
Bitcoin may be approaching a similar institutional opening.
For most of its existence, Bitcoin has been a scarce global asset constrained by limited access to conventional capital. Banks faced legal uncertainty, pension funds faced custody and compliance hurdles, and corporations faced accounting and reputational risk. Bitcoin therefore traded largely as a speculative asset, driven by retail enthusiasm, specialist funds, liquidity cycles and the mechanical halving of its mining reward every 210,000 blocks.
That is beginning to change.
America is building the framework for a regulated digital financial system. The GENIUS Act creates federal rules for payment stablecoins. The SEC and CFTC are establishing clearer definitions and oversight for digital assets. Tokenised Treasuries, money-market funds, private credit, equities and other financial claims are moving onto blockchain rails.
The likely result is not the displacement of the dollar. It is the digitisation of dollar finance.
Stablecoins may become digital money, used for payments, settlement and collateral movement. Tokenised securities may become digital financial claims. Bitcoin can occupy a separate role, digital capital: scarce, liquid, portable and independent of any corporate or government issuer.
That is Michael Saylor’s central proposition. Bitcoin does not need to defeat stablecoins in payments. Stablecoins are better suited to daily transactions because they preserve dollar stability. Bitcoin’s opportunity is to become the reserve asset held beneath a growing system of digital money and digital credit.
This is where the supercycle argument becomes serious. A Bitcoin halving reduces new supply, but it does not create a supercycle. A supercycle needs a new marginal buyer.
China’s WTO accession created a new marginal buyer for commodities. Regulatory clarity, stablecoins, tokenised capital markets and institutional infrastructure could create one for Bitcoin: corporations, asset managers, insurers, pension funds, sovereign entities and global savings pools able to own, custody, finance and collateralise it at scale.
AI adds a further layer.
It is accelerating demand for data centres, power and machine-speed financial infrastructure. Bitcoin miners control power capacity, land, cooling and grid connections, assets increasingly valuable to the AI economy. More stable AI-related revenue could reduce forced Bitcoin sales by miners.
The key condition for a Bitcoin supercycle is not that Bitcoin itself changes. Its supply schedule, network and monetary rules remain the same. It is that the global financial system around Bitcoin changes, becoming more digital, tokenised, regulated and institutionally accessible.
The elements are now lining up: shrinking new supply, regulated digital dollars, tokenised markets, institutional access, AI infrastructure and Bitcoin-backed credit. None guarantees a straight line higher. But if these changes create a permanent new class of Bitcoin buyers, as China’s WTO entry created a vast new source of demand for commodities, Bitcoin could shift from a recurring halving trade to a genuine supercycle re-rating as the reserve capital of a digital financial system.
#Bitcoin $MSTR $STRC
new cycle highs on 10-year bond yields in Germany, France, Italy, Spain, Portugal, Ireland, Netherlands, Finland, Sweden, Denmark, Belgium, Austria, US, Japan h/t @BairdStrategas
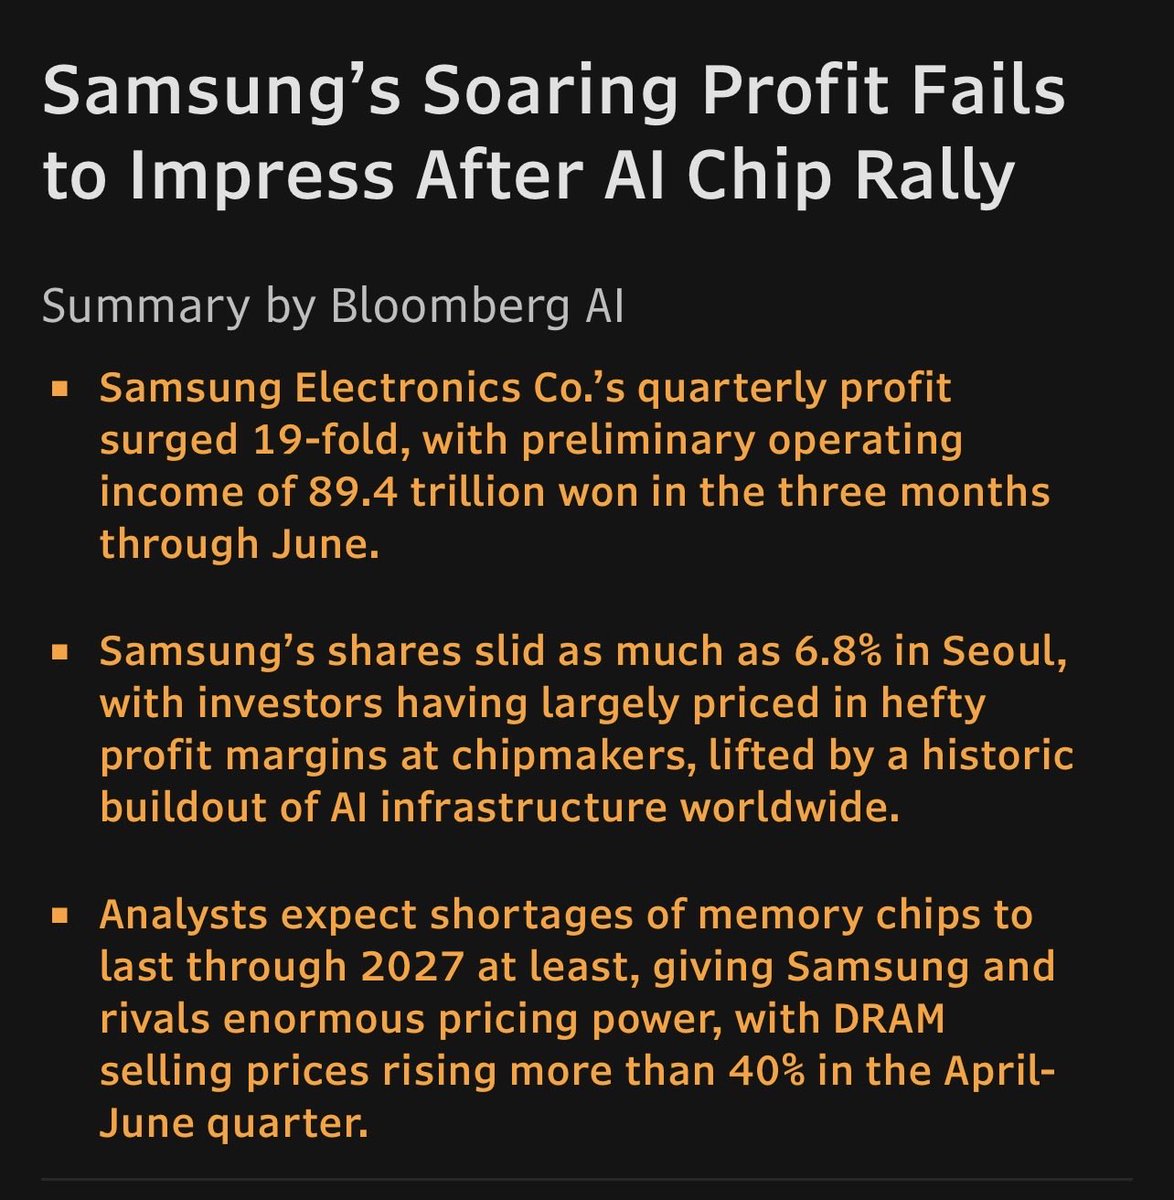
Samsung numbers not good enough!
Beyond the AI bottleneck
Artificial intelligence is not over. But easy trade in it is.
Samsung’s latest numbers made that plain. Quarterly operating profit surged on AI‑driven memory demand and higher DRAM prices. Analysts still expect shortages into 2027. Yet the shares fell. That is what happens when a bottleneck trade gets crowded: fundamentals stay strong, but earnings stop impressing because perfection was already priced in.
This is the fate of parabolic charts. Semiconductors, memory and AI power were the obvious chokepoints in the first phase of the AI buildout. Capital flooded in. Nvidia led. The SOX soared. Now the leaders are over‑owned and increasingly unable to turn good news into higher prices. The theme may have years left. The trade does not.
The next bottlenecks are likely to be less glamorous: power, grid capacity, cooling and physical infrastructure. Markets are also beginning to price a different rates regime. Kevin Warsh’s Fed looks less Powell‑like, the Iran shock is fading and rate‑sensitive sectors are starting to stir.
The lesson is simple: sell parabolic crowding and buy fear. In this market, that means trimming AI bottlenecks and looking harder at under‑owned domestic cyclicals and Bitcoin.