AI AGENTS ARE BECOMING ONCHAIN CAPITAL ALLOCATORS.
Wallets, inference, vaults
All three layers shipped in one week.
20+ teams building the stack
❱ Agent Apps & Execution
- @virtuals_io: Personal AI agents with wallets and group chats
- @bankrbot: Financial agents, token launches and fee infrastructure
- @gizatechxyz: Autonomous onchain capital management
- @almanak: Quant strategies and automated execution
❱ Inference: four layers, four value pools
Every agent pays for inference. Each layer captures a different slice.
Supply
- @chutes_ai: Decentralized inference supply
- @togethercompute: Inference infrastructure and model optimization
Routing
- @OpenRouter: One API, 400+ models
- @Architect_Fi: Liquid Inference, providers compete per prompt
- @AskSurplus: Surplus Intelligence, inference routing
- @UsePodAI: Inference routing, default provider for ClawPump
Tokenized access
- @AskVenice: $VVV, private inference for AI agents
Agent demand
- @openservai: Agents buying inference on demand
- @NousResearch: Hermes, 15–20% of OpenRouter app share
Robot Ventures - @tarunchitra found routing quality has a real price:
- 64/64 OpenRouter tests ranked providers by input price
- Cache-dropping repricers extract ~$3.5M a year, ceiling ~$14M
Agents run long, repetitive sessions. Routing quality becomes a direct cost line.
❱ Vaults & Curators
- @chainlink: CCIP Vault Adapters connecting ERC-4626 deposits across 80+ chains
- @aave: sGHO cross-chain savings
- @maplefinance: Cross-chain lending and deposit access
- @veda_labs: $32B+ volume across 200+ vaults
- @RockawayX: Curated vaults using CCIP adapters
- @k3_capital: Institutional DeFi risk management
- @EmberProtocol: Vault deployment and distribution
Today, agents chat, trade and launch tokens.
Tomorrow, they route inference, pick vaults and rebalance treasuries around the clock.
Capital will follow the rails every agent touches by default: execution, inference and yield.
The next fund manager could be a model.
This map shows who it will hire.
A stablecoin shows $1. That dollar is a claim on the issuer, and most holders reach it through the market. 🪙
Four things to check:
→ Reserves: what backs it, and where it's held
→ Reporting: how often, and who checks it
→ Redemption: who can redeem directly, at what minimum and fee
→ Version: the issuer's own token, or a bridged one
In March 2023, with redemptions paused over a weekend, USDC traded as low as 86 cents.
Fed note on that weekend: https://t.co/NQMpmzjToi
🚀 $INJ AND MICROSOFT PUT AGENTIC FINANCE ON THE TOKEN2049 STAGE
Microsoft and $INJ co-hosted an event featuring institutional speakers, ecosystem builders and previews of upcoming releases.
$INJ says the collaboration will focus on bringing onchain agentic finance to the world.
AI agents moving from conversation toward financial execution.
Some people are very irresponsible with money, whether they make a little or a lot. Everybody wants to talk about the cost of living increasing, but it’s not just that & y’all know it.
You can just be saving up your money and the next moment you receive debit that you don’t even know about
This was not how I planned my Sunday fr 😔.
I hate my life.
We had a church market today, an event we started two years ago to get our people busy and allow them local streams of income that would also bless the community. The week before these I am always tempted to wallow in my inadequacies 😂…
it’s one thing to coordinate and participate in an event. I think I would be good at that? But to do so while cultivating entrepreneurship in our kids at the same time can turn my brain into gobbledygook. They all have ideas, with many needed tools and ingredients for their creations. They are still learning timing and budget and clean-up, so you have to cheerfully push while also being pulled in unknown directions, if that makes sense.
And of course there’s the size of the kitchen lol and working out who gets the oven when.
It feels bigger than life, is what I am saying, in a life that always feel pretty big. 😂
But then once we’ve made it, and everyone has participated in their own way, we are SO happy and satisfied, and even though our town is tiny, we make enough money to bless the family budget beyond the monthly necessities.
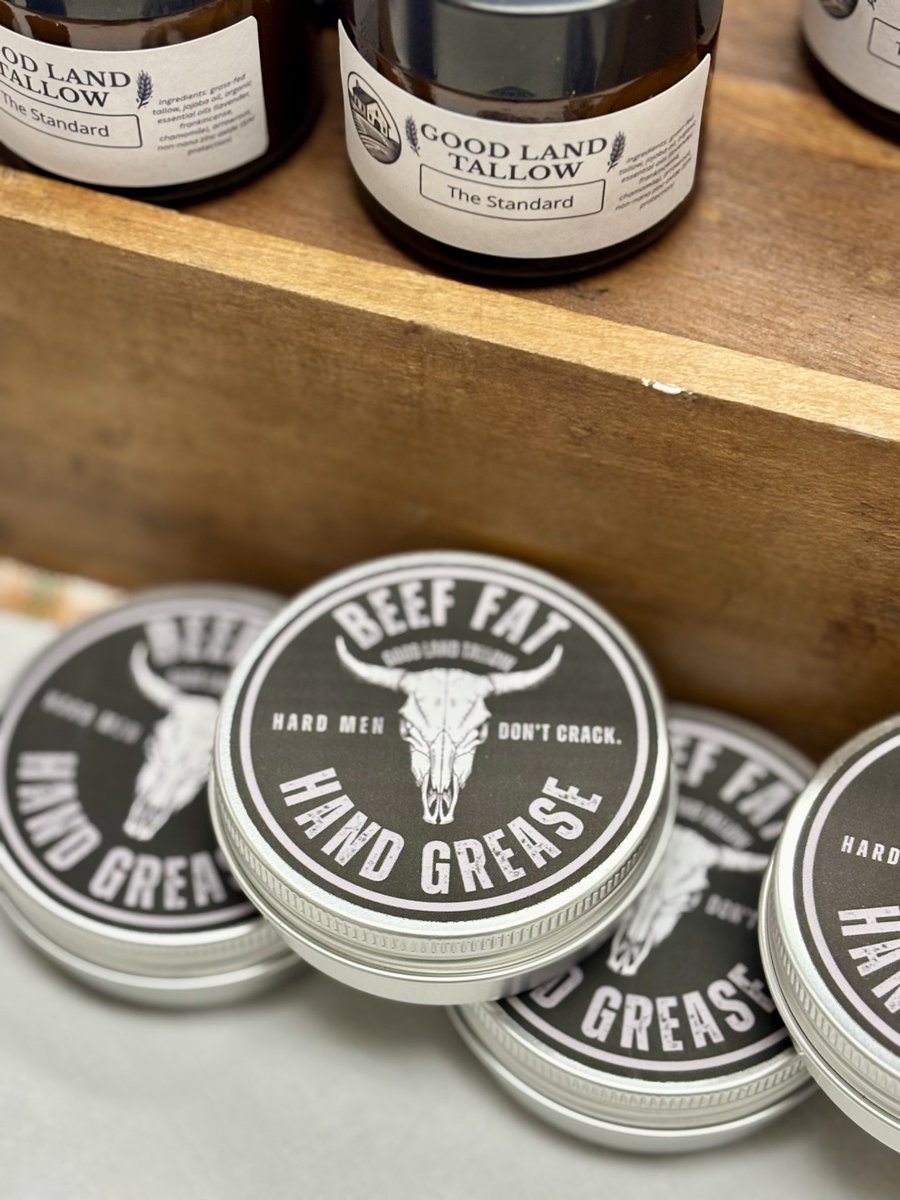
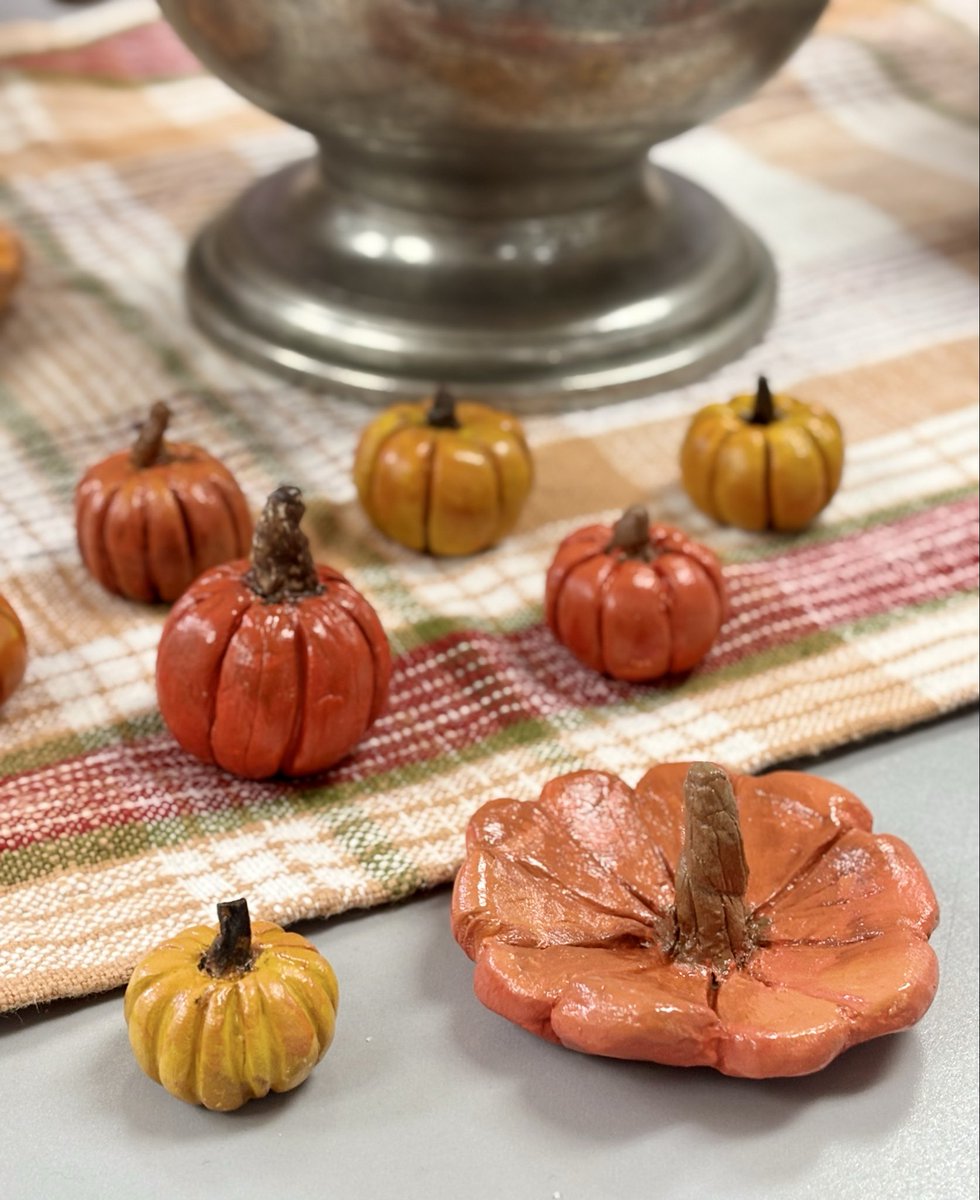
Today we took with us: 42 apple cider donuts, 48 cinnamon rolls, 56 cups of granola, three types of tallow balm, a hundred or so homemade caramel candies, 45 chocolate gooey butter cookies, hand sewn bandanas, three racks of consignment clothes, potato soup, pimento cheese, coloring sheets, and four different kinds of specialty coffee. And our fifteen-year-old made and painted the CUTEST pumpkins and jewelry dishes out of clay!
So yeah, we are happily exhausted tonight, with a few piles of things to unload, but we all came home with extra dollars and another level of growth in our skills. ❤️
It’s so easy to grow discouraged in this economy, but I keep thinking there are opportunities everywhere if we can just keep showing up. 🏃♀️🏃♀️🏃♀️
To budget or not to budget?
A budget is not meant to tell you that you cannot spend your money, but to help you decide where your money should go before it disappears. Without one, it is easy to pay the bills, spend on the things you want, handle a few unexpected expenses and end up grasping for straws before the month ends.
A good budget should account for your regular expenses, savings and investments, debt repayments, irregular expenses and some room for spending. All you need is enough structure to make sure your spending does not consistently compete with the financial goals that matter to you.
BARBARA: my husband and I loaned our 26-year-old son $3,000. He still owes $1,500. When we ask for it back he uses emotional manipulation. He says he's entitled to the money and blames us for his financial problems.
DAVE RAMSEY: forgive the debt.
BARBARA: just let it go?
DAVE RAMSEY: officially. Completely. Not because he deserves it. Because holding it gives him a weapon to use against you.
BARBARA: then what?
DAVE RAMSEY: no more loans. Ever. To any adult child. Money changes the relationship. It always does.
BARBARA: but he's struggling.
KEN COLEMAN: he's not lazy Barbara. He's lost. There's a difference. But here's what you have to understand. You cannot find him. Only he can find himself.
BARBARA: so we just watch?
KEN COLEMAN: you love him. You make yourself available when he's ready to accept help on healthy terms. But you stop accepting abusive behavior as the price of the relationship.
DAVE RAMSEY: you need to roar a little.
BARBARA: what does that mean?
DAVE RAMSEY: it means the next time he uses manipulation or blame you end the conversation. Calmly. Firmly. Without apology.
BARBARA: that feels harsh.
DAVE RAMSEY: what's harsh is a 26-year-old blaming his parents for his choices while still expecting their money.
They loaned their son $3,000.
He returned manipulation.
And they called in wondering if they were the problem.
They are not the problem.
They're just parents who loved too softly for too long.
Sometimes love has to roar.
A FRIEND ASKED ME THIS AND NOW I’M CURIOUS WHAT EVERYONE ELSE THINKS.
Say you have over $130,000 in savings.
Your spouse has close to $60,000 in private student loans.
The interest rate?
12%.
That’s roughly $7,200 a year in interest on a $60,000 balance if it stayed around that level.
Before having a baby, you looked at it as their debt.
Their loans. Their responsibility.
But now there’s a child in the picture.
And suddenly, that 12% debt doesn’t feel like just your spouse’s problem anymore. It affects the same household. The same budget. The same family.
So here’s the question:
Would you use a huge chunk of your own savings to wipe out your spouse’s high-interest debt?
Or would you keep the savings and let them continue paying it down themselves?
Genuinely curious how people would handle this.
Time is the only asset that doesn't have a bid.
You can't buy more of it. You can't borrow it. You can't earn it back. Every other thing you own, the house, the stack, the business is just a mechanism for converting time into money or money back into time. Most people spend forty years running that machine in one direction and never once run it in reverse.
I got out early. Not because I got lucky, but because I decided that time with my daughter, time with my wife, time on my hobbies, and yes, time laying on the fucking couch doing absolutely nothing, was worth more than another decade of climbing. That decision came with a cost: when you leave the rat race early, you still have to eat. Every month. Forever.
So let's talk about what nobody in this space wants to talk about honestly, income.
I hold cash. Real cash. And every time I say that, a maximalist appears to tell me I should be 100% Bitcoin, no exceptions, fiat is a melting ice cube, you're doing it wrong.
I completely disagree, and here's why. A minimum three months of essentials in cash isn't a lack of conviction. It's the thing that protects conviction. Cash is what stops you from selling sats at the bottom when the AC dies, the car needs a transmission, and the Airbnb sits empty for six weeks in the same month. Every forced seller in history was someone with great conviction and no liquidity.
The problem used to be that holding cash meant eating a 3% money market yield while M2 grew faster than that. You were paying for the insurance.
That changed.
Strive's $SATA is a $100 par perpetual preferred paying 13% annualized and since June 16 it pays every single business day, the first US-listed security to ever do that. Daily compounding takes the effective yield to roughly 13.9%. It sits on roughly 1.9x asset coverage with no debt senior to it.
Strategy's $STRC pays 12% on semi-monthly payments and trades just under par. Strategy is asking shareholders on October 28 to move all four of its preferreds to daily payments aimed squarely at closing that gap.
I started with STRC. When SATA went to 13% paid daily, I moved. Not out of loyalty to anyone's ticker, I want the most for my money, because I actually need the income. Especially in a bear market. Especially because I'm not collateralizing my Bitcoin right now. If I ever have to borrow against it, I will, happily, I see Bitcoin as something you eventually trade for goods and services. But if I have instruments that produce income without touching the stack, I'm going to use them fully.
Now here's who else this is for.
I came out of real estate. I know what yield actually costs when it comes with tenants. I have exactly one property left, an Airbnb and I pay a manager 15% a month specifically so I don't have to think about it. That's the premium I pay for my time, and it's worth every dollar. The income from that property funds the rest: a portion to Bitcoin, a portion to SATA, a portion to bills, and a portion to experiences.
Every real estate investor who's tired, every retiree who can't stomach an 80% drawdown at 68, every person who hasn't put in the years to hold through volatility they all need the same thing. Exposure to the Bitcoin economy without the behavioral risk of owning the volatile part. That's what this layer does. Common shareholders absorb the swings. Preferred holders get paid first.
Say the honest part out loud, though: these are not savings accounts. STRC traded as low as $71 during June's selloff. The dividend rate is variable. You're taking on real credit risk, perpetual duration, and exposure to Bitcoin's price through the issuer's balance sheet. If BTC goes to $30K and stays there, coverage math gets ugly. Anyone selling you a 13% yield as risk free is selling you something.
But understood properly, this is one of the most important products to appear in this market in years. Not because of the number. Because of what the number buys.
Peace of mind and financial wellness are closely connected. Knowing that your bills are covered, you have money set aside for unexpected expenses and you are making progress towards your financial goals can take away a significant amount of financial stress.
Financial wellness is not just about how much money you have. It is also about having enough control and financial security to face today’s needs while planning for tomorrow.