@JaredKubin@TMTLongShort 100b straightforward? Your sheet implies NNARR (ex META/distill) needs to dbl q/q in 4Q for that to happen. Yet 3Q NNARR was down vs 2Q. Unless I’m missing sthing
@jturek18 Really interesting. I do think the fed cut market is on the exact number. PM is pricing 20% odds of exactly 2 cuts. If we sum across the 2+ contracts the implied odds of 2+ are 43%. Closer to the 56% pricing of unemp at 5%+
@ChrisChavez Honestly thought you were on the bike till the very end. Your gait and arm swing doesn’t look diff from theirs tbh. They just maintain it for another 5.5mi..
@Floebertus@CuriousinHell cause it's not obvious. just how it's not obvious how they achieved 25% net margin in q1 despite being between 15% and 19% throughout 2024. nor was it obvious growth would slow sequentially last q. im long, dont get me wrong - but it's not a cake walk
@CuriousinHell@Floebertus 3. $3.5m CFO will mostly convert to cash on the BS. I have PF Q1 cash at $12.7m
4. At $0.75, PF EV is $44.3m. Q1 CFO annualized is $14m. But let's say FY25 CFO is $12m. That's 3.7x EV/CFO on decelerating numbers.
Seems like good r/r for a debt-free growing biz, however choppy.
@CuriousinHell@Floebertus Thought I'd update this graph + share some thoughts since they pre-announced q1'25.
1. $18m of rev is an ATH and lends credibility to the "this is not 2022" claim
2. $4.5m net income implies meaningful margin expansion - probably higher GMs as opex is lean
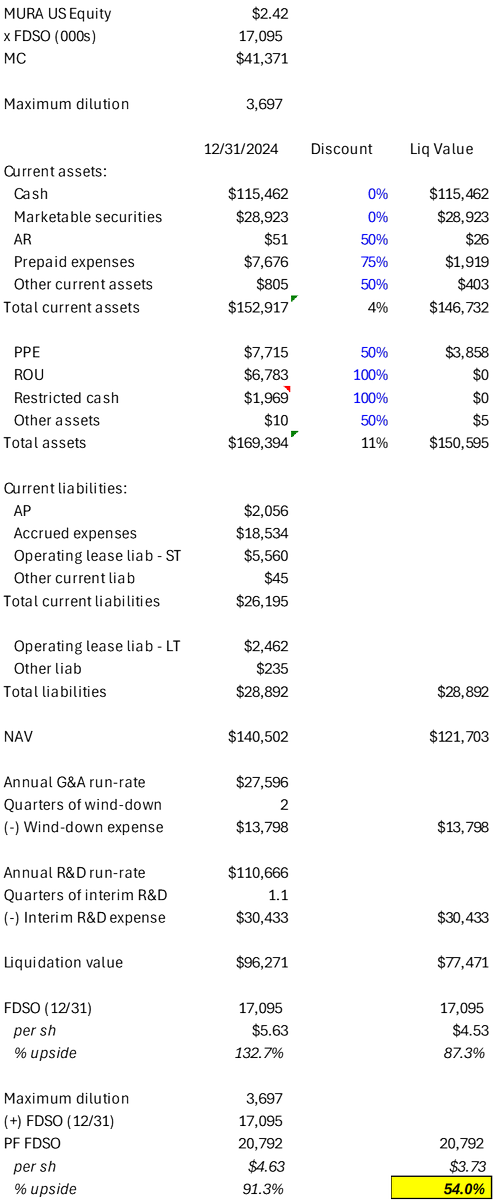
@Biotenic I get to $3.70 / sh via the below. Might have missed some parts (e.g. NOLs). But main diff is opex. FY24 G&A expense was $27.5m. $54m seems like a ton, esp b/c you're modeling this in addition to the $9-10m reduction charges given by the co..
@Lord_of_Biotech@everyonehatesp1@ToffCap@InflexioSearch By no means a sure thing. But given the RIF and suspension of the pipeline, what are the realistic outcomes? 2 most likely look like sale or liquidation. Both would likely be accretive, after accounting for wind-down, dilution, etc.