quand on sait que tiktok recrute à coup de millions des ingés en neurosciences comportementales et des spécialistes du design persuasif pour hacker nos circuits dopaminergiques, je me félicite chaque jour de n'avoir jamais créé de compte sur cette plateforme mdr
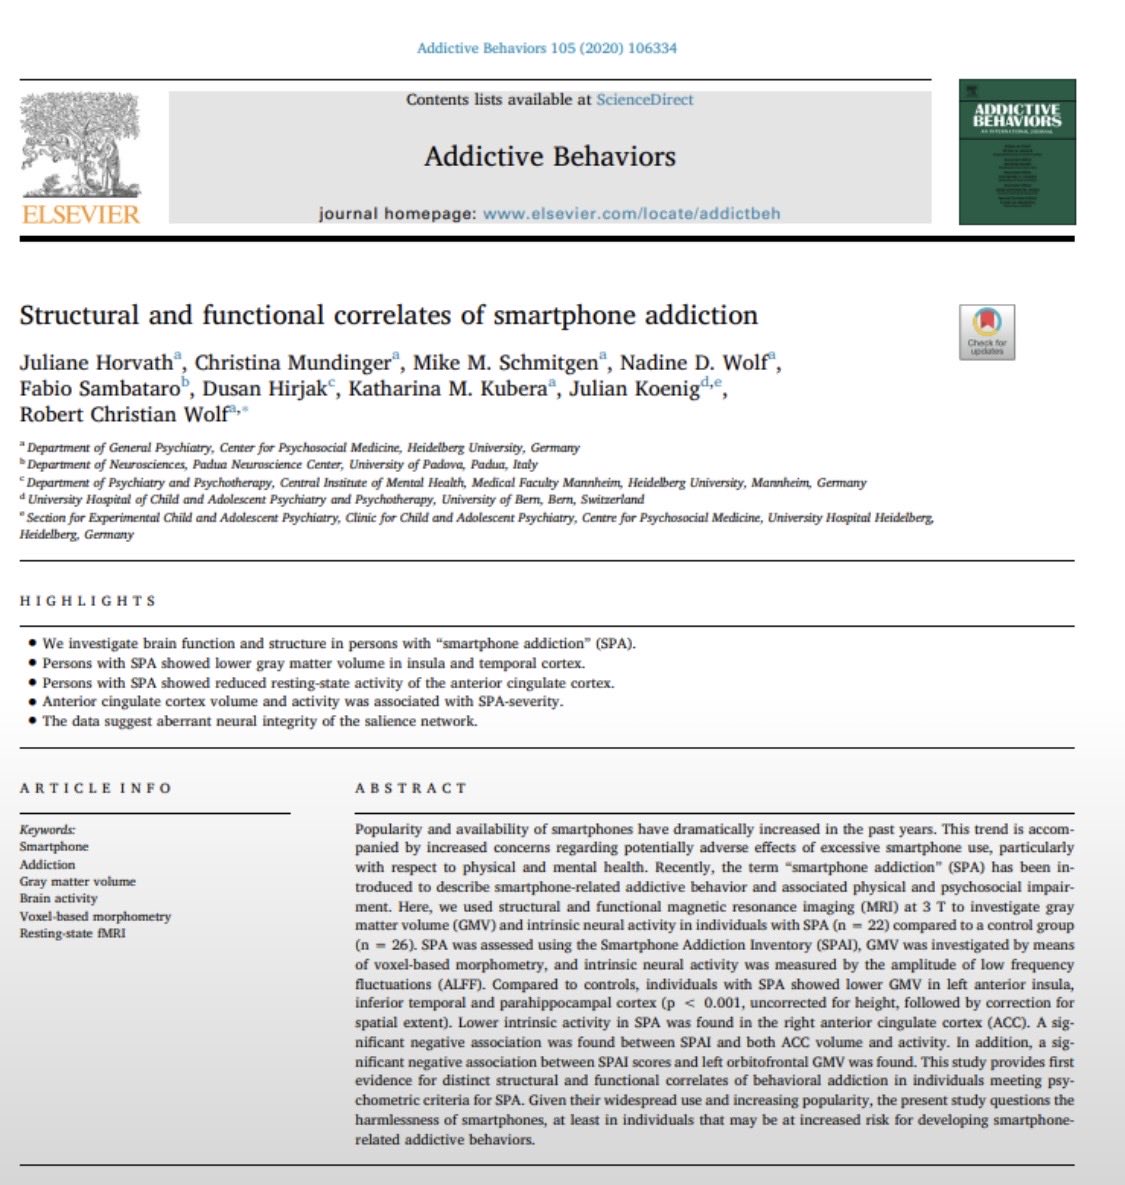
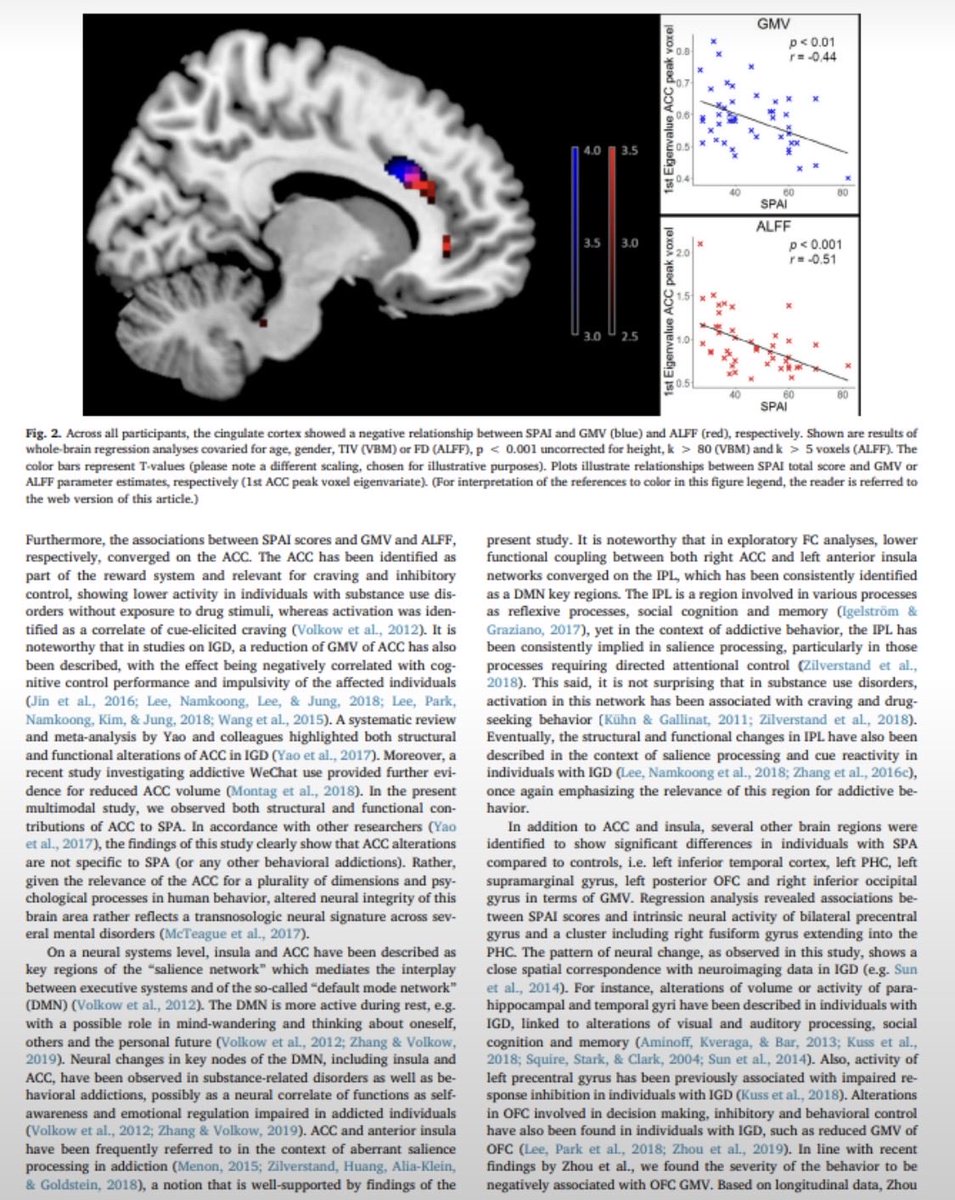
regardez ces études scientifiques en IRMF et eeg qui montrent très clairement quele format vidéo court attaque directement le cortex préfrontal et le cortex cingulaire antérieur (pour info ces zones gèrent le contrôle exécutif, la prise de décision et la régulation de l'attention)
sachez qu’een bombardant le cerveau de micro stimuli imprévisibles, l'algo altère la densité de matière grise et réduit l'activité du réseau par défaut & cette surstimulation permanente entraîne une incapacité chronique à penser à long terme et détruit la capacité à être focus, 2 facultés qui pour moi sont littéralement indispensables à notre époque pour construire l'avenir
bref je pense que refuser d'entrer dans ce système, c'est simplement préserver son autonomie cognitive et la souveraineté de sa propre attention face à une ingénierie de l'addiction taillée sur mesure
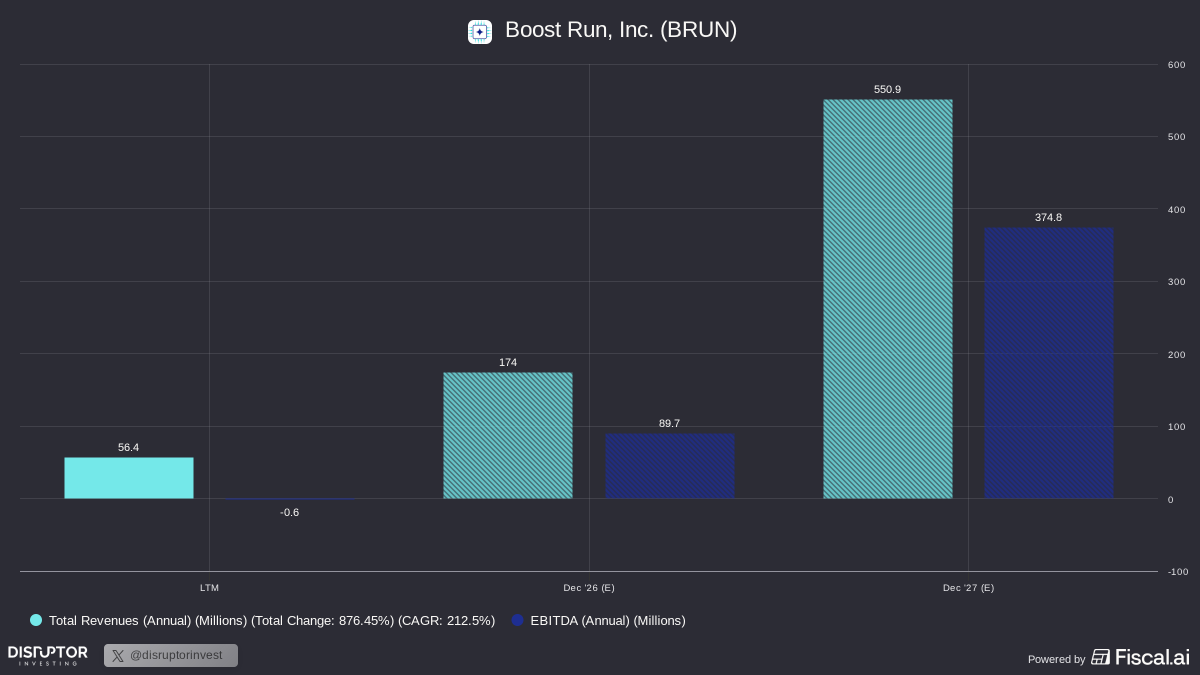
If you like the $PLTR x $NBIS news today and what it all entails, then I'd imagine you'd really like $BRUN.
It's hiding in plain sight, but I can't imagine it will be for much longer. While the analyst estimates I've included below are impressive, I still think they're too low given what we know today.
Please do your own research when making investment decisions. This is not financial advice.
So the flywheel is
NVIDIA invests in Thinking Machines → expands compute needs → they already have a massive multi-year deal locked with $BRUN (NVIDIA Preferred Cloud Partner + Blackwell Exemplar) → $BRUN buys more NVIDIA hardware to fulfill it → NVIDIA books the revenue.
Thinking Machines already has a direct, non-cancelable contract with Boost Run.
• $471.7 million total contract value
• 36-month term
• 5,000 NVIDIA B300 GPUs
• Signed May 2026
That’s real committed revenue sitting on $BRUN’s books right now — part of their $1.9B TCV.
$DELL ON AI INFERENCE DEMAND:
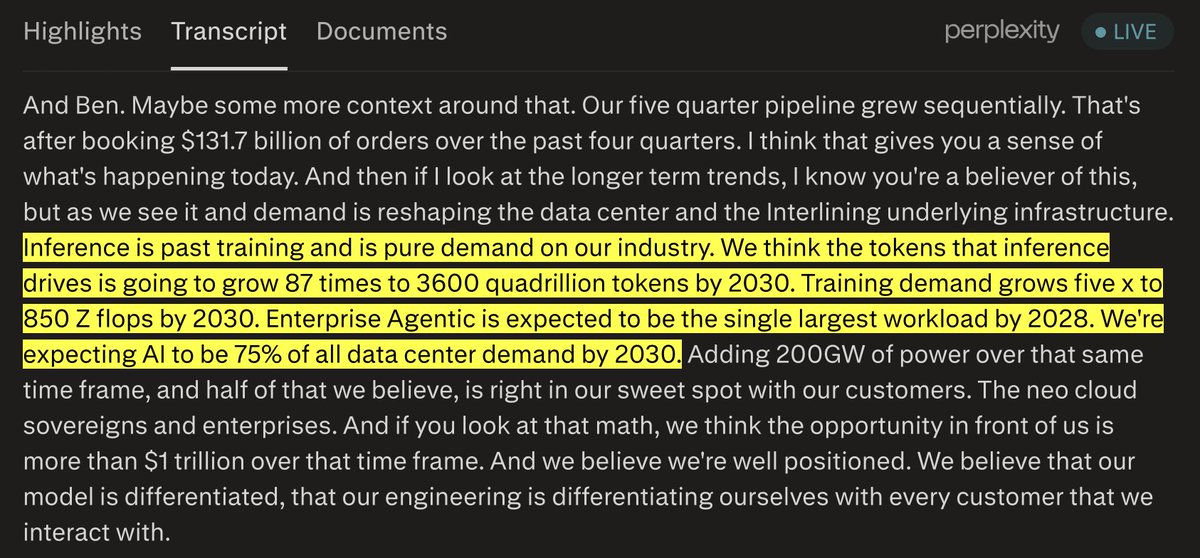
“Inference has passed training and is pure demand on our industry”
Dell expects inference token demand to grow 87x to 3,600 quadrillion tokens by 2030, while training demand grows 5x
“Enterprise agentic to be the single largest workload by 2028”
$KC built the rails to capture it.
The trade: options price a ~14% move, history shows avg move is only 2-6%. Analysts now model narrowing losses (-$290M vs -$343M) + improving EPS — first Q the Street expects margin to catch up. Risk: gross margin fell to 12.8% in Q1 on AI infra
$KC into Wed earnings. Kingsoft Cloud is the most direct DeepSeek infrastructure play in China cloud. Built full deployment tooling for V4 — one-click images, bare metal w/ domestic chip adaptation, distributed multi-machine inference via StarFlow, even gov cloud support.
Not just “hosting AI” — productized DeepSeek specifically.
Result: AI cloud went from 26% → 50%+ of public cloud revenue in under 2 years. Q1 AI gross billings +90% YoY, token services revenue up 53x Jan-Apr 2026. DeepSeek’s efficiency breakthrough = more total inference demand
$BRUN EARNINGS OUT LETS GO
“Demand is not our constraint. Everything we sold this quarter was contracted before the hardware was energized, and the pipeline behind it is larger than anything we have seen in the history of this company."
Second Quarter and Year to Date 2026 Financial Highlights
> Total revenue for the three months ended June 30, 2026, was $31.1 million, a 270% increase compared to $8.4 million in the prior year period.
> Total long-term contracted revenue (TCV) stands at $1.9 billion.
> Added over $1 billion in contracts signed during the second quarter.
>Unrestricted cash balance was $120.2 million as of June 30, 2026.
2026 Financial Outlook
> Fiscal 2026 Annualized Recurring Revenue (ARR) Target: The Company expects to exit fiscal 2026 with approximately $400 million in ARR.
> Net Cash Flow Margin Target: The Company expects to achieve a sustainable Net Cash Flow Margin of 15% to 20% in forward periods.
Second Quarter and Year to Date 2026 Operational Highlights
> Completed a business combination on May 8, 2026, resulting in $114.1 million in net proceeds and transitioning the company to a publicly traded entity on Nasdaq.
> Currently operating six data center locations in the United States, with three additional sites scheduled to come online over the next six months.
> Expanded data center partnerships to add an additional 125MW of power, bringing total accessibility to 253MW.
> Fully committed and allocated a $1.44 billionpurchase agreement with Dell and currently processing a strategic procurement of an additional $4 to $5 billion in compute hardware across multiple OEMs.
> Entered into 34 new finance lease agreements for GPU servers during the first half of the year.
"This is our first earnings call as a public company, and over the past quarter, we have added over $1 billion in contracts signed," said Andrew Karos, Founder & Chief Executive Officer of Boost Run. "Currently our TCV stands at $1.9 billion. Demand is not our constraint. Everything we sold this quarter was contracted before the hardware was energized, and the pipeline behind it is larger than anything we have seen in the history of this company."
What a crazy week in AI! 🚀
DeepSeek V4 Flash
Seedance 2.5
MiniMax H3
Kimi K3
Instella
ID V2V
Crisper Whisper
Inkling Small
Prism
Gemini Robotics 2
Wonder
Redesign
Phi Zero
& more!
Watch the full recap:
https://t.co/Yvj7kxL4j8
Forge Nano $ATII is either wildly overpriced or dirt cheap, and which one comes down to a Phase 2 Gigafactory that is still in the early stages of buildout.
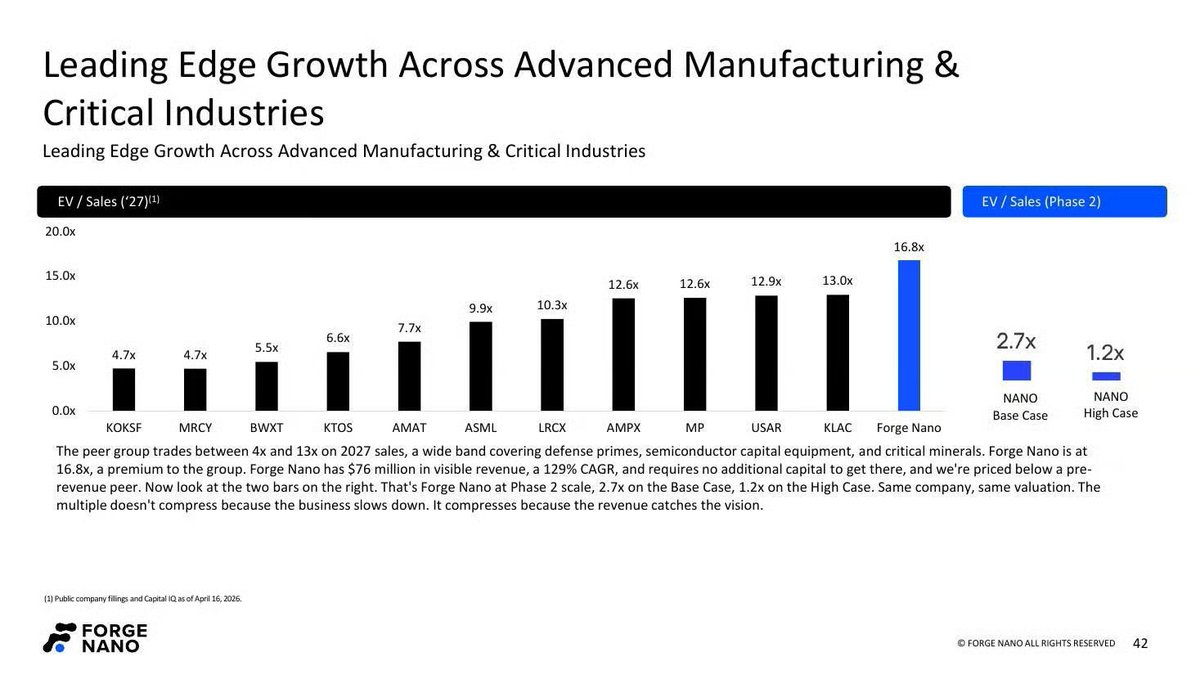
At the $10.00 deal price, the pro forma enterprise value is $1,278.9M, which management frames as 16.8x 2027 projected revenue of $76.1M.
At today's $10.88/share, using the deck's 159.6M-share count, equity value runs ~$1.74B and EV ~$1.42B ($1.74B less $317M net cash), or ~18.7x the 2027 projection and ~35x the 2026 one.
Since both projections carry grants ($2.5M in 2026, $1.5M in 2027), the ex-grant multiples are ~37.7x on 2026 ($1,419M / $37.6M) and 19.0x on 2027 ($1,419M / $74.6M).
Now look at what the market is being asked to prepay.
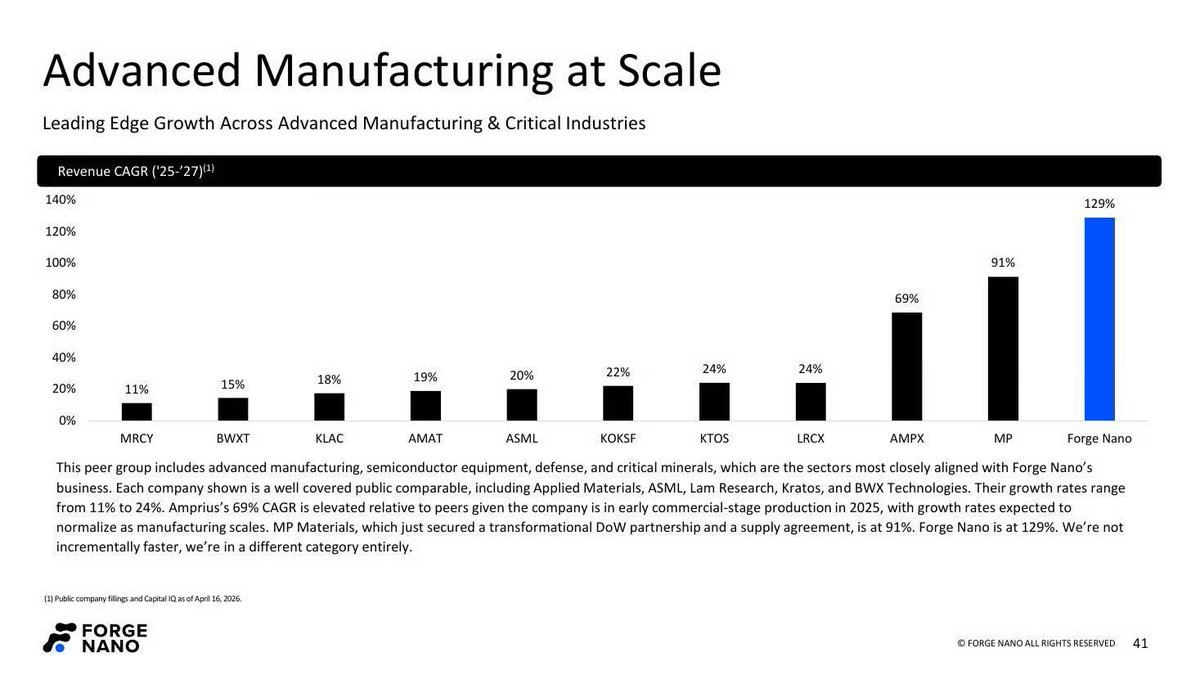
Growth-stage battery peers (QuantumScape $QS, Eos $EOSE, Amprius $AMPX, and others) trade between 4.7x and 13.0x 2027 sales, with 2025-2027 revenue CAGRs of 11-91%. Forge Nano's deal is priced at 16.8x with a claimed 129% CAGR, above every name in its own deck.
The bull case is that the buildout does the work. At Phase 2 base-case revenue of ~$460M, today's EV works out to ~2.7x sales, and ~1.2x at the $1B+ high case, cheaper than every peer on the chart above IF the capacity gets built and sold out.
CSO Lance Little's line on the investor call was that buyers today get Phase 1 revenue with Phase 2 optionality "essentially for free," and that the multiple compresses "because the revenue catches the vision."
In other words, the current price already pays for clean execution of a factory that starts construction this summer and opens in 2028, plus a 300mm tool line that doesn't exist yet.
The share count is the other half of the valuation. The S-4's basic count of 150.3M shares becomes 293.6M fully diluted, all before the 10% equity plan.
Getting from 150.3M to 293.6M takes 11.9M SPAC warrants at $11.50, up to 30M PIPE warrants at $10.00 or lower, ~11.4M converted Forge Nano warrants and options (OIC's mostly at a $2.66 effective strike), and the 90M earnout shares.
Upside scenarios clearly dilute themselves. At $15.00 the first 30M earnout shares release, at $20.00 the next 30M, and every warrant tranche is in the money along the way.
Getting to a $25.00/share stock requires the market to absorb roughly double today's share count on the way up. That ignores debt, which is fair, since the only corporate debt is the $10.4M OIC note.
So whether today's ~$1.42B EV proves cheap or absurd comes down to execution against dated, checkable milestones: Construction starting now, project financing signed, H2 2026 revenue at a ~$12M quarterly pace, tools shipping to named customers, and Morrisville cells off the line by Q2 2028.