@EEberhartinger @OECDtax Not taxed. The law that provides for the approximation of the tax base to ifrs explicitly determines that fair value will be recorded separately and taxed on realization. A common academic question here is what if the legislator didn't say that. But in practice we dodged that one
@EEberhartinger @OECDtax Also,accountants tend to prefer to be as far as possible from the tax legislator (historical reasons).Still, I don't think we will be better off with the separation.If the acc rules are good from shareholders perspective,then I don't see why they are not ok to identify ab. to pay
@EEberhartinger @OECDtax Currently we use acc profit with tax exclusions. But bc of ifrs complexity and open discussions the rev service just put out a proposal to set the tax profit further appart from accounting (though not entirely).
Happy to share that our latest #research on the effects of #taxtreaties on #FDI has just been published with @SpringerNature in International Tax and Public Finance! Available now online with open access: https://t.co/rUM3Y29uew
@FaccioTommaso The revenue loss argument has been used in favor of changing the current system, but I’m not aware of actual econ impact analysis backing it up. Would be really useful but with a huge number of variables...
Brazil and TP: a new developments in the approximation to the OECD standards were just announced. Attached, a group of academics provides insight. In short, some features of the Brazilian approach deserve to be improved and maintained - not discarded. https://t.co/lnqFrAIp02
@EUTAX131 Fair point, well taken. The idea is a simplification that has its limitations, including this one you point out. Was thinking mostly of wealth redistribution
@EUTAX131 Exactly. The idea being to let the market determine behavior (efficiency). Equity and distribution concerns could be addressed as effectively by public spending...
Discussing tax reform in Brazil. Refreshing reminder by Prof. Marcos Lisboa: there is nothing you can achieve with the tax system that you can’t achieve with public spending. Time for tax neutrality! @lacaz_martins
A warm welcome to my Oxford successor, whose appointment was announced today. I am pleased to be staying on in a part time capacity as Professor of Tax Law and Policy. Tsilly will hold the statutory Chair of Taxation Law. Look forward to working with her https://t.co/ZylRSlGTKd
Information flyer of my book "Jurisdiction to tax corporate income pursuant to the presumptive benefit principle" edited by @KluwerLawint https://t.co/HAvd651Krq
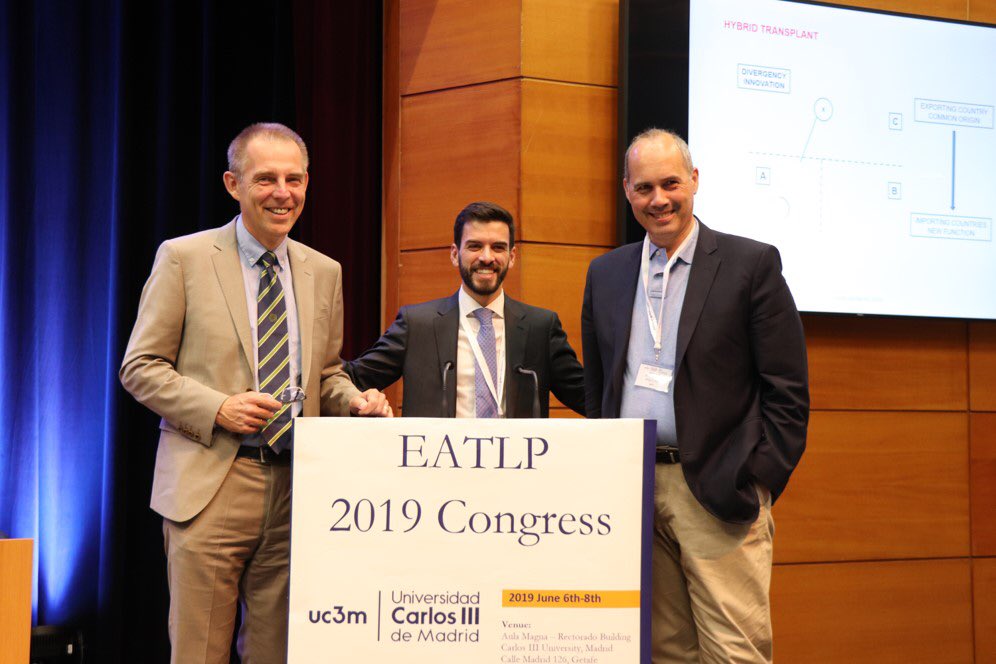
Yesterday was so special: I received the European Academic Tax Thesis Award for my PhD thesis from the EATLP and @EU_Taxud. The book will be out soon - Conflicts of international legal frameworks in the area of harmful tax competition: the Modified Nexus Approach)