@theallinpod@altcap Just recorded a few minutes of the Pod in Claude app (Fable5). It guessed the speakers and referred to the episode instantly. Mind boggling!
@Rainmaker1973@grok what's the real deal when the size of each satellite is added up to compare the size of the orbit? Is it as bad as the video describes?
@Jason@balajis
The Network State is getting popular in Chennai. Nice to see the reach in the local TV news channel in Tamil Nadu, India.
@MalaimurasuTv
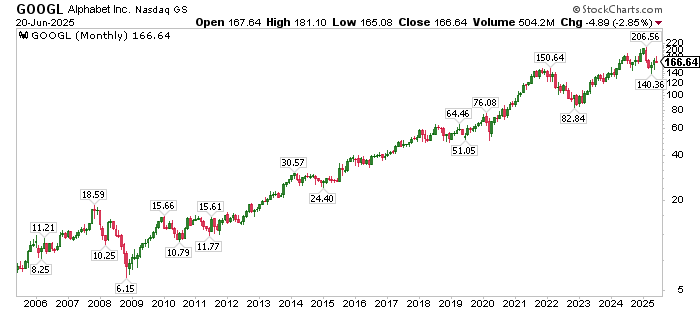
The $GOOGL bullish counter
Hat tip to AI
1/ “Looks like a bargain… but it’s a trap”
Counter: Google isn’t just “cheap vs. peers”—it has among the best margins, network effects, and cash generation in the market. Valuation multiples reflect prudence, not trouble. A business with 25%+ operating margins, $100B+ in FCF, and high moat resilience is rarely a trap—it’s a cash compounder.
2/ “Search is in structural decline”
Counter: Search is evolving, not dying. Google still handles 8.5 billion searches/day. SEO spam and clutter are being actively addressed. Furthermore, Google's own AI search (SGE/Gemini) keeps users within the ecosystem. Engagement remains strong in intent-based searches (e.g., travel, shopping, local services) where ad value is highest.
3/ “AI hurts Google’s business”
Counter: Google is not just defending itself—it’s leading in key AI infrastructure. Through TPUs, DeepMind, and Gemini, it's building both consumer and enterprise AI solutions. AI enhances other Google services (Cloud, Ads, Workspace) and helps maintain its ecosystem moat. Margin dilution is real but temporary—like AWS early on.
4/ “Cloud, Android, YouTube don’t move the needle”
Counter: They do move the needle—just not all at once. Cloud is now a $36B/year business growing 25–30% YoY, and finally profitable. YouTube monetization and Shorts are accelerating again. Android is a royalty and data engine embedded across the world. None are moonshots—they’re durable pillars that will drive the next decade’s growth.
5/ “Conglomerate discount, no sum-of-the-parts premium”
Counter: True, the parts aren’t broken out—but that doesn’t mean they’re discounted. Alphabet’s tight integration creates ecosystem defensibility, not inefficiency. YouTube, Android, and Search reinforce each other. Spinouts may unlock value—but synergy and platform scale are already reflected in margins and earnings power.
6/ “Costs are exploding, margins falling”
Counter: Alphabet is actively trimming fat. It has cut over 12,000 jobs in the past 18 months and is slowing hiring. Operating leverage is improving as Cloud turns profitable and AI infra becomes a long-term investment. Margins may dip short-term, but Alphabet still runs at ~25% operating margin—a level most tech firms would envy.
7/ “Capital allocation is weak”
Counter: Google is buying back tens of billions in stock annually. In 2023 alone, it repurchased $70B in shares. While it doesn’t pay a dividend, the buybacks are accretive and reflect capital discipline. Unlike companies that return cash because they can’t reinvest productively, Alphabet has both optionality and resources.
8/ “Regulatory pressure is real”
Counter: Regulation risk is baked in. Google has been dealing with global antitrust cases for over a decade. Yes, it’s a headwind—but a known one. Investors have already discounted regulatory uncertainty. Moreover, any forced divestitures (e.g., ad stack) could even unlock value if spun out.
9/ “You’re left with a fading compounder”
Counter: Not fading—maturing with upside. The ad business continues to grow at high single-digits. Cloud is scaling. AI is being productized. YouTube is second only to Netflix in digital viewing hours. Google isn’t over-understood—it’s often misread as static when it’s evolving steadily.
10/ “It will grind sideways”
Counter: Flat performance isn’t a permanent destiny. Microsoft was considered a "dead stock" for a decade—until Azure and Satya transformed it. Google has the balance sheet, talent, and tech stack to surprise to the upside, especially as monetization of AI, YouTube, and Cloud accelerates.
11/ “Cheap ≠ good. Dominant ≠ invincible.”
Counter: True—but cheap + dominant + innovating ≠ value trap. Google still owns irreplaceable infrastructure (Search, Ads, Maps, Android, YouTube), is a leader in AI, and has multiple levers for reacceleration. It’s not a dying empire—it’s a cash-rich, platform-anchored tech titan transitioning into its next phase.