More Zoci data end of year and also Atopic Derm data on an asset I didn’t cover. The main question is will the strong ORR (and low AEs) translate into strong OS
$ZLAB LONG PT $60 $6B MC
-90% frm $192 Jan-’21 ATH
-55% off the 52wH
$2B MC $760M cash $1.4B EV
China Rev today ($500M) already supports EV, 2x EV/S > $1B plus DLL3 ADC Zoci potentially worth $3-$5B EV.
Rev: $460M 25A, $500M 26E $600M 27E $1.3B 28E (vs company 1Q26 guide to $2B Rev 28E)
2x multiple for low margin China Rev implies $1.3B x 2 = $2.6B EV 28E
+ $760M cash ≈ $3.4B > 75% upside from today on China commercial alone
🫁 Zoci (DLL3 ADC): best-in-class SCLC. ORR 67–79% vs 40–50% for $AMGN tarlatamab. Gr≥3 TRAE 16% vs 27% for Tarla, with 0 CRS/ICANS — no boxed warnings, no inpatient step-up. No CRS, no titration means community oncs can give this without needing to monitor for CRS - massively expands commercial oppty.
Zoci peak sales > $3B+
Even with CRS, $AMGN Tarla annualizing $1B peak just 2Ys after launch in 2L SCLC only - could reach $2B in 2L. 1L is 2.5x larger. $AMGN guiding to $3B-$5B for Tarla.
M+A
$ABBV bought Rova-T (DLL3 ADC) for $6B upfront. Also $AMGN currently running combo trial with Zoci and Tarla and suddenly has revenue gap with $CCXI Avacopan/Tavneos collapsing.
$APGE and their longs have spent years saying that Dupi/Lebri were underdosed and that higher dosing was going to improve efficacy. Today their data show the inverse of that, with high dose underperforming mid dose in every way.
Watch how fast their management team completely abandons what (until today) was their key narrative now that it no longer suits them..."Ignore the 1,000 times we said that exposure thing...this thesis is intact and better than ever!"
This management team's constant spin bullshit drives me crazy (like saying ISRs are the biggest problem for Dupi - objectively and easily falsifiable bullshit. Only was that was not a *lie* is if you accept they're unintelligent enough to misunderstand what an ISR is. Which is worse?).
Anyway, look at their long-awaited high dose P2b results, and compare those to Lebri's (Ebglyss) P2b results...Sorry $APGE, I'm not impressed.
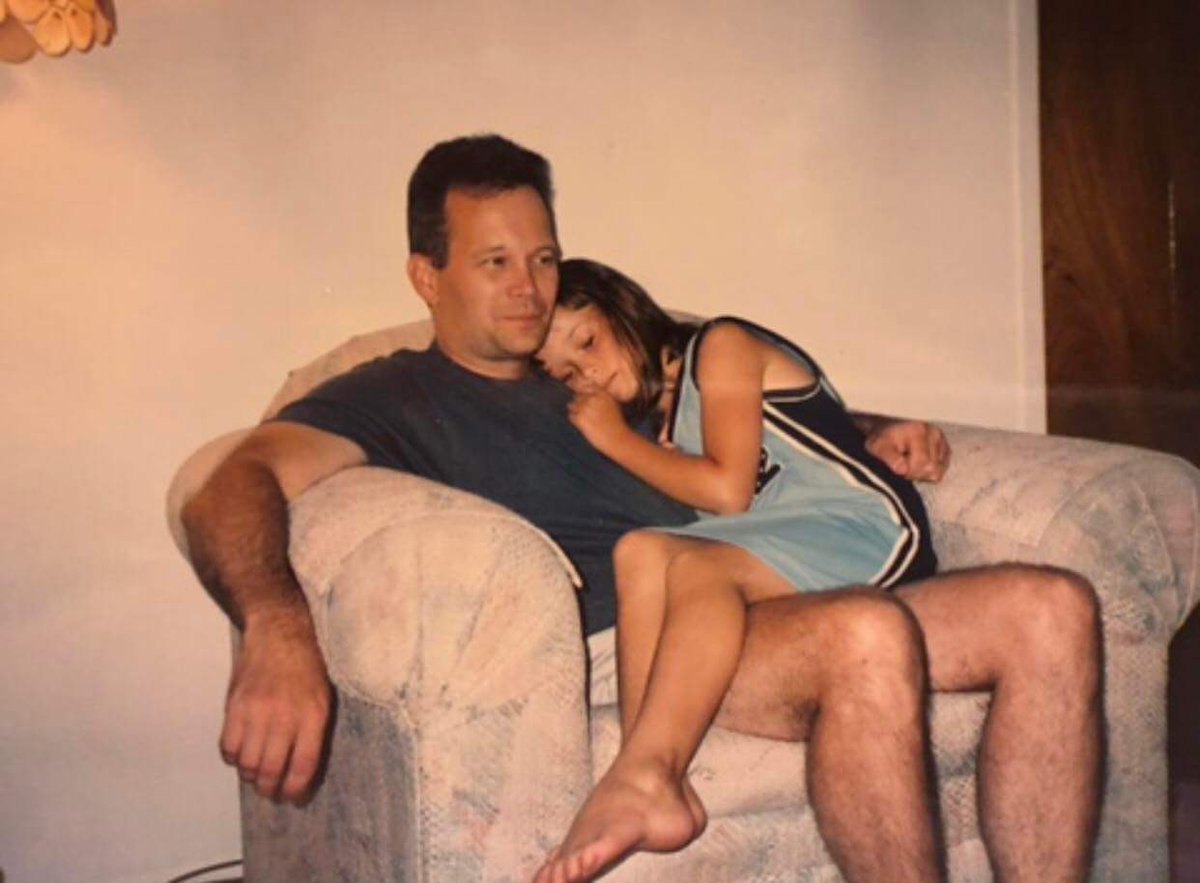
This is me & my dad. My dad before HD changed him into someone I didn’t know. He suffered for years as HD slowly deteriorated his brain and then he chose to end his life on his own terms. An HHS official just called us “the swamp”. Make it viral #IAmtheSwamp@AndrewNixonHHS
@pemulisking It’s priced like it’s a zero right now - I think even a single monotx response in the mono cohort (given Alpelisib has an 8% ORR) an then good tolerability and ORR with Fulv. The pan inhibitor in pipeline could also be interesting
$OKUR
Alpelisib QD covers EC80 PI3Ka for 16/24h
It gets monotx responses in mBC (8%) and a mPFS of 5.8mo (where PFS is what actually matters in BC)
OKI-219 900mg covers EC80 for 10/12h (BID dosing)
Therefore it should get monotx responses
2024 SABCS update only had n=2 patients at 300mg dose with follow-up beyond 60 days, no patients out beyond 60 days at either 600 or 900mg - kinetics of responses in mBC typically slower than other indications
219 is exceptionally clean - G1 AEs only at 900mg
mBC is about combo therapy - so cleanliness is next godliness
n=70 patients dosed with data update 4Q (likely around SABCS Dec) split between monotx and fulvestrant combo
Comp is Scorpion Tx taken out for $2.5B
OKUR trading at $50M MC
Risks
Burn is high
Less mutational coverage than Scorpion
Lower mgmt pedigree vs Scorpion
Escape mutations eventually
Financing overhang
mBC requires big studies and is capital intensive
Remarkable that US spending on pharmaceuticals is just ~1.6% of GDP. Amazingly good value for money considering the welfare gains. (And especially given the extent to which the US subsidizes the rest of the world.)
$FULC I think people confused the recent increase with total HbF: mean HbF increased 8.6%, bringing total HbF to 16.2%. 7/16 patients achieved HbF >20% - which is effectively curative. I think stock finishes day at $10.
these are the values if $ABVX launches equivalent to:
Entyvio: $200/share
Rinvoq: $350/share
Skyrizi: $600/share
this assumes the patent(s) hold up! (2039 LOE)