Buchempfehlung: Die Schweiz war nicht das Armenhaus Europas im 19. Jh.. Der Schweizer Finanzplatz schuldet seine Bedeutung nicht WKII. Der Schweiz ging es immer gut, wenn der Staat und Pensionssysteme schlank waren. Einfach verständlich, voller Daten und mit viel ❤️ zur 🇨🇭
Kpler's Michelle Brohard suspects some Gulf producers are quietly paying Iran tolls for safe Hormuz passage, possibly 10-20% of cargo. The claim is unverified, but it may help explain why Brent sits near $100. @OilandEnergy
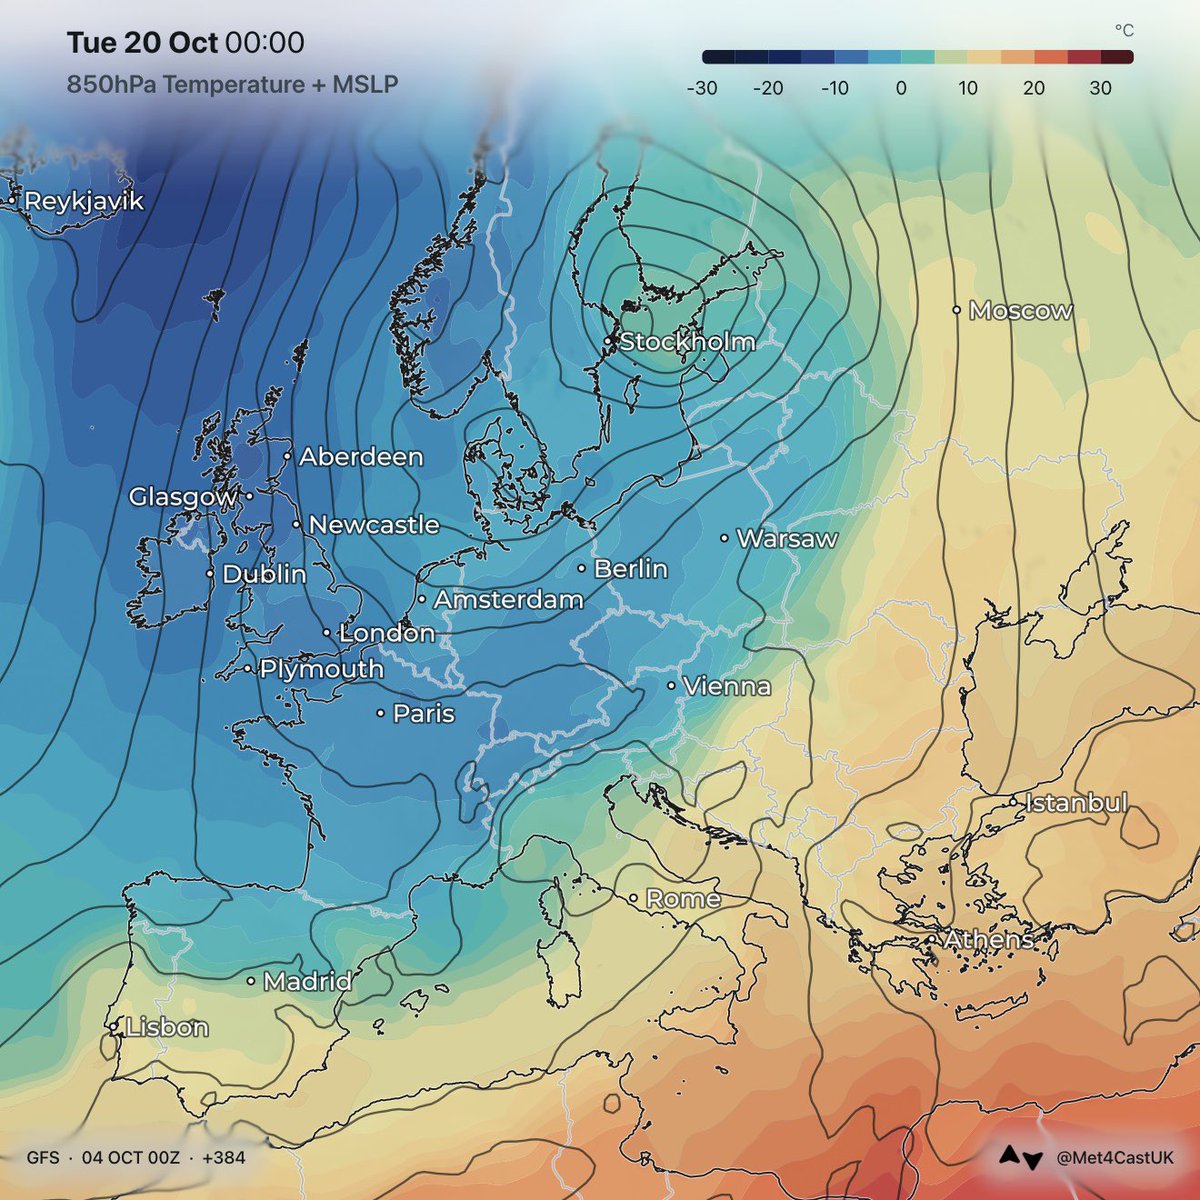
The first silly chart of the season goes to the GFS with this unseasonably cold northerly right at the end of the run.
Unlikely to verify of course, it’s a long, long way off.
so coatue +12% ytd underperforming $QQQ 45% and $SMH 82%
if AI was real, how can @plaffont with basically unlimited resources (>$1.5bn mgmt fees per year alone) underperform that much?
either AI is not that great for investing, or information asymmetries have been arbitraged
The latest energy windfall tax in Europe is now enacted, this time in Poland.
Europe desperately needs more refining capacity and more product supply. High cracks are the market screaming exactly that: we need investment. Orlen owns 850kbpd of refining capacity, roughly 60% of it in Poland. Quite big.
Instead of fast-tracking permits, removing bottlenecks and incentivising new capacity at Orlen, in all its wisdom Warsaw decided to tax the capital that could build it at incredibly high rate of 60%.
We need more supply, not more taxes. One policy failure after another.
@sikorskiradek@donaldtusk
France, Germany and Italy use both CSE (case #2) and EO (case #3) storage.
The mix of the release will be key to assess market impact. My take is that they started with EO storage, and thus barrels physically already at the refinery have been freed for release. This is how you frontload the release in the first 20 days, as this is the most readily available SPR which is mobilizable on short notice.
Those barrels were most likely hedged by the refinery hedging desk using short ICE Gasoil future positions - charging the negative carry plus financing to the governement on each roll, but that is story for another day.
Those hedges had to be lifted, hence the brisk future buying activity on front ICE Gasoil futures after the announcement.
That also means diesel released deep inland Germany and France, far, far away from ports - and that is deliberate.
Neat paper!
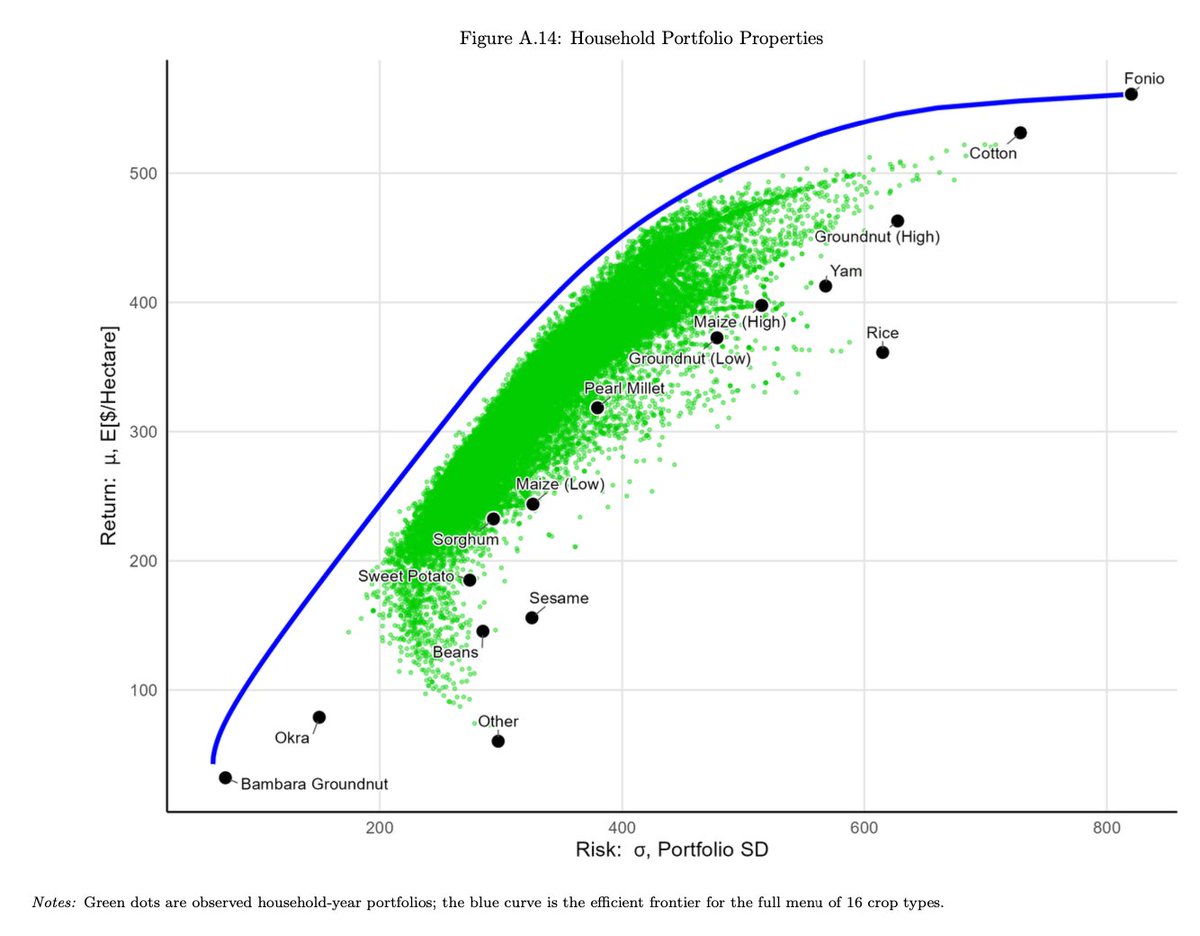
Small-scale farmers in low-income countries are solving an incredibly sophisticated portfolio optimization problem under difficult conditions.
Even so, many farmers are close to the efficient frontier. Unconditional cash helps them get even closer.
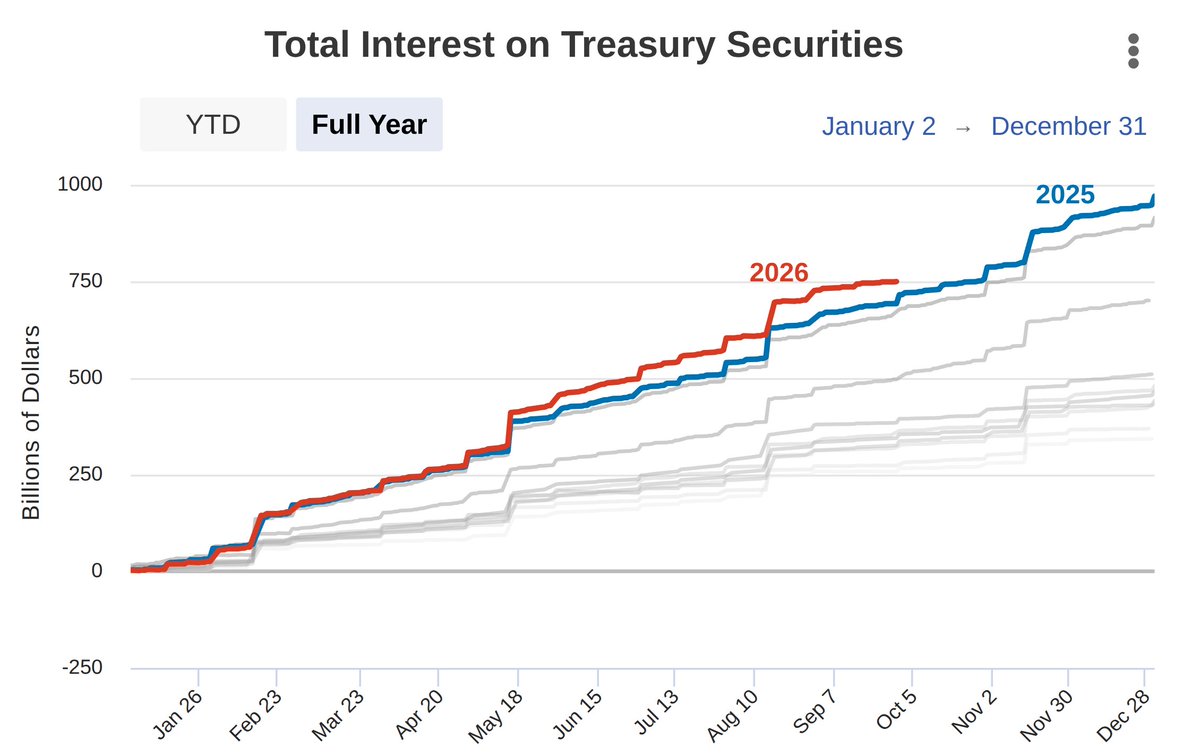
Which means the Federal deficit will absolutely go bananas from here. The debt needs to be rolled.
You don't have to believe me, read Wharton School of Management opinion.
https://t.co/zK49pb02mN
Current interests payment on Federal debt are a trillion a year already, en route to reach 2 trillions by 2029.
Tick tock.
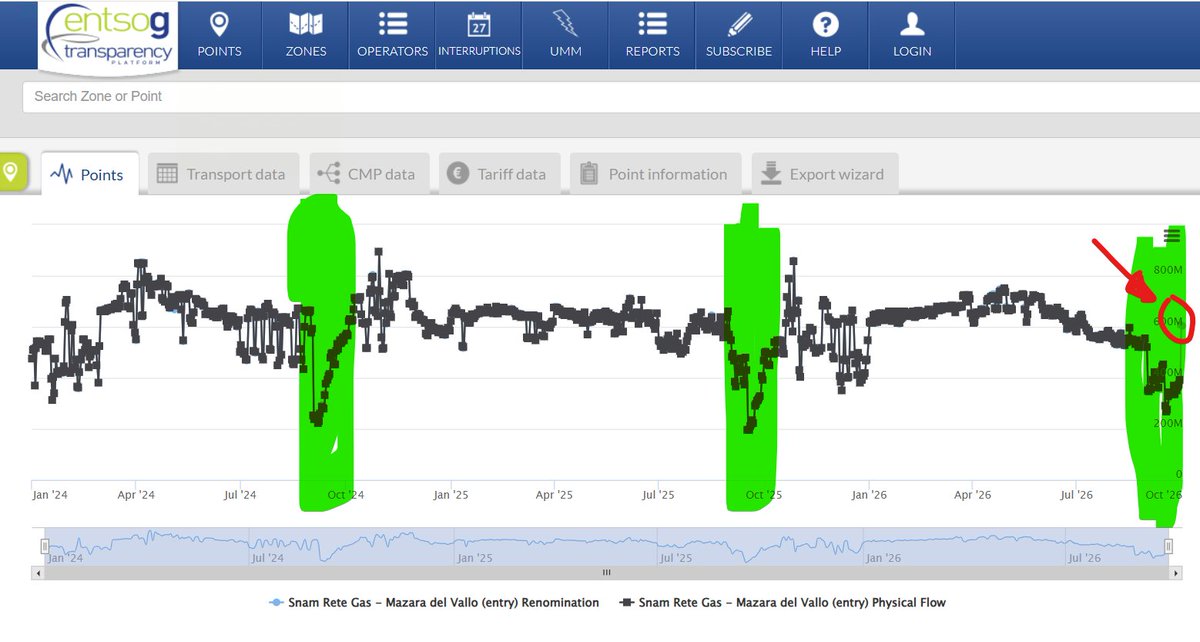
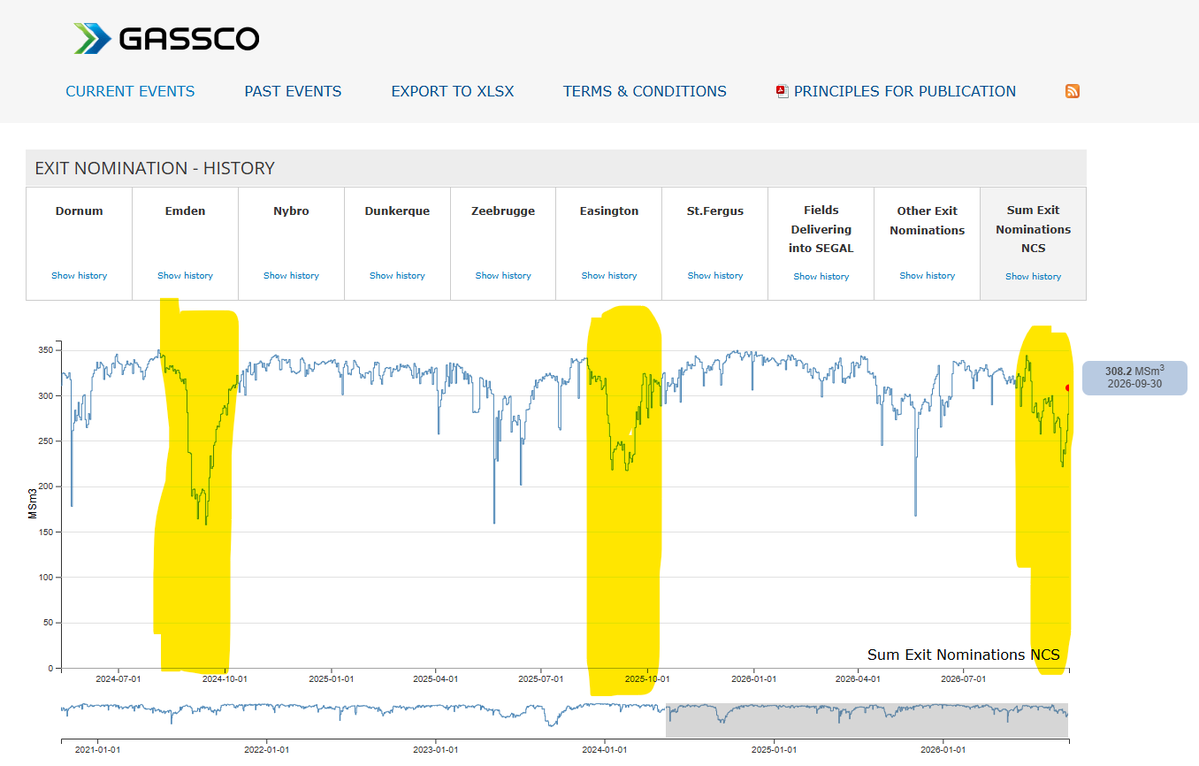
A comparatively light Norway September #natgas maintenance month ends, with flows back in the 300s. All adding to a late surge in storage.
Algeria-to-Italy vols also jumping back as we complete another trip around the sun.
Happy New Gas Year, folks.
#TTF#LNG
I’ve never liked the short OAT trade. French net debt less financial assets they own has always been rather manageable.
French govt owns a lot of assets - push comes to shove it will simply be privatisation.
France continues to lead Europe in space, AI, defence and energy- several of the industries of the future _- if and when Europe decides to Reindustrialise - France will be the biggest beneficiary
@ira_joseph@GastechInsights@ColumbiaUEnergy nice pod, thanks ira and colleagues
2 core points I agree with:
Hybrid warfare has expanded in EU & it is naive to assume Russia won’t push for another energy shock
LNG market will quickly be crazy oversupplied. 30+eur Cal28 TTF is a pipe dream looking at any sensible balance