Germany pays roughly €4bn a year for congestion management. That’s the cost of a grid that can’t always move power from A to B.
Batteries can bring that number down. But integrated poorly, very large ones could push it up.
Wilhelm Kiewitt, Head of Energy Economics at @50Hertzcom, makes two points worth sitting with:
TSOs are still learning how batteries work commercially. Operators, investors, developers, tolling. Understanding that structure matters for how batteries are integrated.
Bringing congestion costs down means not adding uncertainty. That’s why the four German TSOs published joint battery requirements in May, aiming for a sweet spot between operational freedom and predictability.
Full conversation below
#BESS #EnergyStorage #Germany #Energiewende #GridCongestion
NEM: the connection application stage is meant to run 80 days under the rules, but the median is 8 months. The real delay sits downstream. Proponent implementation has nearly tripled since mid-2024, from 6.5 months to 20.3 months, with no deadlines governing that stage.
Great Britain: connections reform has pushed 6.5 GW of the BESS pipeline back by at least six months. Counterintuitively, that helps the projects that do connect on time. Under the same market conditions, slower buildout means less competition and higher revenues per MW.
Congratulations to the BW ESS team on closing financing for Hams Hall, and to all their project partners.
It's really cool to see projects of this size come through, and I'm excited to see the scale of what's coming down the pipeline.
At a time when our power markets are increasingly stressed and we need flexibility, this is the news we need to see.
ERCOT: gas interconnection requests now total 79 GW, eight times the January 2023 level, as new solar and BESS filings fall. But little of it has arrived. Gas added just 10 MW in Q3, while solar synchronized 2.13 GW. The queue and the grid are pointing different ways.
As we get heat domes, we’re going to see growing system stress. Useful to see what’s happening in MISO
Also, if you’re looking at MISO, follow @willrawlmodo
A year ago, MISO prices couldn’t go above $3,500/MWh. This September, Real-Time prices reached the new $10,000/MWh cap on two separate days.
On September 17, 35 minutes at the cap were worth over $500,000 to a 100 MW battery. All of it was in the Real-Time market.
Here’s what happened, in two minutes.
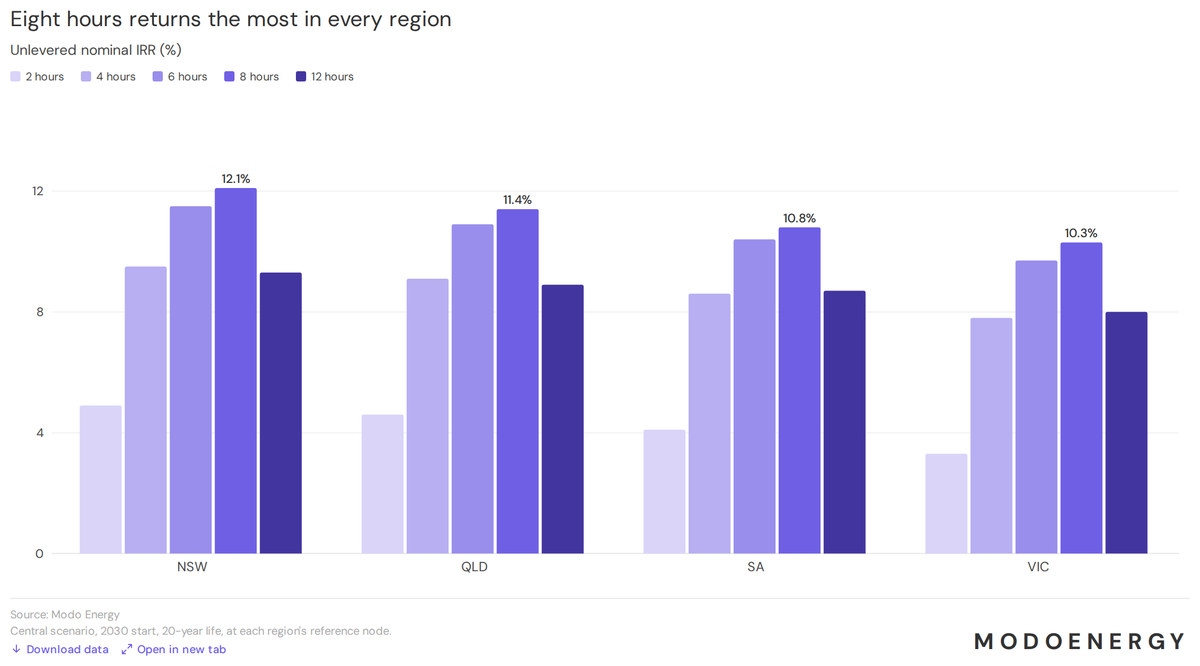
NEM: in Modo's Central scenario, an 8-hour battery going live in 2030 returns 11.1% across the mainland regions, the highest of any duration tested. Push to 12 hours and revenue rises 17%, but capex rises 37%. The daily price shape only pays out to about hour eight.
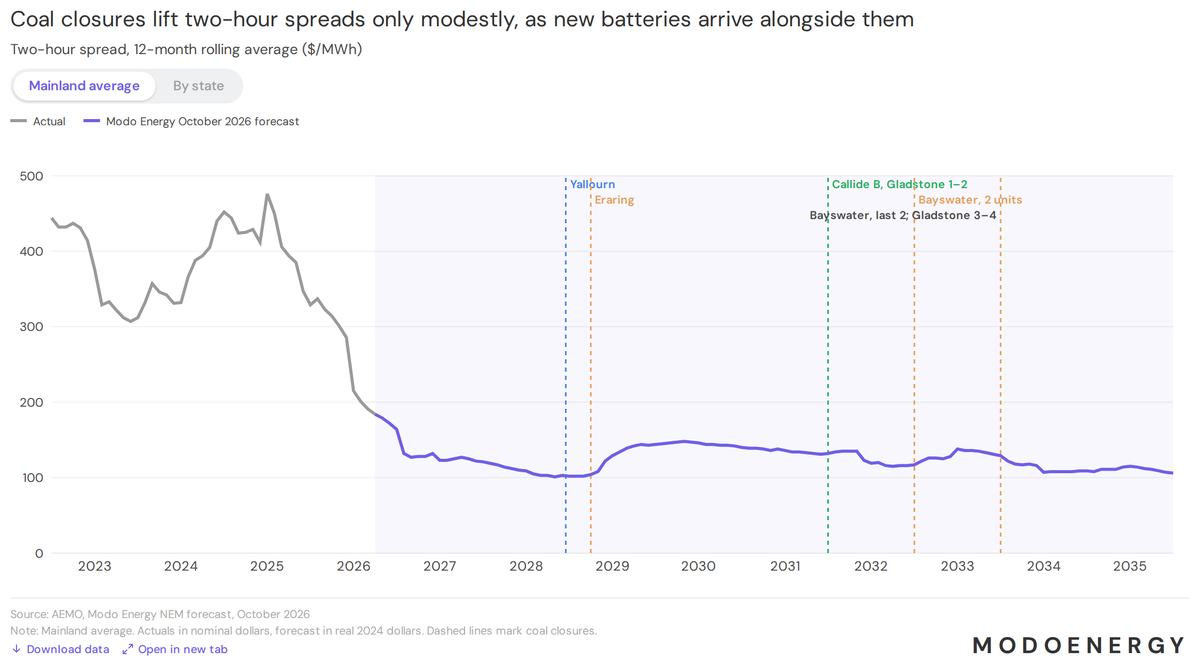
NEM: two-hour spreads in the year to September 2026 fell to about a third of the prior year in NSW and Queensland, and halved in Victoria. The fleet did its job, soaking up midday solar and softening the evening peak. Each new battery now needs a different investment case.
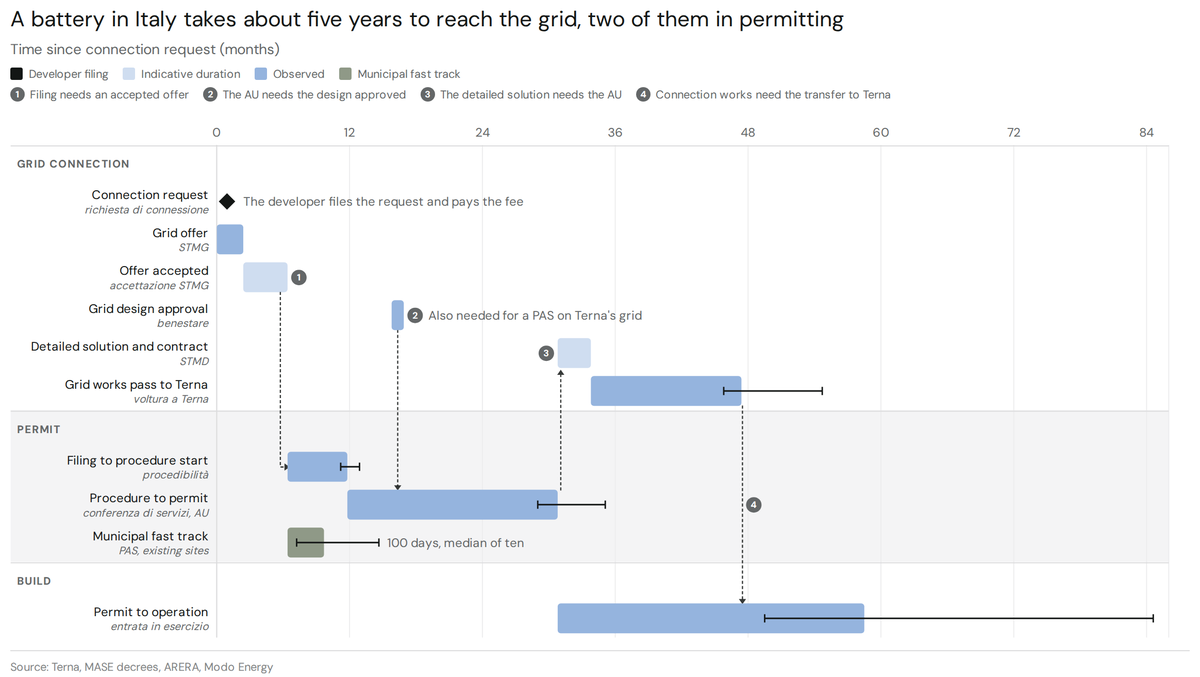
Italy: a standalone battery takes about five years from first grid request to operation. The bottleneck is permitting at MASE, where median review time rose from 12 months in 2024 to 19 months in 2026 as requests piled up. Terna issues its grid offer in about two.
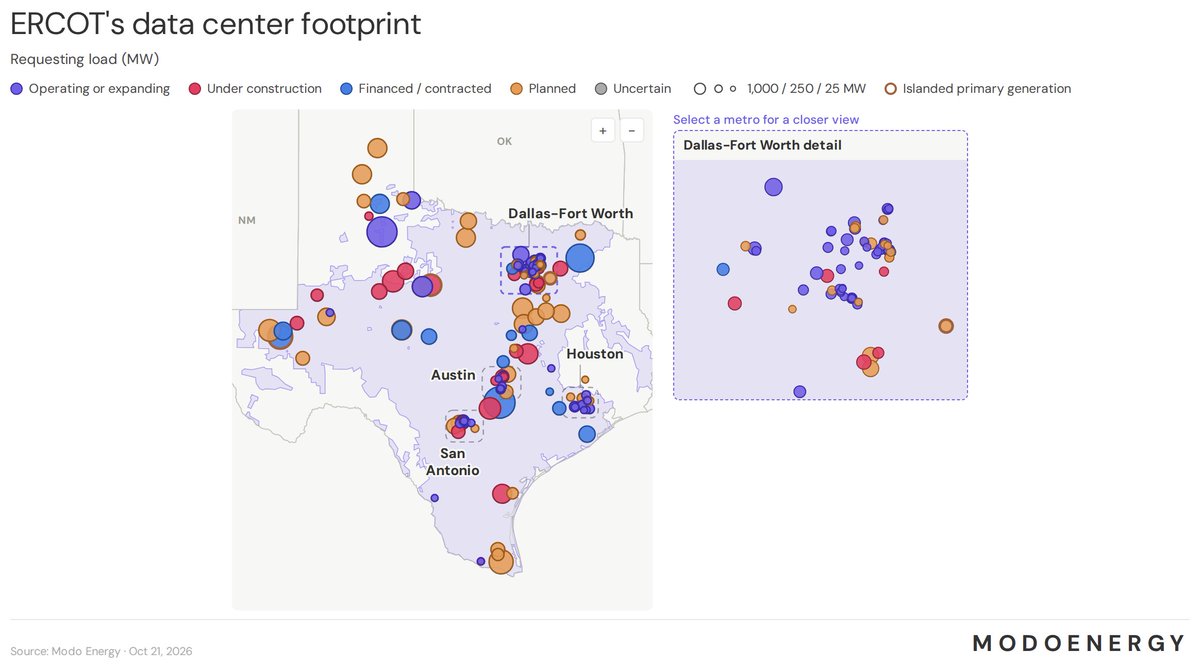
ERCOT: Modo tracks 92 GW of data center load in advanced planning as of October 21, spanning Dallas-Fort Worth into West Texas and the I-35 corridor. But these projects are heavily phased, so the timing and volume hitting the grid depends on how customer ramps actually land.
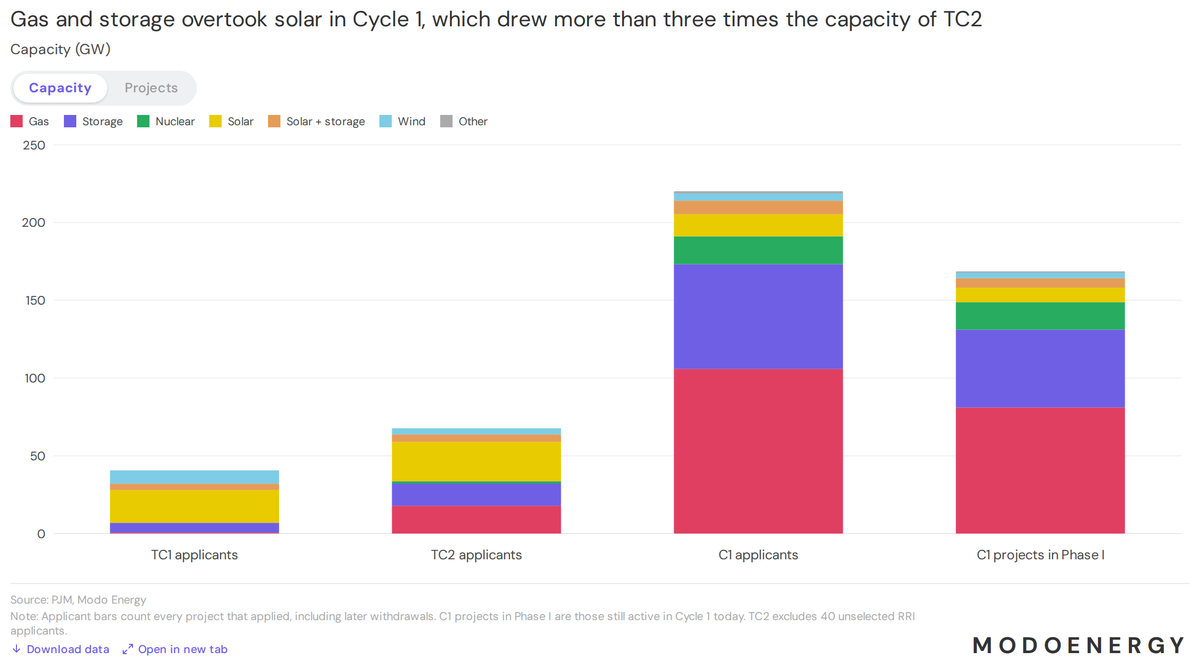
PJM: solar made up 37% of applied capacity in the last transition cycle. In Cycle 1 that share fell to 6%. Gas applications grew nearly sixfold, storage nearly fivefold. With capacity prices at the cap three auctions running, higher ELCC ratings now drive what developers build.
Until recently, Germany’s transmission grid got a handful of connection requests a year. But big power stations are slow to build. Batteries aren’t.
Over the last two years, 50Hertz alone has seen 100+ applicants, most of them batteries.
→ 30+ GW of new connection capacity offered
→ 14 GW of batteries with grid reservations, projects starting 2029 or earlier
→ A starting point of less than 1 GW
On top of that, 50Hertz received around 180 more battery applications this year, totalling 80+ GW. Germany’s peak demand is about 80 GW.
How much of it will actually get built? Wilhelm says it’s the question that keeps 50Hertz awake at night.
Wilhelm Kiewitt, Head of Energy Economics at @50Hertzcom, on Transmission with @Edcporter.
#BESS #EnergyStorage #Germany #Energiewende #GridConnection