| Engineer | Masters in Supply Chain | Ex Tech Consulting Director | Supporting big corporations with their IT transformation | Active Investor since 2024
Server CPU revenue is up sharply across the sector — AMD +107%, Intel +59%, Broadcom's AI silicon +221%. But Intel's own filings show volume grew just 9% while price did the rest. That's a supply story, not yet a demand story.
Ranked cheapest to most expensive on forward earnings: $MU, then $NVDA / $DELL / $AVGO in a tight band, then $AMD and $INTC. The two purest CPU plays are also the two most expensive.
Full valuation scorecard, bull/base/bear cases, and a probability read on "parabolic" below.
https://t.co/FhLttGoNUV
Linda points out a smooth, steady uptrend on the 2-min S&P futures chart where a tight ATR trailing stop stays intact, calling it an efficient markup. This linear price action usually means large institutions are slowly feeding big buy orders into the market via algorithms so they do not move prices too sharply. The takeaway is that a substantial amount of capital is currently being put to work.
$META
Might run a bit more. In the short term - it may be better to trim if this goes closer to $790.
As much as I see the catalyst when it comes to MUSE. It will have its own bumps in the road in the near future.
Be careful. Use today and the next few days to manage your risk and re-arrange your cash situation.
Green days - trim as necessary and no buys!
Red days - Use the cash wisely.
The graph tracks weekly global onshore oil storage (in millions of barrels) from 2017 to now.
The red 2026 line has plunged lately to the lowest levels in years (near 3,330).
This drop happened even after the market already absorbed ~340 million barrels from strategic reserves plus ~140 million from floating storage near the Strait of Hormuz.
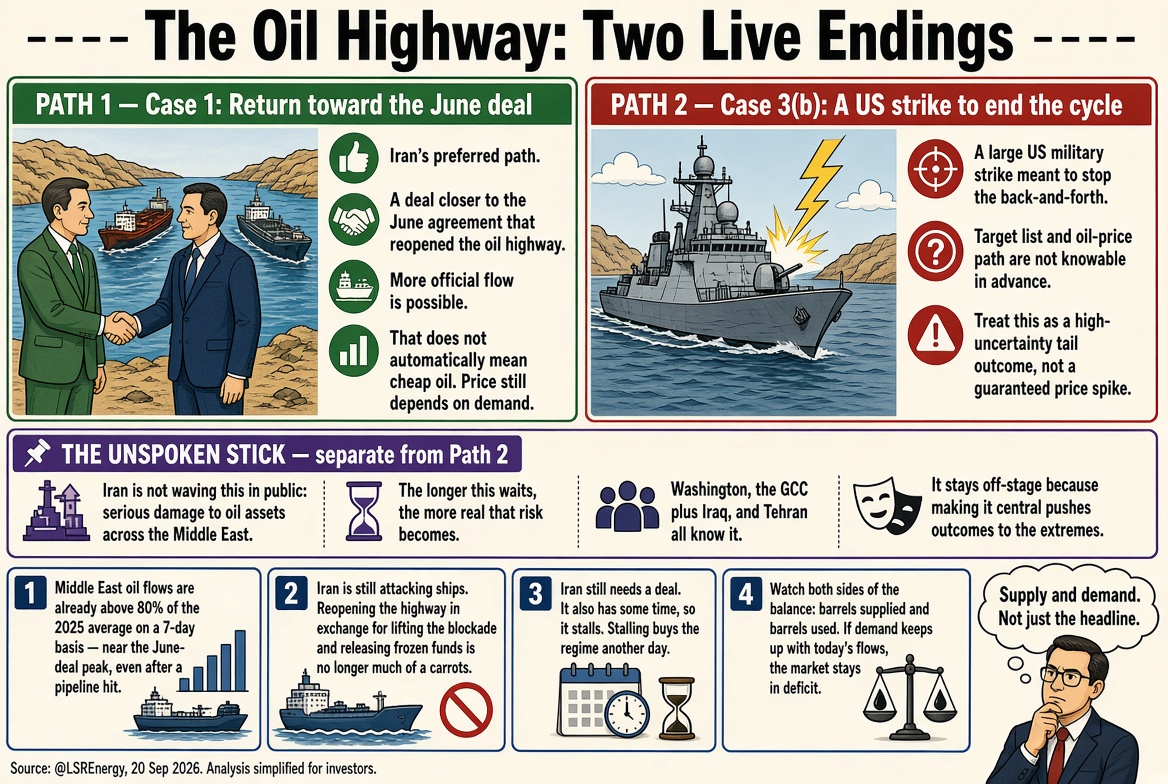
That’s the surprise: inventories are draining fast amid Middle East supply disruptions.
@HeidingOut I already had a decent position. Now that it went past $610. Hoping you get sometime soon to update price targets. I was hoping to trim some this month.
Looks like markets are going to give that small window. Not sure how long it will remain open. It’s still a risky tape which means find the right times to trim. I’m sure by now you should know which ones you need to trim in your ports. Only exception being long term stock holders
@CKCapitalxx Red - I’m hoping for one more green day to trim some of my short term swing positions. But I think we are reaching a stage where the end of September and October might be very painful.
I’d like to get some more cash on the sides.
#SPY#QQQ
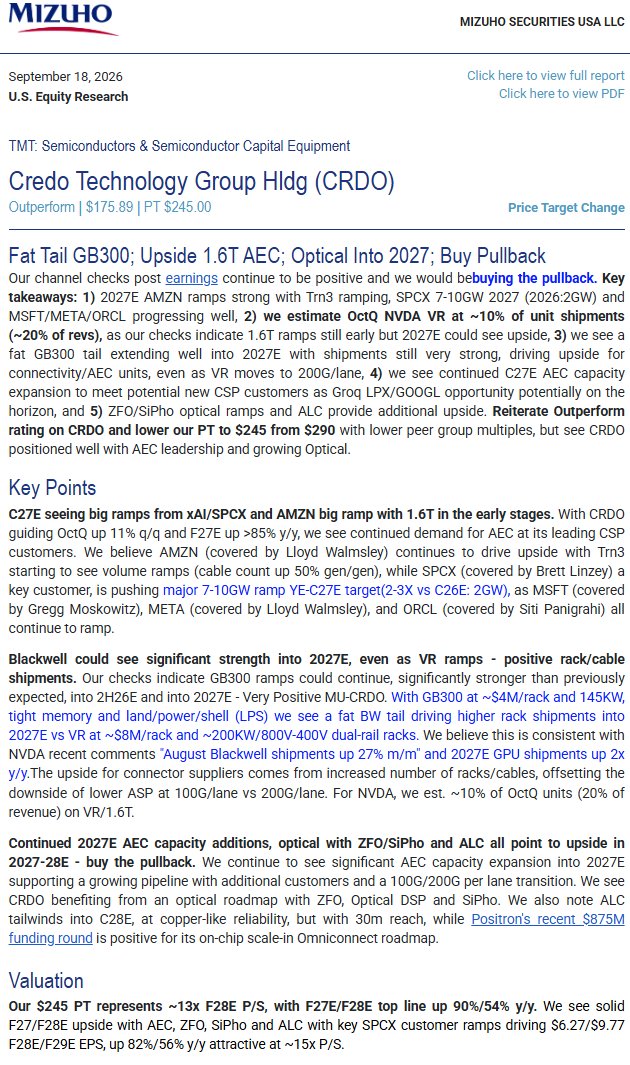
Mizuho on $CRDO: "very positive $MU / CRDO":
"Our checks indicate GB300 ramps could continue, significantly stronger than previously expected, into 2H26E and into 2027E - Very Positive MU-CRDO. With GB300 at ~$4M/rack and 145KW, tight memory and land/power/shell (LPS) we see a fat BW tail driving higher rack shipments into 2027E vs VR at ~$8M/rack and ~200KW/800V-400V dual-rail racks. We believe this is consistent with $NVDA recent comments "August Blackwell shipments up 27% m/m" and 2027E GPU shipments up 2x y/y.The upside for connector suppliers comes from increased number of racks/cables, offsetting the downside of lower ASP at 100G/lane vs 200G/lane. For NVDA, we est. ~10% of OctQ units (20% of revenue) on VR/1.6T."
$NUAI has entered into a 20-year PPA with a Vistra affiliate for up to 207 MW of firm, contracted power for Phase 1 of Texas Critical Data Center (TCDC).
The agreement provides New Era with power expected to be available in Q3 2027 from Vistra’s adjacent 1,180 MW Odessa generation facility.
New Era and Vistra have also entered into a development framework agreement that establishes a pathway for advancing future power development at TCDC and other New Era projects.
https://t.co/o51OJ91kwO
Samsung, SK Hynix, Micron and SanDisk are best placed given their leading NAND/eSSD shares and AI hyperscaler exposure (Samsung #1, SK Hynix/Solidigm #2, Micron rising fast, SanDisk pure-play QLC). Phison benefits as a controller supplier but less directly.
Best value right now is SK Hynix: lowest forward P/E (~4.5x) among them despite HBM leadership plus strong NAND/eSSD growth, with analyst targets implying solid upside. Micron is close behind on balanced exposure and accessibility.
Jev + Astra beats the Ender Dragon in Minecraft in 8 minutes 43 seconds! ⏱️
Cost less than $1 ($0.01 Jev, $0.96 Astra)
I open sourced the code and explain the harness setup below. This type of movement is only possible with Jev's near instant decisionmaking, and some continually learning skills from Astra.
#3 is the part people are treating as a volume call. The filings don’t.
Intel’s Q2: DCAI +59%, server units +9%, ASP +48%. Agent VMs can be CPU-bound and still show up as mix and price first.
$MU is the cheap way to own the DIMM side of the same stack. $AMD and $INTC are already the two most expensive names on forward earnings.
https://t.co/2nNaS9iBpS
Yes — GPU counts were the last cycle’s scoreboard. The ratio is the next one.
Just don’t read a rising CPU:GPU mix as a shipment boom. Intel’s Q2 was +59% DCAI revenue on +9% server volume. Price and mix did the work.
Walked through that split and the valuation stack here: https://t.co/2nNaS9j9fq