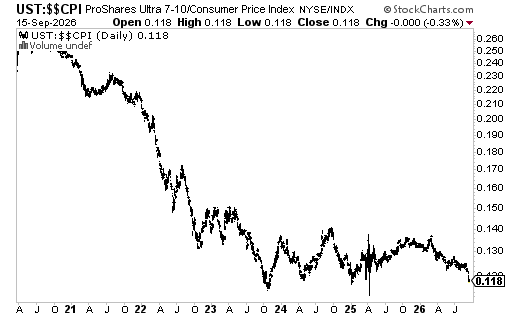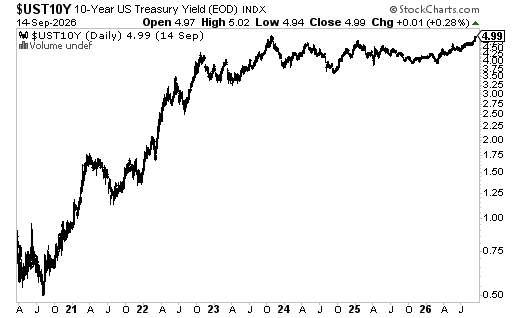@IFB_podcast These ratios are what others believe about a co's outlook. Also include a DCF, which reflect what you believe about prices, unit sales, gross profit margin, SG&A, R&D, taxes, capex, investment in WC, and WACC. That's valuation. Then as you learn new info, you update.
Time stamp this for 2036: $BRK.A $BRK.B has $325B of UST’s. Meanwhile, there's just $80B of bitcoin:native left to mine at today’s price. In theory, new CEO Greg Able can buy the last 920,000 coins and still have $245B of (chronic spendthrift) U.S. debt. He should.
@CaffeSatoshi Good visual. Perhaps use the left y-axis to show block rewards and add a right y- to show cum. supply. Then the supply increases at just 0.04% CAGR for the next 114 years is even more dramatic. The point: bitcoin:native 's supply doesn't respond to its price.
@MebFaber@MIT Meb - MIT pranksters once put a car on top of that dome. Another time they did this https://t.co/H72c4H42GG. Disclosure: My late father-in-law taught there.
@Theron_Mohamed Munger's all-time most helpful comment of many is: "We look for a horse with one chance in two of winning and which pays you three to one.” That's his stock hurdle rate: an expected value multiple of ≥ 3x.
@IIICapital Esp. for fixed income assets like UST's, this is a nominal estimate. The real return will be less unless our economy flips to deflation from its current inflation.
@zzeker@porterstansb@Porter_and_Co Mark - Don't know about divs and leadership. But I think I know Mr. B's personality well enough to say he's generously told Greg, "Do what you need to do. Conditions change and BRK must, as well. It's your canvas now."
If Greg Abel, Howie Buffett, and Susan Decker want to make $BRK.A $BRK.B great again (like the kinds of co's Warren and Charlie sought), they should pay @porterstansb@Porter_and_Co some A shares to explain at the next directors' meeting when and how the sprawling Omaha conglomerate diworsified. If you own Berkshire, reading "Warren's Mistakes" is a must. @herbgreenberg@DougKass
Since 2011, $BRK's return on capital has averaged a ho-hum ~10%/year, https://t.co/7VoUPMKIaY. Now that Abel is in charge, he should distribute 1) 80% of the $380 billion in cash and equivalents, 2) $300 billion of marketable securities, and 3) insurance and its $177 billion float. Then laser focus on the railroad, energy, and Precision Castparts. A smaller, leaner, more nimble BRK is a better BRK.
The smart money sold their 10-year paper because the semi-annual interest rate (coupon) lags inflation. "Reward-free risk," as Grant's Interest Rate Observe's James Grant has described.
Only a little more than six years ago the fixed income market was willing to pay 200 times earnings (annualized interest) for the 10-year UST. Now, the P/E is 20 times the coupon (1 / 0.05), which works out to a rerating of minus 90 percent. Brutal.