Amazon is building two new robotics factories to ramp up production of Proteus.
My estimate is that these two new factories alone could target annual production of around 60K Proteus robots, potentially generating $200M+ in annual revenue for $OUST.
Including Amazon’s existing robotics manufacturing facilities, its total annual Proteus production could be significantly higher, potentially helping explain why Ouster already expanded the capacity to manufacture over 100K Rev8 LiDAR sensors per year, with room to scale further. $OUST
https://t.co/hgxJe77C5J
$OUST
Very bullish on Ouster supplying lidar for Amazon's robotics ambitions.
Amazon's Proteus robot is already equipped with Ouster lidar, offering a glimpse of how big that opportunity could become.
$OUST is my picks-and-shovels way to own Physical AI, selling 3D perception into warehouses, logistics and autonomous systems without needing to guess whether $TSLA, $CCXI, Figure or any other robot maker wins.
Safe perception is what lets robots scale reliably and Ouster wins as that happens regardless of which manufacturer leads the market.
You can already see that starting to happen with Q2 revenue up 56% to ~$55M across 17,000+ lidar and camera sensors at ~$3,200 per unit on average while Stereolabs broadens stack beyond lidar alone.
@ousterlidar should post a video of grey kittens captured by Rev8 color LiDAR at 11 PM, so @elonmusk can see what a native color LiDAR can do today. $OUST $TSLA
Thanks to Eric112 for the idea.
$OUST Angus Pacala’s recent “After Earnings” interview provides a useful foundation for examining Ouster’s path to profitability.
On the timing, Angus said:
“2027 looks like the year we cross into profitability for the first time.”
On REV8’s commercial contribution:
“We're already seeing an impact from the revenue of REV8.”
And on the spending discipline supporting that transition:
“Maintaining OpEx growth at around 7% year-over-year.”
Together, these comments connect product adoption with operating leverage: management’s framework targets 30–50% annual revenue growth, 35–40% gross margins, and expenses growing much more slowly than revenue.
The analysis below works backward from a modest milestone: $0.01 of earnings per share in 2028, with stock compensation and depreciation fully expensed. Under the stated cash, interest, and tax assumptions, approximately $452.5M revenue at a 40% gross margin reaches that target.
That requires 43.9% annual growth over two model years from today’s annualized revenue baseline. Applying today’s revenue multiple and including the disclosed unvested RSUs produces an illustrative $86.21 share price, without multiple expansion.
A plausible scenario grounded in management’s framework—not company guidance or a guaranteed outcome.
People hate AI slop, adobe creative cloud won’t get disrupted by image generating AI lol
As someone who has a marketing agency:
$ADBE is a steal Right now
Corporate won’t swap Adobe for Canva, midjourney or any other BS.
I wonder which Fortune 500 companies @ousterlidar CEO Angus Pacala was referring to. $OUST
Amazon has already purchased more than $100M of goods and services from Ouster since 2023. So you might think Angus was talking about some other Fortune 500 companies..
But the timing of the events below really catches my attention:
Ouster released the Rev8 sensor in May with functional safety, enabling robots to safely work alongside humans.
Amazon announced plans in June to expand in Europe and roll out the next-gen Proteus:
“The next generation of Proteus is designed to go much further. Rather than operating only in dock areas, the new system can work anywhere items need to be moved. This includes transporting containers as they arrive at a site, transferring them between workstations, and assisting employees across Amazon’s fulfillment centers and delivery sites.”
The demand for next-gen Proteus could be orders of magnitude larger than what Ouster has already supplied to Amazon, which has already generated $100M+ in revenue.
It would make perfect sense for Amazon to want Ouster to have a strong balance sheet and be financially strong enough to support the expansion of Proteus over the next 5–10 years.
Ouster is currently shipping roughly 40K lidars/year. Yet on June 15, Ouster and Benchmark announced established Rev8 production capacity exceeding 100K units/year, with the ability to rapidly expand capacity as demand grows — and a planned 10-year production life.
That means Ouster is already capable of producing 1M+ Rev8 LiDAR sensors over the next 10 years, even without further capacity expansion.
Then Ouster raised ~$192M just two weeks later, bringing pro forma cash to ~$450M.
We now know that the purpose of the raise was to strengthen the balance sheet for some “Fortune 500 companies placing a bet on Ouster as a strategic supplier or sole supplier.”
In August, Amazon announced a new robotics factory in Austin, Texas, to build “heavy lifting robots that can work alongside humans” — which we know is clearly Proteus. As I estimated, the factory should be capable of producing at least 30K Proteus robots per year, comparable to Amazon’s existing robotics factory in Massachusetts.
That alone could represent ~$100M/year for Ouster.
Then Amazon announced another robotics factory in Indiana in September.
Not that hard to connect the dots here.
$OUST
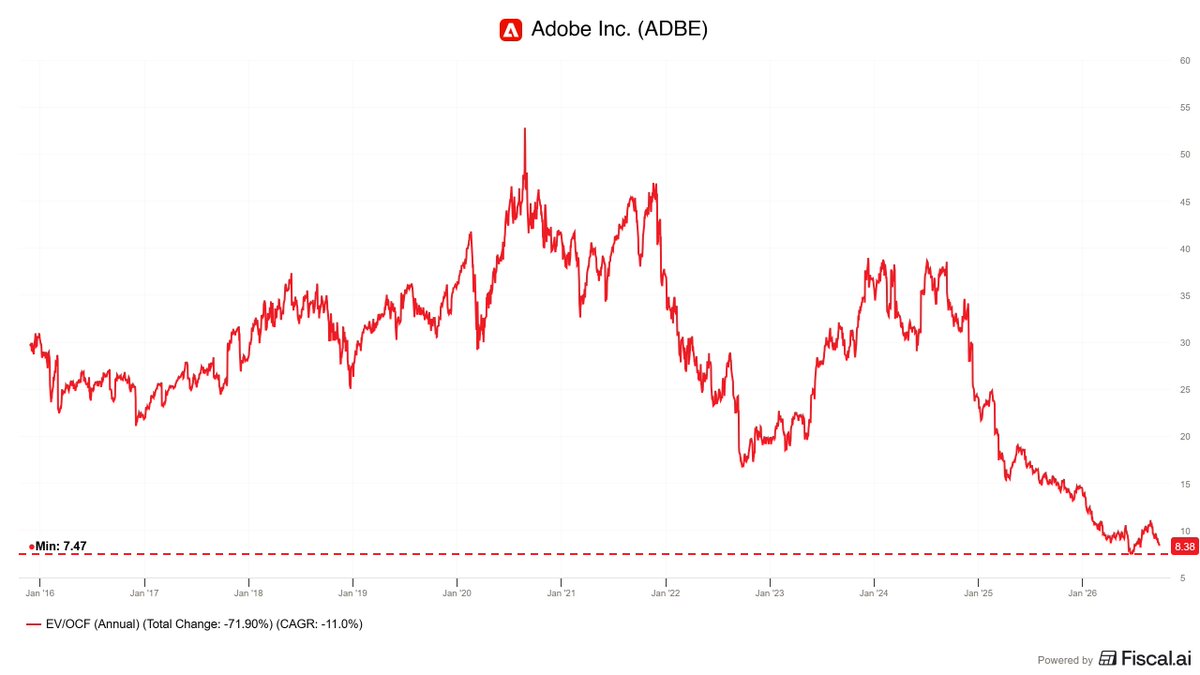
$ADBE is every deep value investor's wet dream right now.
The most hated, neglected, and spit-on business out there.
Heavily discounted on its tangible assets... again, the wet dream of any deep value investor.
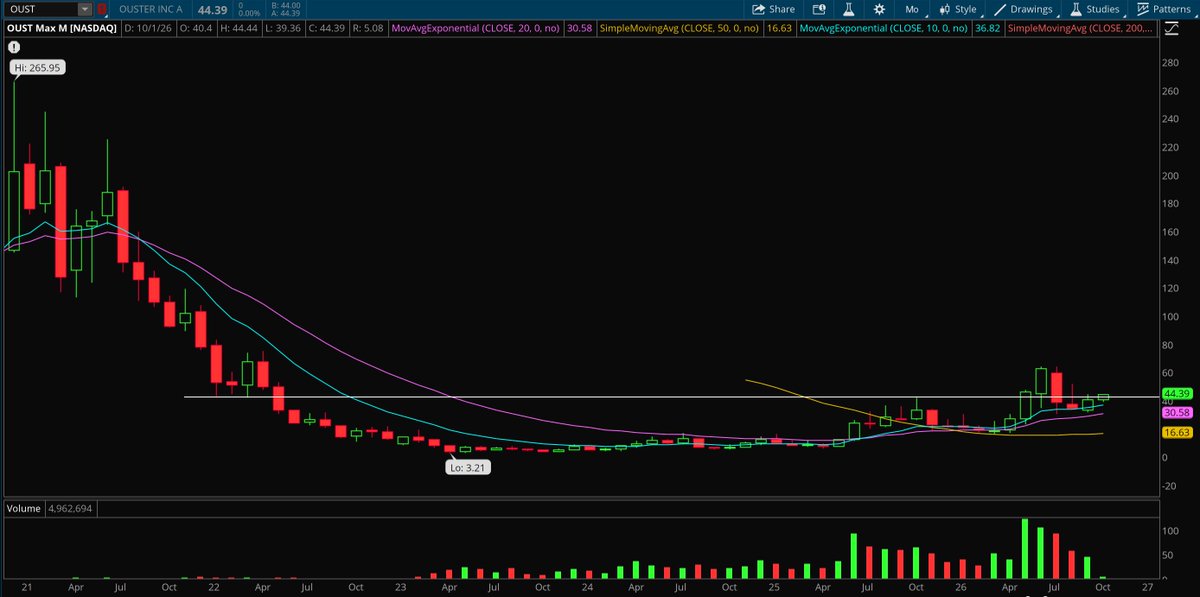
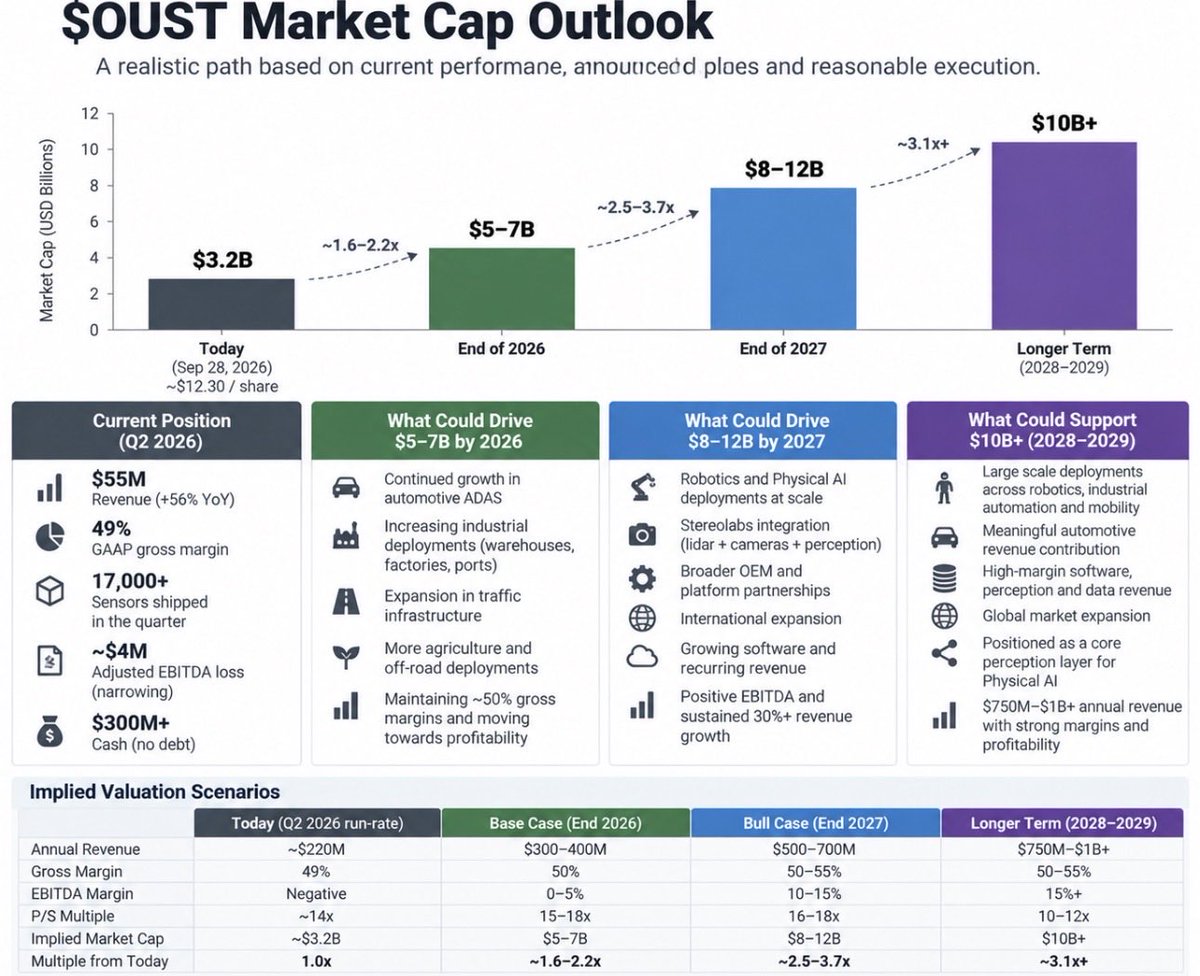
I think $OUST can realistically become a $ 10B+ company
That’s roughly 3x today’s ~$3.2B market cap.
But at this valuation, “Physical AI will be huge” isn’t enough.
The numbers actually have to work.
Right now Ouster is doing ~$55M of quarterly revenue.
That’s +56% YoY.
Gross margin is already 49%.
And adjusted EBITDA loss is down to just ~$4M.
So here’s roughly what I need to see:
2026 -> ~$3-4B
Keep revenue growing 30%+.
Maintain ~50% gross margins.
Get to / very close to positive adjusted EBITDA.
2027-28 -> ~$5-7B
This is where the Physical AI thesis needs to start showing up in volume.
Not just pilots.
Thousands more sensors going into warehouses, traffic systems, agriculture, drones + robots.
And Stereolabs needs to prove the acquisition gave Ouster something bigger than lidar:
Lidar + cameras + perception.
Then ~$10B+ becomes interesting.
To justify that, I’d want Ouster approaching roughly $ 750M-$1B annual revenue with strong growth and actual profitability.
At $1B revenue, a $10B valuation is 10x sales.
Expensive.
But not insane if Ouster has become one of the core perception layers underneath Physical AI with ~50%+ gross margins and 30%+ growth.
That’s really my thesis here.
I’m not betting that lidar suddenly becomes incredibly valuable.
I’m betting that millions of machines are eventually going to need to understand the physical world around them.
Cars.
Robots.
Drones.
Factories.
Warehouses.
Cities.
Farms.
And somebody has to give those machines eyes.
If Ouster becomes one of those companies, I don’t think $3B is where this story ends.