$ABCL, 거대한 TCE 경쟁의 최전선에 서다
시작은 2014년, 암젠의 혈액암 TCE 치료제 최초 승인이었다.
그리고 10년 뒤인 2024년, 암젠은 고형암에서도 항체 기반 TCE의 가능성을 입증했다. 이를 기점으로 글로벌 제약사들의 기술 확보 경쟁은 더욱 뜨거워졌고, 대형 계약들이 잇따르고 있다.
TCE가 신약 개발의 대세까지는 아닐지 몰라도, 매우 중요한 축으로 급성장하고 있다는 것은 분명해 보인다.
첨부한 그래프는 2020년부터 2026년 10월까지 공개적으로 확인한 주요 TCE 기술이전·라이선스·공동개발 계약의 건수(건)와 최대 계약금액 합계(억 달러)를 나타낸 것이다. 전체 계약을 망라한 통계는 아니지만, 최근 대형 계약이 얼마나 활발해졌는지 보여준다.
앱셀레라는 이미 2021년 말부터 TCE 개발을 준비해 왔다. 그리고 2026년, 그동안 축적한 기술이 구체적인 사업 성과로 이어지기 시작했다.
① 재즈 — 고형암용 차세대 다중특이성 TCE 공동개발
② 버텍스 — 자가면역질환 TCE 개발 계약
③ ABCL386 — 아직 기전이 공개되지 않았지만, 자체 TCE 후보물질일 가능성도 있는 항암 파이프라인
거대한 파도가 밀려오는 시장에 앱셀레라도 숟가락 하나를 얹어놓은 셈이다.
그리고 앱셀레라의 항체 발굴·설계 기술력이 어떤 수준인지는 여러분도 잘 알고 있을 것이다.
문득 이런 생각이 든다.
어쩌면 앱셀레라는 ABCL635보다 훨씬 더 거대한 웨이브에 올라탄 것인지도 모른다.
물론 그 기술력이 실제 임상 성과로 이어진다는 전제하에.
성공한다면, 이야기는 완전히 달라질 것이다.
Visit our poster at The Menopause Society 2026 Annual Meeting. We will be presenting Phase 1/2 results on ABCL635, an investigational, potential best-in-class antibody drug for the non-hormonal treatment of vasomotor symptoms.
Read more about ABCL635 here:
https://t.co/HY9u8ygahS
$LPTH
Germanium 대체를 넘어
이제는 방산 IR 시스템 전체를 말하고 있다
LightPath가 AUSA에서 다시 메시지를 분명히 했습니다.
“Germanium availability shouldn’t dictate your defense program’s schedule.”
핵심은 단순히
“BlackDiamond가 Germanium을 대체한다”
가 아닙니다.
이번 공식 게시물에서 회사가 직접 말한 범위는
Fixed lenses
→ Continuous zoom optics
→ Integrated thermal camera systems
까지입니다.
즉, BlackDiamond를 소재 하나로 파는 것이 아니라,
광학 성능
확장 가능한 생산
공급망 안정성
까지 포함해 방산 integrator의 IR 시스템 전체를 다시 설계하려는 방향입니다.
어제 @OptimusDelta의 자료에서도 봤듯이,
LightPath가 가려는 곳은 결국
Glass
→ Optics
→ Camera
→ Subsystem
→ Seeker
입니다.
그래서 이제 LPTH를 단순한
“Germanium 대체회사”
라고만 보는 것은 점점 맞지 않는 것 같습니다.
제가 이번 AUSA에서 보고 싶은 것도 같습니다.
BlackDiamond가 몇 개 제품에 들어갔는가보다,
그 소재를 출발점으로 실제 방산 플랫폼에서
Camera·Subsystem·Seeker까지 얼마나 깊게 들어가고
있는가.?
회사 전략은 점점 선명해지고 있습니다.
이제 필요한 것은
Named Customer와 Production Order입니다.
🔗 참고자료 / PRIMARY SOURCES
LightPath Technologies — AUSA 2026 BlackDiamond 공식 게시물
https://t.co/jExrA9WcOu
OptimusDelta — From Glass to Seeker: NGSRI and LightPath
https://t.co/lEtTxQXpe7
$LPTH
AUSA 2026 중간점검
제품은 준비됐다 이제 고객과 생산을 확인할 차례다.✔️
AUSA 2026이 시작됐습니다.
지금까지 LightPath가 공식적으로 보여준 내용을 다시 정리해보면, 이번 행사의 방향은 꽤 분명합니다.
단순히 BlackDiamond라는 소재 하나를 홍보하는 자리가
아닙니다.
LightPath가 이번 AUSA에서 들고 나온 것은 크게 네 축입니다.
• Redesigned G5 / Kestrel cooled MWIR
• BlackDiamond 기반 LWIR zoom
• Compact LWIR seeker
• CST Omni passive C-UAS sensing
그리고 회사가 반복해서 사용하는 단어도 눈에 들어옵니다.
Integration
MOSA
Production
Scalable production
Production timelines
제가 보기에는 이번 AUSA의 핵심은
Glass → Optics → Camera → Subsystem → Seeker
라는 LightPath의 방향을 방산 고객과 integrator에게 실제로 보여주는 자리입니다.
1. Kestrel COMPACT185
새로운 compact cooled MWIR camera입니다.
단순히 기존 G5를 작게 만든 것이 아니라
detector
optics
controls
processing
을 하나의 system으로 다시 최적화했습니다.
Target은 gimbal, airborne payload, autonomous
system입니다.
즉, G5가 실제 플랫폼 안으로 들어가기 위한 architecture redesign에 가깝습니다.
2. BlackDiamond LWIR Zoom
여기서는 한 단계 더 구체적인 표현이 나왔습니다.
15–75mm F/1.2 LWIR zoom은 회사 표현상
“moving into production”
단계입니다.
반면 11–55mm F/1.2 SWaP optimized zoom은 아직 개발단계입니다.
이 구분은 중요합니다.
AUSA에서 보여주는 모든 것이 미래기술은 아니고, 일부는
실제 생산단계로 넘어가고 있습니다.
3. Compact LWIR Seeker
최근 우리가 깊게 봤던 부분입니다.
LightPath는 단순 camera core를 끼워 넣는 것이 아니라
core + electronics + BlackDiamond optics
를 플랫폼 요구조건에 맞춰 설계한다고 설명하고 있습니다.
최근 low-cost seeker white paper와도 방향이 같습니다.
결국 회사가 목표로 하는 것은 렌즈 공급이 아니라
guidance-ready imaging subsystem
쪽으로 보입니다.
CST Omni
C-UAS에서도 메시지는 비슷합니다.
CST Omni는 여러 640×480 IR sensor와 BlackDiamond
lens를 사용하고,
RF를 방출하지 않는 passive detection,
shutterless continuous imaging,
MOSA integration을 강조하고 있습니다.
LightPath가 완성 C-UAS prime이 되겠다는 것보다
더 큰 방산 시스템 안으로 들어가는 sensing layer
를 노리는 전략으로 보입니다.
그런데 중요한 것은 여기부터입니다.
현재까지 제가 확인한 AUSA 관련 공식자료에서는 아직
새로운 Named Customer
새로운 Production Order
새로운 Program Award
두 번째 Named Seeker Customer
7개 Missile Platform의 새로운 이름
G5/Kestrel의 실제 Design-in 고객
은 나오지 않았습니다.
그래서 현재 AUSA 중간평가는 이렇게 하고 싶습니다.
기술과 제품은 더 선명해졌다.
하지만 시장이 기다리는 Commercial Proof는 아직 나오지 않았다.
최근 LPTH 주가를 보면서 더욱 느끼는 부분입니다.
이제 시장은
“기술이 좋다”
보다
누가 사는가
몇 대인가
언제 생산되는가
를 요구하고 있습니다.
그래서 남은 AUSA 기간에는 제품 설명보다 다음 네 가지를
더 중요하게 보겠습니다.
1. Named Customer / Integrator
2. Production-ready / Qualification / LRIP
3. NGSRI 외 새로운 Seeker Program
4. Kestrel / G5의 실제 Platform Design-in
LightPath가 AUSA에서 보여주려는 방향은 상당히 분명해졌습니다.
이제 필요한 것은
Strategy → Contract
Design-in → Production
으로 넘어가는 증거입니다.
이번 AUSA에서는 바로 그 한 단계가 나오는지를 끝까지 지켜보겠습니다.
🔗 참고자료 / PRIMARY SOURCES
LightPath Technologies — AUSA 2026 공식 LinkedIn
https://t.co/T4P4WnrnGc
LightPath Technologies — CST Omni for C-UAS Defense at AUSA 2026
https://t.co/6MQX8Q37PB
$RDW 레드와이어, ROSA 발사 준비 완료.
Redwire는 오늘 국제 우주 정거장에 배치될 국제 우주 정거장을 위한 롤아웃 솔라 어레이 (ROSA) 날개의 네 번째이자 마지막 쌍이 NASA의 SpaceX 35번째 화물 보급 서비스 임무(SpaceX CRS-35) 탑재체로 우주 정거장으로 발사될 것이라고 발표함.
레드와이어의 태양광 사업은 순조로운 상황.
$RKLB
If you think it's tough holding Rocket Lab now, imagine holding it in 2023 when:
• Electron mission failed
• Peter Beck sold 3.6M shares
• The stock was trading around $4
Makes today's worries feel pretty small. A bit of perspective goes a long way.
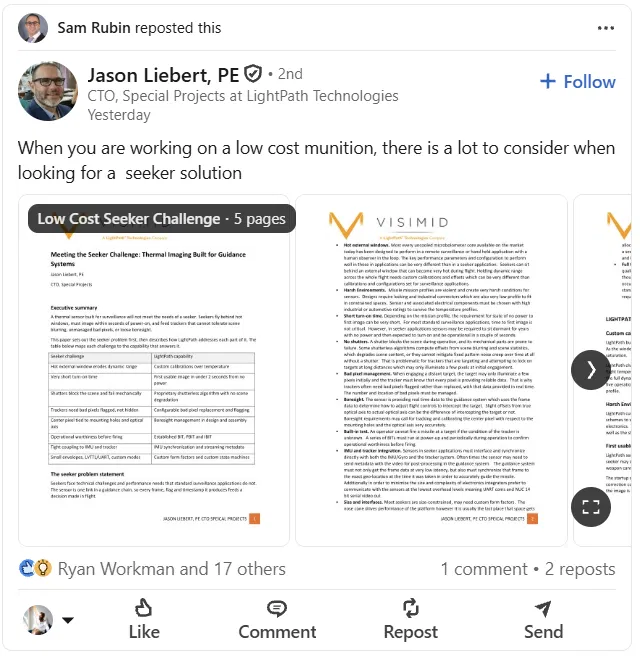
$LPTH's CTO of Special Projects has just put out a white paper on low cost seekers, and @skrubin reposted it, so this is the company putting its name to it.
The interesting part is what they're selling.
It's not glass or a lens, it's the whole seeker sensor module, with calibration for a window that heats up in flight, a usable image in under two seconds from cold, shutterless correction, bad pixel flagging for the tracker, built in test and IMU sync.
That's the camera that actually guides the missile.
It's also uncooled, which is the cheap and high volume end of seekers, and that's exactly where the Army is now heading with low cost interceptors and buying seekers as standalone components rather than through a prime.
The paper is pretty direct about who it's competing with too, as it calls out off the shelf thermal cores that were built for surveillance and asks whether those suppliers will ever modify anything for your system.
My read is @lightpathtech is moving up the munitions chain from optics supplier to seeker supplier, which is a much bigger slice of each round. With the redesigned G5 being unveiled at AUSA the same week, it looks like they're heading to the Army show with long range cameras for towers and seeker modules for munitions.
Long $LPTH 🫦
https://t.co/FbxAQjCypS
$LPTH 드디어 17,600주가 됐습니다.
지금은 제 투자 과정에서 가장 답답한? 구간 중 하나인 것 같습니다.
주변 환경은 분명 좋아지고 있습니다.
C-UAS, MWIR, 방산 EO/IR, BlackDiamond, AUSA, 정부 생산지원 가능성까지
LPTH가 들어갈 수 있는 시장과 정책 방향은 계속 좋아지고
있습니다.
그런데 정작 회사에서 우리가 가장 보고 싶은
고객명
계약금액
생산수량
신규 수주
매출 전환
은 아직 충분히 보이지 않습니다.
그래서 지금은 마치 긴 어둠의 터널을 지나가는 느낌입니다.
스토리는 점점 좋아지는데, 숫자가 아직 따라오지 않는 구간.
그래도 저는 이 회사를 가장 기대하는 종목 중 하나로 보고
있습니다.
이제 필요한 건 더 많은 추정이 아니라
“이 기술과 시장이 실제 계약과 매출로 바뀌고 있다”는
증거라고 생각합니다.
그 한두 개의 확정된 숫자가 나오기 시작하면
지금 우리가 지나고 있는 이 구간의 의미도 훨씬 선명해질 것 같습니다.
🔗 참고자료 / PRIMARY SOURCES
LightPath Technologies — FY2026 Form 10-K
https://t.co/CB4S1k4wIb
LightPath Technologies — Official LinkedIn
https://t.co/T4P4WnrnGc
$ABCL new ABCL hiring development
AbCellera’s careers board just jumped to 31 openings, with a fresh cluster of GMP Quality + Manufacturing hires appearing today:
• Senior Manager, QC Microbiology — $135K–$170K + equity/bonus
• QC Analyst II
• Senior QC Data Reviewer
• External QA Specialist/Manager
• QA Specialist — Supplier Quality
And these aren’t discovery-science jobs.
They’re hiring for GMP clinical manufacturing, drug substance + drug product, release/stability testing, contamination control, CMO oversight, manufacturing readiness and CMC support.
Add that to the recent hiring for:
VP Late-Stage & Commercial Biologics Development
VP Medical Affairs
VP Biometrics
Drug Safety/Pharmacovigilance
CMC Regulatory Affairs
Director, Drug Product MSAT
Combination Products/Device Development
Look at the pattern.
Discovery → Clinical Development → Manufacturing → Regulatory → Medical Affairs → Commercialization
$ABCL isn’t just talking about becoming a fully integrated biotech anymore. They’re hiring the infrastructure to actually become one.
All while ABCL635 advances, 12-week data are still coming, and 688/386 move toward the clinic.
One job posting is noise.
This many coordinated hires across the entire development stack is a signal. 👀🔥
Bullish. 🧬📈
🔭 $LPTH
10월 1일 공식자료 — AUSA에서 Redesigned G5 공개.
핵심 판단:
이번 G5는 단순한 Germanium→BlackDiamond 렌즈 교체가 아니라, 장거리·자율체계 경험을 반영해 architecture와 optics를 함께 다시 설계한 차세대 MWIR 플랫폼으로 보는 게 맞아 보입니다.
10월 1일 LightPath는 AUSA 2026을 앞두고
Redesigned G5 MWIR platform을 공개하겠다고 공식
발표했습니다.
회사가 직접 사용한 표현은:
New architecture.
New optical approach.
BlackDiamond™ inside.
입니다.
또한 LightPath는 장거리 및 autonomous application용 MWIR 카메라를 개발하면서 배운 내용을 다시 G5 플랫폼에 적용했다고 설명했습니다.
✅ 확인된 사실
기존 Investor Day에서 G5 redesign의 목표는
• Germanium → BlackDiamond 전환
• 동일하거나 향상된 optical performance
• size / weight / interface 유지
였습니다.
이번 10월 1일 게시물에서는 여기에 더해
**“New architecture / New optical approach”**라는
표현까지 등장했습니다.
따라서 이번 AUSA에서 공개될 G5는 단순 소재 교체보다
한 단계 더 큰 platform redesign으로 보는 게 자연스럽습니다.
⠀
🔎 아직 확인이 필요한 부분
AUSA에서 반드시 봐야 할 것은
Production-ready인가?
Qualification은 어디까지 끝났는가?
정확한 SWaP은?
기존 고객이 신형 G5로 전환하고 있는가?
입니다.
제품 공개 자체보다
Production / Qualified / Customer transition / Delivery
라는 단어가 나오는지가 더 중요하다고 봅니다.
지금까지는
BlackDiamond
→ IR optics
→ G5 MWIR camera
로 기술통합이 진행됐다면,
이번 AUSA에서는
이 G5가 실제 방산·자율체계용 production platform으로 어디까지 올라왔는지를 확인하는 자리가 될 것 같습니다.
🔗 참고자료 / PRIMARY SOURCES
LightPath Technologies — Redesigned G5 MWIR / AUSA 2026 공식 게시물, 2026년 10월 1일
https://t.co/EGpwFD3igQ
LightPath Technologies — 2026 Investor Day Presentation
https://t.co/xEnjQeIwNH
LightPath Technologies — FY2026 Form 10-K
https://t.co/CB4S1k4wIb
$RDW
Redwire has completed roughly $149.6 million (about 30%) of its $500 million At-The-Market (ATM) program.
This leaves $350 million in capacity remaining.
Imagine a successful Q3 report + end of ATM.
We are here to retire baby
$LPTH — 𝗧𝗛𝗘 𝗗𝗢𝗧𝗦 𝗔𝗥𝗘 𝗚𝗘𝗧𝗧𝗜𝗡𝗚 𝗛𝗔𝗥𝗗𝗘𝗥 𝗧𝗢 𝗜𝗚𝗡𝗢𝗥𝗘
At some point you have to ask the question.
How many more dots have to connect before they stop being dots?
Look at what happened just this past week — then compare it to what LightPath has been telling investors.
𝗗𝗢𝗧 #𝟭: 𝗧𝗛𝗘 𝗔𝗥𝗠𝗬 𝗝𝗨𝗦𝗧 𝗣𝗨𝗧 𝗕𝗜𝗟𝗟𝗜𝗢𝗡𝗦 𝗕𝗘𝗛𝗜𝗡𝗗 𝗖𝗢𝗨𝗡𝗧𝗘𝗥-𝗨𝗔𝗦
On Sept. 29, JIATF-401 awarded a major series of counter-UAS IDIQ contracts supporting Domestic Shield and its C-UAS Marketplace. Ten companies received initial ceilings totaling approximately $4.15 billion, with the broader vehicle potentially reaching $7 billion.
The capabilities cover sensors, long-range tracking cameras, smart optical systems, radar, effectors and layered C-UAS defense.
LightPath specifically named JIATF-401 as a near-term C-UAS pipeline opportunity on its Investor Day.
To be clear: LightPath was not one of the 10 companies awarded this week.
But JIATF-401 is no longer theoretical. The procurement machinery is moving and the marketplace is explicitly designed to let new technologies be rapidly evaluated, integrated and procured.
𝗔𝗡𝗗 𝗧𝗛𝗜𝗦 𝗗𝗢𝗧 𝗝𝗨𝗦𝗧 𝗚𝗢𝗧 𝗦𝗧𝗥𝗢𝗡𝗚𝗘𝗥.
A new Pentagon directive released on Oct. 2 puts JIATF-401 at the center of coordinating counter-UAS employment while directing the Department to remove administrative and procedural barriers that have slowed deployment.
The objective is straightforward: move some counter-UAS approval timelines from months to days or weeks.
Again, that doesn’t mean a LightPath contract.
But it means the Pentagon isn’t simply putting billions behind counter-UAS procurement.
It’s simultaneously trying to accelerate how quickly these systems can actually be approved, deployed and fielded.
For a company already positioned across U.S.-made infrared optics, imaging systems and counter-UAS, that’s another meaningful piece of the same picture.
𝗗𝗢𝗧 #𝟮: 𝗧𝗛𝗘 𝗔𝗜𝗥 𝗙𝗢𝗥𝗖𝗘 𝗜𝗦 𝗟𝗢𝗢𝗞𝗜𝗡𝗚 𝗙𝗢𝗥 𝗟𝗪𝗜𝗥 𝗦𝗘𝗘𝗞𝗘𝗥𝗦
Around the same time, the Air Force posted a QuickSink Notice of Contract Action covering Long-Wave Infrared seekers, LWIR/RF configurations, test assets and flight-test support.
There is no evidence LightPath is involved with QuickSink.
What matters is the direction: infrared seekers are being actively developed, tested and procured right now — exactly the area LightPath has flagged as new seeker opportunities and expansion of existing missile programs.
𝗗𝗢𝗧 #𝟯: 𝗢𝗞𝗦𝗜 𝗨𝗡𝗩𝗘𝗜𝗟𝗦 𝗣𝗥𝗢𝗗𝗨𝗖𝗧𝗜𝗢𝗡-𝗥𝗘𝗔𝗗𝗬 𝗜𝗡𝗧𝗘𝗟𝗟𝗜𝗚𝗘𝗡𝗧 𝗦𝗘𝗘𝗞𝗘𝗥𝗦
On Oct. 1, OKSI announced a line of production-ready Intelligent Seekers for missile platforms and precision munitions. The systems feature passive EO/IR sensing, AI-enabled target recognition, autonomous acquisition and tracking, GPS-denied operation, lock-on-after-launch and applications across counter-UAS, maritime strike and land attack.
There is no evidence OKSI is a LightPath customer.
But the architecture — EO/IR, autonomy, seekers, counter-UAS, open architecture and supply-chain resilience — maps directly onto the markets LightPath has been building toward.
𝗗𝗢𝗧 #𝟰: 𝗧𝗛𝗘 𝗡𝗔𝗩𝗬 𝗜𝗦 𝗥𝗔𝗣𝗜𝗗𝗟𝗬 𝗘𝗩𝗔𝗟𝗨𝗔𝗧𝗜𝗡𝗚 𝗡𝗘𝗪 𝗘𝗢/𝗜𝗥 𝗧𝗘𝗖𝗛𝗡𝗢𝗟𝗢𝗚𝗬
In the week of Sept. 21, the Department of the Navy Rapid Capabilities Office held its first “Disruptor Day” focused on electro-optical/infrared systems, bringing industry directly together with operators and acquisition personnel to accelerate near-term deployment.
𝗗𝗢𝗧 #𝟱: 𝗔𝗠𝗘𝗥𝗜𝗖𝗔 𝗞𝗘𝗘𝗣𝗦 𝗕𝗨𝗜𝗟𝗗𝗜𝗡𝗚 𝗗𝗢𝗠𝗘𝗦𝗧𝗜𝗖 𝗢𝗣𝗧𝗜𝗖𝗔𝗟 𝗖𝗔𝗣𝗔𝗖𝗜𝗧𝗬
On Sept. 29, Attalon announced a nearly $13 million investment to expand U.S. sapphire manufacturing for advanced EO/IR and next-generation defense systems.
Different material, different company — same directional signal LightPath has been highlighting: demand for secure, domestic optical-material supply chains is rising.
Only weeks earlier, LightPath itself received a competitively awarded Department of War prototype agreement under the CLEAR program to advance BlackDiamond as a domestic alternative to germanium for defense EO/IR systems.
𝗡𝗢𝗪 𝗖𝗢𝗡𝗡𝗘𝗖𝗧 𝗜𝗧 𝗕𝗔𝗖𝗞 𝗧𝗢 𝗟𝗜𝗚𝗛𝗧𝗣𝗔𝗧𝗛.
On LightPath’s Q4 conference call, CEO Sam Rubin @skrubin said LightPath’s camera systems were being designed into or actively evaluated across seven different platforms — three involving Lockheed Martin, the rest involving other primes and neo-primes.
𝗦𝗲𝘃𝗲𝗻 𝘄𝗮𝘀 𝘁𝗵𝗲 𝗹𝗮𝘀𝘁 𝗻𝘂𝗺𝗯𝗲𝗿 𝗱𝗶𝘀𝗰𝗹𝗼𝘀𝗲𝗱.
We do not know the number today.
It could still be seven. It could be higher.
Investors only see what management can or chooses to discuss publicly.
Meanwhile LightPath already has:
• A record backlog
• Existing defense production
• C-UAS programs ramping toward tens of systems per month
• A qualified low-cost seeker that management says opened the door to “many other opportunities”
• Multiple platform evaluations and design-ins
• BlackDiamond glass and its own IR camera technology
• Optical assemblies and expanded seeker capacity in Texas
• Additional glass-melting capacity
• Relationships with primes and neo-primes
• A publicly identified pipeline that includes new seeker work, missile-program expansion, C-UAS including JIATF-401, FPV drone optics and space
Demand for its glass is running ahead of supply.
Automation is being added for high-volume assemblies.
Capacity is being expanded specifically because any program that moves into production could require very rapid scaling.
𝗧𝗛𝗔𝗧 𝗜𝗦 𝗧𝗛𝗘 𝗦𝗧𝗢𝗥𝗬.
Not that LightPath won every program this week — it didn’t.
Not that OKSI or QuickSink is using LightPath — we don’t know that.
Not that the JIATF-401 awards went to LightPath — they didn’t.
𝗧𝗛𝗘 𝗦𝗧𝗢𝗥𝗬 𝗜𝗦 𝗧𝗛𝗘 𝗗𝗜𝗥𝗘𝗖𝗧𝗜𝗢𝗡 𝗢𝗙 𝗧𝗥𝗔𝗩𝗘𝗟.
For years investors were asked to believe these markets were coming: EO/IR, autonomous targeting, counter-UAS, drones, seekers, precision munitions, domestic optical materials, germanium alternatives and supply-chain resilience.
𝗧𝗛𝗢𝗦𝗘 𝗠𝗔𝗥𝗞𝗘𝗧𝗦 𝗔𝗥𝗘 𝗡𝗢 𝗟𝗢𝗡𝗚𝗘𝗥 “𝗖𝗢𝗠𝗜𝗡𝗚.” 𝗧𝗛𝗘𝗬 𝗔𝗥𝗘 𝗔𝗥𝗥𝗜𝗩𝗜𝗡𝗚.
And LightPath is already inside them — with the backlog, production, qualified seeker, design-ins, material, capacity and pipeline pointed exactly where the money is accelerating.
Which brings us back to the only question that matters now:
𝗔𝗧 𝗪𝗛𝗔𝗧 𝗣𝗢𝗜𝗡𝗧 𝗗𝗢 𝗬𝗘𝗔𝗥𝗦 𝗢𝗙 𝗤𝗨𝗔𝗟𝗜𝗙𝗜𝗖𝗔𝗧𝗜𝗢𝗡𝗦, 𝗗𝗘𝗦𝗜𝗚𝗡-𝗜𝗡𝗦 𝗔𝗡𝗗 𝗖𝗔𝗣𝗔𝗖𝗜𝗧𝗬 𝗜𝗡𝗩𝗘𝗦𝗧𝗠𝗘𝗡𝗧𝗦 𝗦𝗧𝗔𝗥𝗧 𝗖𝗢𝗡𝗩𝗘𝗥𝗧𝗜𝗡𝗚 𝗜𝗡𝗧𝗢 𝗣𝗥𝗢𝗗𝗨𝗖𝗧𝗜𝗢𝗡 𝗖𝗢𝗡𝗧𝗥𝗔𝗖𝗧𝗦 — 𝗔𝗟𝗠𝗢𝗦𝗧 𝗢𝗡 𝗧𝗢𝗣 𝗢𝗙 𝗢𝗡𝗘 𝗔𝗡𝗢𝗧𝗛𝗘𝗥?
Because if that inflection arrives, the conversation around $LPTH changes very quickly.
This stops being about finding another dot.
𝗜𝗧 𝗕𝗘𝗖𝗢𝗠𝗘𝗦 𝗔𝗕𝗢𝗨𝗧 𝗪𝗔𝗧𝗖𝗛𝗜𝗡𝗚 𝗧𝗛𝗘 𝗗𝗢𝗧𝗦 𝗧𝗨𝗥𝗡 𝗜𝗡𝗧𝗢 𝗖𝗢𝗡𝗧𝗥𝗔𝗖𝗧𝗦.
#LPTH #DefenseTech #EOIR #Infrared #CounterUAS #Missiles #BlackDiamond
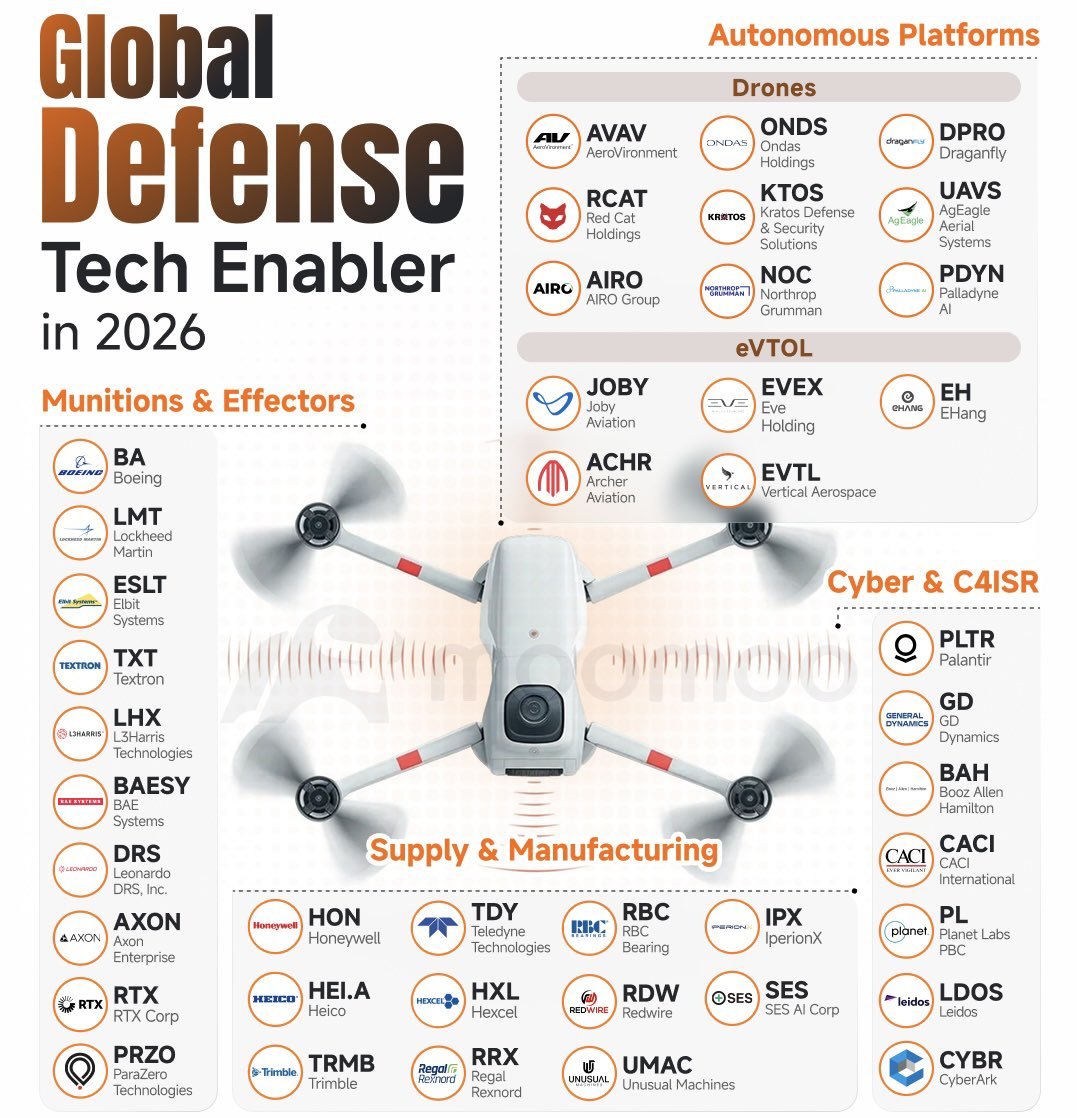
🤔 $LPTH | 그런데 왜 이 지도에는 LPTH가 없지? 😎
미 국방부가 자율전·드론을 핵심 전력으로 끌어올리고 있고,
이 자료에는 드론 플랫폼부터 센서·제조·C4ISR까지 관련
상장사들이 꽤 많이 들어가 있습니다.
그런데 보면서 가장 먼저 든 생각.....
“LPTH는 왜 없지?”✔️
물론, 이 자료가 미 국방부의 공식 공급망 지도는 아닙니다.
작성자가 추적하는 대표 상장사를 골라 만든 일종의
Defense Tech basket에 가깝습니다.
그래서 빠졌다고 해서
LPTH가 이 시장과 관련 없다는 뜻은 아닙니다.
⠀
오히려 공식자료를 보면 LightPath는 이미
• C-UAS용 IR camera 실제 주문
• Long-range EO/IR
• G5 MWIR
• Compact MWIR for gimbal integration
• Seeker systems
• BlackDiamond optics
• Autonomous platform용 thermal imaging
까지 사업영역을 넓히고 있습니다.
최근에는 아예
LWIR zoom
→ Seeker
→ Compact MWIR
→ Redesigned G5
를 AUSA 2026에서 보여줄 차세대 제품군으로 묶고 있습니다.
그럼 왜 아직 이런 지도에는 잘 안 보일까?
제 생각에는 시장 인식의 시차가 큽니다.
LPTH는 오랫동안
“작은 광학·렌즈 회사”
라는 이미지가 강했습니다.
하지만 지금 회사가 움직이는 방향은
Optics
↓
Camera
↓
EO/IR system
↓
Seeker / C-UAS / Autonomous sensing
입니다.
회사는 이미 변하고 있는데
시장의 분류가 아직 따라오지 못하고 있는 셈입니다.
그리고 이 그림을 보면 한 가지 빈칸도 보입니다.
Platform 회사는 많고,
C4ISR 회사도 많고,
munition 업체도 많습니다.
그런데 드론과 자율무기의 ‘눈’ 역할을 하는
Sensor / Perception layer
는 상대적으로 잘 보이지 않습니다.
저는 LPTH가 바로 이 자리를 노리고 있다고 봅니다.
⠀
물론 AUSA 이후 실제로 확인해야 합니다.
제품은 좋은데 고객은 누구인지.
Qualification은 끝났는지.
Production program으로 넘어가는지.
결국 그게 중요합니다.
그래도 개인적으로는 조금 재미있습니다.
아직, 이런 지도에 LPTH가 안 보인다고요? ✔️
뭐… 저 같은 투자자 입장에서는
아직 모두가 알아버리지 않은 것도 나쁘진 않습니다. 😄
조금 더 모아갈 시간이 남았다는 뜻일 수도 있으니까요. ✔️
⠀
🔗 참고자료 / PRIMARY SOURCES
Shay Boloor — 원문 X 게시글
Pentagon Drone Push / Defense Tech Companies
https://t.co/2sHM06SdBE
LightPath Technologies — FY2026 Form 10-K
https://t.co/CB4S1k4wIb
LightPath Technologies — Drone & UAV Thermal Imaging Solutions
https://t.co/bJCKkPWj6g
LightPath Technologies — MWIR / G5 Infrared Solutions
https://t.co/tM9L8hhV94
LightPath Technologies — Official LinkedIn
https://t.co/T4P4WnrnGc
AUSA — 2026 Annual Meeting & Exposition
https://t.co/0VZk6ME2aL
지상 데이터 센터 비용이 점점 올라감.
아마존은 반발이 커지자 지지를 확보하기 위해 향후 5년간 데이터센터가 들어서는 지역에 10억 달러 이상을 추가 투자하기로 함
이건 MS와 구글도 마친가지임.
환경·전기요금·일자리 문제를 둘러싼 우려
데이터센터 건설 중단(모라토리엄)이 시행될 경우 미국이 AI 경쟁에서 스스로 패배를 자초할 수 있다고 경고.
앞으로 2년 뒤, 정말 우주는 AIDC의 새로운 부지가 됨.
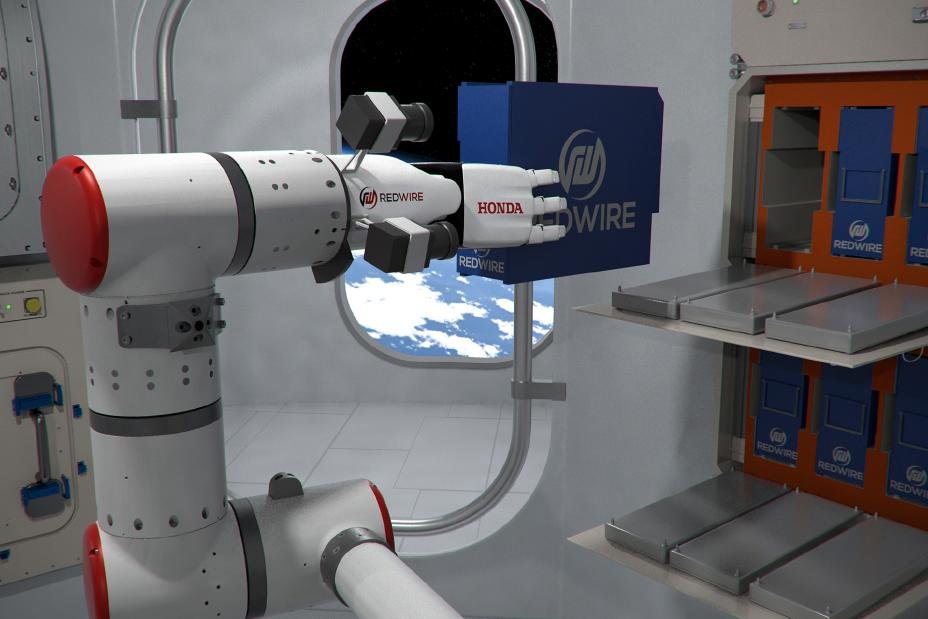
$RDW: Honda today announced efforts to develop a robotics solution for future commercial space stations that could reduce the time needed for astronauts to conduct experiments and laboratory operations in space.
To advance its space station robotics concept, the U.S.-based Honda space development team is engaging with experts at Redwire.
The concept would combine the Honda multi-fingered robotic hand with Redwire’s STAARK robotic arm and experiment locker technology into an integrated system for research operations in orbit.