Ex Meta, Ex Capital One | AI/ML Software Engineer | Deep interest in HPC & AI data center investment (IREN, NBIS, CIFR) | Sharing what I see or believe | NFA
How much is $IREN worth on just the sites it has already powered?
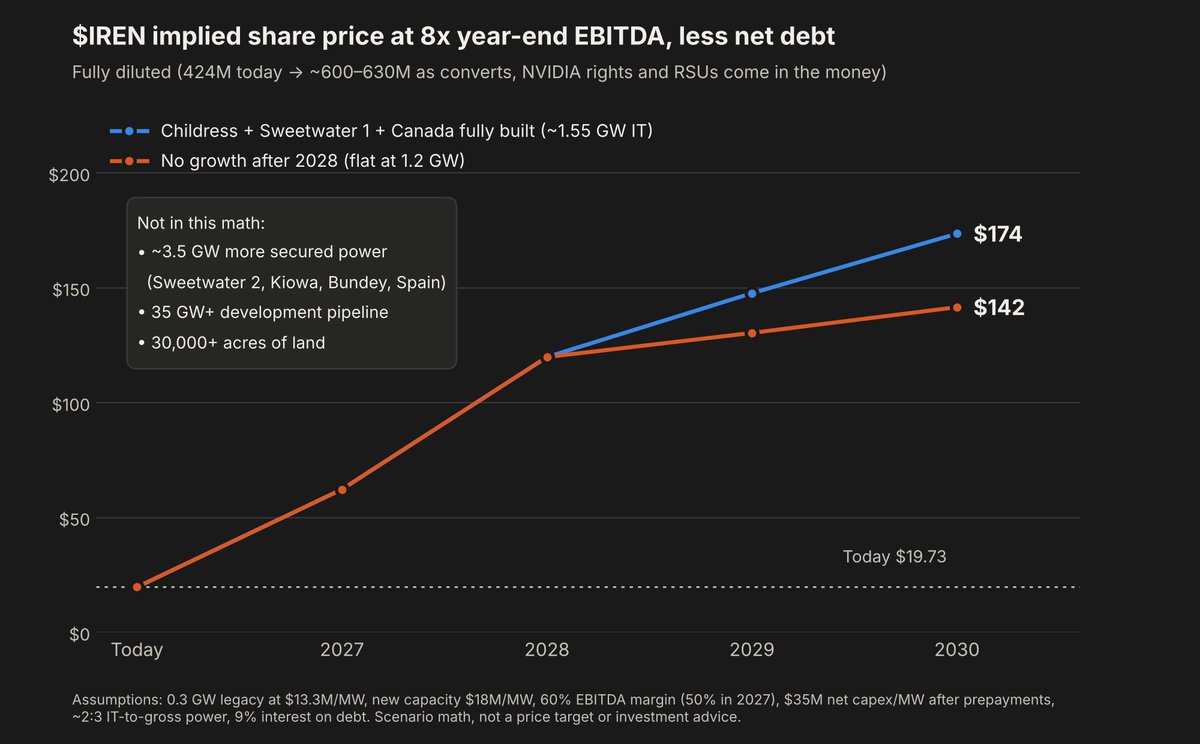
I valued it at 8x year-end EBITDA, less net debt, counting ONLY Childress, Sweetwater 1 and Canada (~2.3GW gross, ~1.55GW of IT). Inputs kept conservative:
• Shares: 424M today per the 10-Q, rising to ~600–630M fully diluted as the converts, NVIDIA's $70 rights and RSUs come in the money
• EBITDA margin: 60% (50% in 2027), well below the 86% AI Cloud gross margin
• Pricing: legacy 0.3GW at ~$13M/MW, new capacity at $18M/MW, below today's $22M 5-yr deals
• Capex: ~$35M/MW net of customer prepayments
• Debt: 9% interest
Where it lands in 2030:
No growth after 2028 (1.2GW): ~$142
All three sites fully built (1.55GW): ~$174
At 10x instead of 8x: $179 / $223. Discounted back at 12%: ~$90–110 today vs ~$20.
Now the part this math ignores completely:
• ~3.5GW more secured power: Sweetwater 2, Kiowa, Bundey and Spain, all starting to energize in 2027/2028
• 35GW+ development pipeline
• 30,000+ acres of land
The numbers above use well under half of IREN's secured power. Imagine what the rest is worth if they execute. We definitely are not bullish enough. FEW.
My math, not a price target or investment advice.
A lot has been happening around $NVDA, and it happened quickly—tanking the market and Neo Clouds along the way. But I believe AI is much bigger than $NVDA. Demand is astronomical; we are still scratching the surface for inference demand, and capex from Hyperscalers and AI labs is growing. Nothing stops this train.
The last few weeks have been brutal for Neo Clouds, with Elon and Chamath talking about risk, the $CRWV debt crisis, Democrats sweeping midterms, etc. We finally got a breather when $IREN and $CRWV reported, confirming demand with good deal economics.
Today is $NBIS’s turn. They will release numbers soon. Many expect $1B in revenue. I’m watching for new deals, customer prepayments, and price per MW to confirm the gap between supply and demand.
$ANT IPO per Anthropic's SEC S-1/A:
• 825M Class A shares at $70–$78 on Nasdaq
• Plus a $26B private placement to Google, NVIDIA, Microsoft & others
• ~$84.6B net proceeds at the $74 midpoint
• 13.09B shares outstanding after the IPO → ~$916B–$1.02T implied valuation
Our initial public offering: https://t.co/Ah4BkI2loD
Legal disclaimer: Anthropic has filed a registration statement (including a prospectus) with the SEC for the offering to which this communication relates. Before you invest, you should read the prospectus in that registration statement (available at: https://t.co/Z44axxzf9b) and other documents Anthropic has filed with the SEC for more complete information about Anthropic and this offering. You may get these documents for free by visiting EDGAR on the SEC Web site at https://t.co/94ojsWZTKi. Alternatively, copies of the preliminary prospectus may be obtained from: Goldman Sachs & Co. LLC, Attention: Prospectus Department, 200 West Street, New York, NY 10282, by telephone at (866) 471-2526, or by email at [email protected]; or Morgan Stanley & Co. LLC, Attention: Prospectus Department, 180 Varick Street, 2nd Floor, New York, NY 10014.
The securities may not be sold, nor may offers to buy be accepted, prior to the time the registration statement becomes effective. This post is not an offer to sell, or a solicitation of an offer to buy, the securities in any jurisdiction where the offer or sale is not permitted.
@daniel_koss Anything specific you're looking for? I'm looking for new deals, customer prepayments, price per MW, etc. to assess demand-supply imbalance.
How much is $IREN worth on just the sites it has already powered?
I valued it at 8x year-end EBITDA, less net debt, counting ONLY Childress, Sweetwater 1 and Canada (~2.3GW gross, ~1.55GW of IT). Inputs kept conservative:
• Shares: 424M today per the 10-Q, rising to ~600–630M fully diluted as the converts, NVIDIA's $70 rights and RSUs come in the money
• EBITDA margin: 60% (50% in 2027), well below the 86% AI Cloud gross margin
• Pricing: legacy 0.3GW at ~$13M/MW, new capacity at $18M/MW, below today's $22M 5-yr deals
• Capex: ~$35M/MW net of customer prepayments
• Debt: 9% interest
Where it lands in 2030:
No growth after 2028 (1.2GW): ~$142
All three sites fully built (1.55GW): ~$174
At 10x instead of 8x: $179 / $223. Discounted back at 12%: ~$90–110 today vs ~$20.
Now the part this math ignores completely:
• ~3.5GW more secured power: Sweetwater 2, Kiowa, Bundey and Spain, all starting to energize in 2027/2028
• 35GW+ development pipeline
• 30,000+ acres of land
The numbers above use well under half of IREN's secured power. Imagine what the rest is worth if they execute. We definitely are not bullish enough. FEW.
My math, not a price target or investment advice.
How much is $IREN worth on just the sites it has already powered?
I valued it at 8x year-end EBITDA, less net debt, counting ONLY Childress, Sweetwater 1 and Canada (~2.3GW gross, ~1.55GW of IT). Inputs kept conservative:
• Shares: 424M today per the 10-Q, rising to ~600–630M fully diluted as the converts, NVIDIA's $70 rights and RSUs come in the money
• EBITDA margin: 60% (50% in 2027), well below the 86% AI Cloud gross margin
• Pricing: legacy 0.3GW at ~$13M/MW, new capacity at $18M/MW, below today's $22M 5-yr deals
• Capex: ~$35M/MW net of customer prepayments
• Debt: 9% interest
Where it lands in 2030:
No growth after 2028 (1.2GW): ~$142
All three sites fully built (1.55GW): ~$174
At 10x instead of 8x: $179 / $223. Discounted back at 12%: ~$90–110 today vs ~$20.
Now the part this math ignores completely:
• ~3.5GW more secured power: Sweetwater 2, Kiowa, Bundey and Spain, all starting to energize in 2027/2028
• 35GW+ development pipeline
• 30,000+ acres of land
The numbers above use well under half of IREN's secured power. Imagine what the rest is worth if they execute. We definitely are not bullish enough. FEW.
My math, not a price target or investment advice.
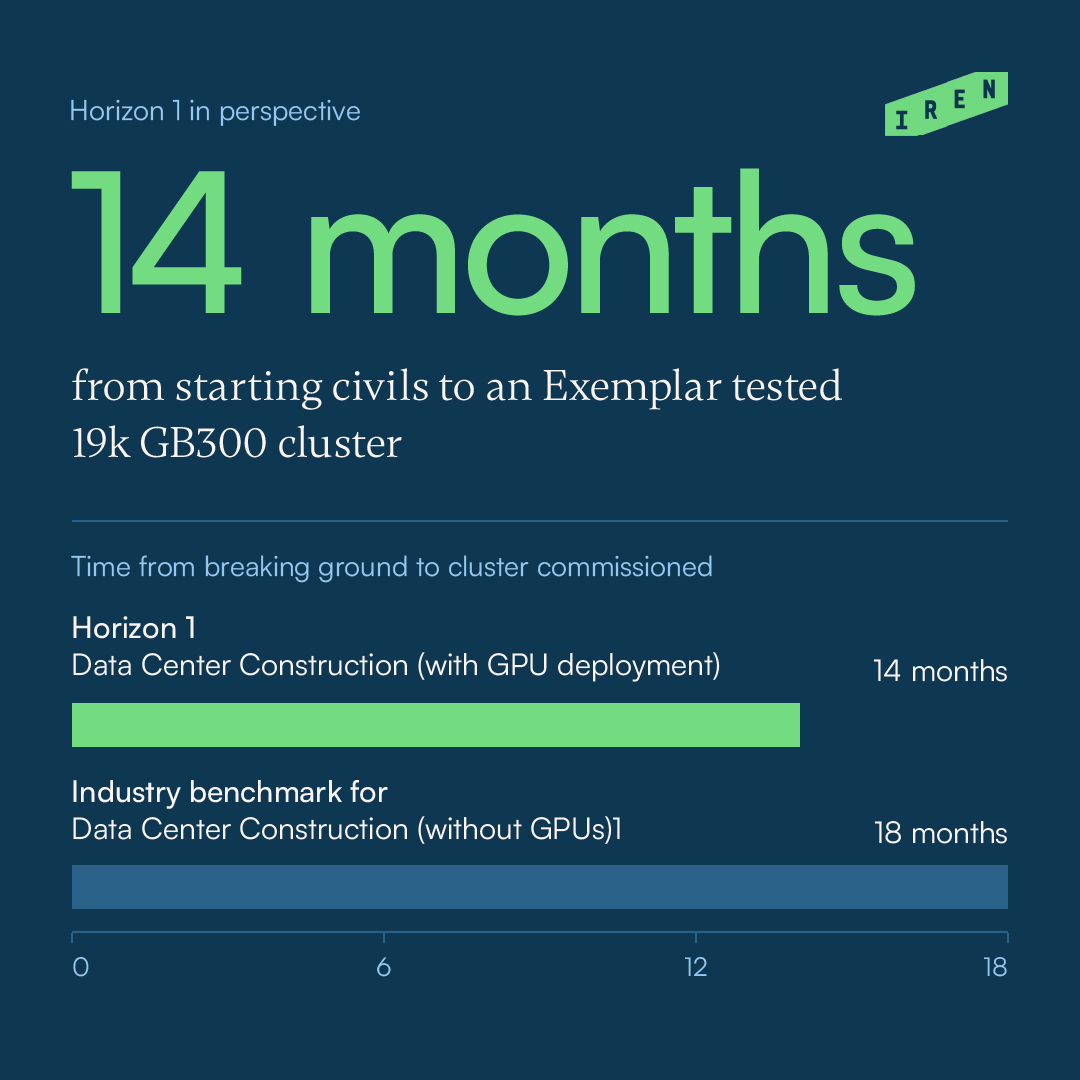
22% faster delivery than the industry benchmark.
Horizon 1, the first of four 50MW (IT) AI Cloud deployments for Microsoft, went from starting civils to an NVIDIA Exemplar Cloud-tested GB300 cluster in 14 months.
IREN's vertical integration delivers end-to-end control across design, engineering and construction, so contracted capacity reaches customers sooner.
Patience is key for fundamentals to catch up to real potential. Once sentiment improves, the stock price will catch up soon. The stock price can oscillate wildly between oversold and overbought.
@Crownedmasses This is the most conservative way to value it, and I deeply believe the price will be much higher once sentiment turns around and revenue starts flowing.
Is the $IREN thesis broken❓
The stock is down, analysts are cutting targets, rates are up, Texas flipped blue and Microsoft is delayed. The narrative writes itself: the $IREN thesis is broken.
The numbers say the opposite.
Payback is shrinking GPUs plus the data center now pay back in ~3 years, down from ~4.5 on the Microsoft contract a year ago. On a 5-year contract, that leaves two years of pure profit and a paid-off data center with 20+ years of life. The next contract in that shell only has to pay back the GPUs. IREN's latest GPU payback is ~18 months, which leaves roughly 42 of 60 months as profit, if we continue same prices after 5 years (very dpeculative)
Customers are funding the build: Microsoft prepaid 20% of contract value. IREN's latest contract prepays 90% of GPU cost, at 0% interest. Add ~50% debt on the GPUs and the whole project is funded without dilution or equity, with the data center still unlevered.
The dilution fear is overdone: IREN is ~$6B short of its $25–30B capex guide, but it sits on $12–15B of unlevered data centers and GPUs. Borrowing against that at ~10% would cover the rest of FY27. Future dilution looks very low, possibly zero.
Pricing keeps climbing Lease rates have gone from $10M to $22M/MW, short-term deals are signing at $40M/MW, and IREN's 4-year-old H100s just repriced +100%.
Higher rates matter less than you think: A $25M/MW contract at 24% interest is about as profitable as a $20M/MW contract at 9% (assuming 90% of GPU cost is debt and there's no prepayment). The pricing gains have already more than offset the rate move. Also, the rate being quoted is CoreWeave's corporate cost of debt, not asset-backed GPU financing. IREN just raised $400M in ABF at 9.5%, and that would be lower with IG backing.
Texas is a smaller risk than it looks: Hinojosa's proposal targets new permits. SW1 and SW2 already have approved grid connections and come online before 2028, and Republicans still hold the legislature. IREN builds miles from residents and doesn't push up local power bills, or use the local water. The real risk is a lower tax abatement (85% today), and IREN has ~35+ GW of pipeline beyond Texas.
The Microsoft delay is Microsoft's request: The delay comes from a cabling change Microsoft asked for, outside the original scope. Because IREN is fully integrated, it could make the change on short notice. The cost is 1–2 months, depending on equipment delivery. Horizon 1 was accepted. That says enough.
What the bears got right: The stock is down and price targets are being cut. For an investor, those are the things that matter least. Last year IREN went from $5 to $70 in six months on a sentiment shift alone. The same happened to the downside the last months. If GPU pricing collapse, the fundamentals will be hit hard.
But today I believe that the fundamentals have never been stronger.
Stock price ≠ the company.
Im long, and strongly believe the stockprice will have a crazy repricing towards second half of 2027. (21$ today).
@TheFinGodFather@scludweed It's very easy to understand and project, but people don’t get the simplicity. Risk-reward has never been better, which is why few succeed in investing. $IREN will be a success story many will regret missing.
Indeed. The foresight companies like $IREN and $CIFR had in accumulating land and power is pretty amazing. Having leaders like @danroberts0101 and @rftylerpage is the cherry on top. Can’t beat deal negotiators and builders of real physical infrastructure driving humanity’s future growth.
@JoshMandell6 Could you do a covered call on Kidney, acquire more $BTC with the premium, and hope your kidney doesn’t appreciate so the call buyer doesn’t exercise? 😉
Fair for high-yield, lease-heavy neoclouds, but $IREN’s slice of that chart is mostly 0–1% convertible notes, fixed-rate and not due until 2031–33. If the stock is above $51–86 at maturity, they convert to shares with nothing to refinance. Near-term principal is only ~$1B a year, GPU loans are repaid by customer contracts, and ~$6B of owned data centers carry no debt. For IREN, expensive credit slows growth but does not threaten solvency.