dave tepper - hands down, GOATED investor
the only investor the other greats admire and respect and would not dare disrespect
he's also misunderstood... known as a great distressed investor, he's also a great macro investor... skates to where the puck is headed, full cycle
Pretty crazy that on a day like today, the S&P 500 nearly triggered a deGraaf Breadth Thrust for the first time since May 2025. 👀
The trigger is 55% of S&P 500 stocks closing at new 20-day highs.
Today, we hit 50.4%.
So close.
@RenMacLLC@granthawkridge@WillieDelwiche
Don, there is a missing term in your equation.
The crunch spread is not: Token Price - GPU rental price.
Rather it is: (Token Price * Token Volume) - GPU rental price.
More simply: Revenue per GPU - GPU rental price.
Continuous throughput improvements for the same exact token mean that volume growth can more than offset token price declines for the exact same model/token
i.e. Kimi K3 token throughput per GPU has recently been improving at a 37% annualized rate driven by inference engine optimizations.
GPU prices are vertical because:
1) Mix is shifting from higher margin frontier tokens to lower margin open-weight tokens. $10 in Claude revenue requires $1 of inference compute. $10 of of open-weight revenue requires $3 to $7 of inference compute given competition between inference providers leads to lower margins. Open-weight tokens taking share is positive for AI infrastructure demand given lower margins at the model layer. The reverse is also true in that frontier tokens taking share is negative for AI infrastructure demand. Open-weight models have been taking share since early summer.
2) Throughput is steadily improving for each individual token type such that GPU compute becomes more valuable even as true like for like token prices decline.
@1BigCountryO for sure a downside risk to spot on nebius, but they control the supply. They can modulate quality and at what terms they bring on supply.
2:30am wake-up insight
Nebius now has spot GPU pricing for available GPUs
Nebius also has a software overlay for “bring your own GPU” for bare metal owners to contribute GPU capacity to the Nebius distribution network
What GPU owner wouldn’t - in the most liquid way possible - contribute GPUs to the Nebius network. It’s free money as a bridge between use or even more indefinite arbitrage between cost and market.
I have to believe this becomes a big business for Nebius. Highly disruptive for Fireworks and Baseten.
Am I wrong?
$nbis
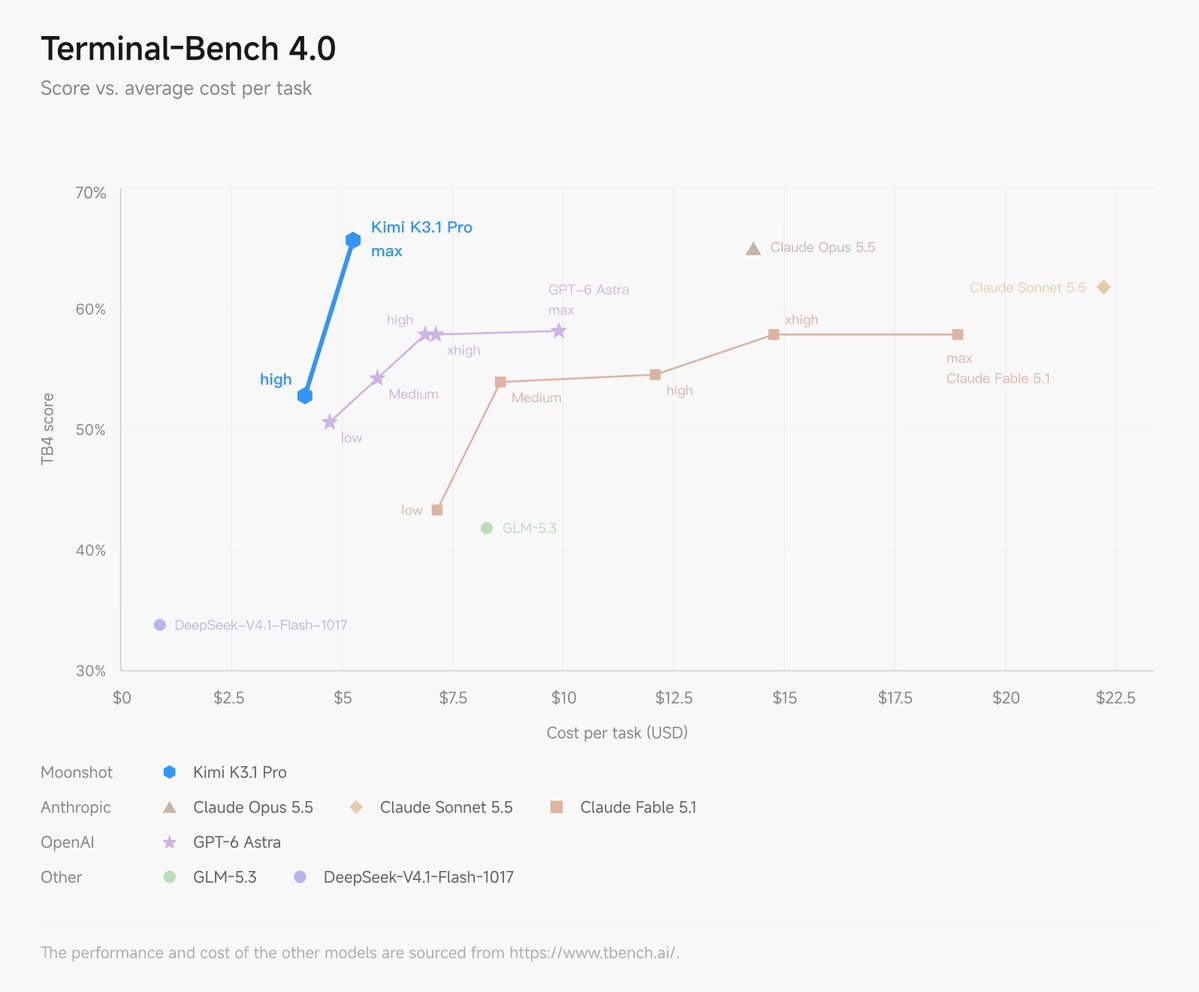
On Terminal-Bench 4.0, which evaluates coding agents on realistic, resource-constrained terminal tasks using strict task-specific tests, K3.1 Pro scores 65.7%, ahead of GPT-6 Astra (58.2%) and narrowly behind Claude Opus 5.5 (66.4%).
Do I still expect the same $NBIS 2027 price target?
Usually I nowadays only share my long-form thoughts on our paid Substack behind a paywall, but because I believe many people got interested in Nebius because of me, I feel like it's only fair to address this topic publicly and for free in the current time where many people panic and are scared.
The no. 1 question I get right now from many $NBIS bulls is if I still expect the same price target for 2027.
Instead of giving you a stupid yes / no answer that would get more likes, I want to break down exactly how I make my price targets and how you can decide for yourself which numbers to use and, as a result, which price target to expect / make your own.
⚙️ HOW I MAKE PRICE TARGETS
When I make my price targets I do it like this:
- I model the business the way I expect it to look like in the future, usually it's 12-18 months out.
- I then apply the valuation framework I think makes most sense (and adjust expected returns for the risk)
- I then apply the multiples that I think would be typical in a "normal" market (long-term median multiple for such businesses, not low or high ones), which means what comparable businesses with a similar model, growth, profitability, profile etc. typically get in a normal market
The 2 big variables here are:
1) the valuation framework (do you use EV/EBITDA for $NBIS or do you use an ARR multiple and adjust the multiple based on your revenue quality, profitability, growth, etc.?)
2) The BIG ONE is the multiple.
My default for $NBIS is 10x ARR.
📊 WHY ARR, NOT TRAILING REVENUE OR PROFIT
I get so many stupid comments on this approach.
Many people think they are financial savants for pointing out that revenue doesn't reflect business durability, ARR is NOT revenue, ARR is calculated by multiplying revenue of the last month by 12, revenue doesn't mean profits, etc.
No shit Sherlock 😂
First of all: you MUST use a revenue metric, because there is no profit yet. You cannot value this on profits that don't exist today.
But you CAN NOT use trailing full-year revenue for a company like Nebius, because they are growing from 1B → 10B ARR → probably 40B+ ARR next year.
This is called HYPERgrowth.
The market is forward looking. What Nebius did 12 months ago, when it was many hundred percent smaller, simply does not matter for the future.
ARR looks at the present. Trailing revenue looks backwards. I actually think you should look at FORWARD ARR, but that's another story.
The dumbest people on this app all point out that the business is not profitable. Thanks to all the quants for this insight.
Why is the business not profitable? One reason is that it's a fresh business that only exists for a few years. It's a baby company and despite the 40B+ valuation it's essentially a startup.
The more important reason is that they are AGGRESSIVELY investing every dollar they make and even taking on dilution and debt to invest as much as possible into the future business, which they do for only one reason: because they (and I as well) believe, based on all available data, it's gonna be incredibly profitable.
Do people on here understand the concept of investing 1 dollar today to make more than 1 in the future? Is that a hard concept to follow?
Then there's another incredibly stupid thing that people on here do: they compare capex (20-25B this year) with this year's revenue or ARR.
Revenue is very stupid for the reason mentioned above, but even comparing it against ARR is very low IQ.
Why? Because the money they spend TODAY is used to build data centers that won't even come online this year. These projects take quarters to years depending on the size.
And they will generate revenue for many years and currently the past spending looks brilliant because chips that the market thought would today be worthless are now selling near the initial prices at launch. A massive divergence between the initial market thought and now reality.
So tl;dr so far: I believe you must use a revenue metric because the profits are in the future (and you should not model it out 3-5 years or it gets very inaccurate), and you must use ARR (not trailing revenue) because this company is growing hundreds of % year over year, STILL.
🧮 HOW DEBT, DILUTION AND PROFITABILITY GET INTO THE MULTIPLE
Now what about profitability, debt, etc.?
You OBVIOUSLY already adjust for dilution in your assumed share count.
And you OBVIOUSLY deduct debt and interest to be paid from future profits.
And you OBVIOUSLY adjust your assumed valuation multiple based on the assumed profitability and durability of the business.
You understand? You DO account for all these things via the multiple.
If you think a business is great and another one is shit, you can use an ARR multiple for both and give one of them an ARR multiple of 30 and the other one an ARR multiple of 1 or 2.
👀 WHAT THE MARKET IS SAYING VS WHAT I EXPECT
Right now I believe Nebius can hit over $40B ARR in 2027 and I do think they are trading below a 1x forward ARR multiple.
So the MARKET (not me) is currently saying Nebius is a shit business.
Ignore all the derps who say Nebius is trading at idk 200x sales or 500x pe etc. all of that is insanely stupid as I explained above.
The market currently treats Nebius like garbage, it's NOT richly valued. You gotta really understand that.
I obviously disagree strongly and think over the next 12-18 months many people will step by step understand the unit economics better, understand how much PROFIT this business will generate. Why will they learn it? Because we'll see Nebius execute and deliver stronger and stronger results quarter over quarter.
I expect not just strong performance from Nebius as a company, I also expect the market to see an ever bigger divergence between companies like Nebius (which I see at the top) and other companies when it comes to execution.
I expect Nebius to get financing at significantly better terms than peers.
I expect Nebius to add more capacity and faster.
I expect Nebius to win on a lot of "boring" topics like customer support, reliability, speed, security, utilization, efficiency, etc. that enterprise customers care VERY MUCH about (FinX might not).
All of these things I believe are the reasons why I think Nebius will outperform and deserve a significantly higher ARR multiple.
I do completely agree with the market that most "neoclouds" are actually shit and deserve something like 1-3x ARR. Personally I wouldn't even touch most of them.
I think many have bad teams, no moats and simply can not execute or build what they promise. Not on the software or physical side and they will simply attempt to copy what others do. This constant lag will lead to significantly worse unit econics!
🐘 THE ELEPHANT IN THE ROOM: THE MARKET ENVIRONMENT
Now do you notice what the big elephant in the room here is that could still massively impact the ARR multiple EVEN IF we agree it's the right metric and even if we agree Nebius deserves the highest one?
It's the market environment. I wrote in the beginning that I expect 10x ARR as the fair and normal multiple for a business of Nebius' quality in a normal market as the median valuation.
But we've seen the market getting increasingly schizophrenic on AI. It goes from parabolic run to panic in weeks. Just looking at all AI stocks shows this. Has nothing to do with Nebius. Right now maybe with the neocloud scare, but it's just another wave. We've had tariffs, DeepSeek, Iran, now neocloud scare, nothing new.
Doesn't matter! The valuation will always reflect the CURRENT market environment.
Things like wars, oil prices, rates, bond yields, etc. will OF COURSE impact the cost of money, the "risk free" return options and the prices and valuations of equities.
Nebius is simply strongly affected by this, just like all other hypergrowth stocks.
🎯 SO DO I STICK WITH MY 2027 PRICE TARGET?
All the business assumptions I made in my Substack article stand and most have gotten better.
The 2 big fundamental changes that have happened since for the negative are
1) the cost of capital seems to be increasing as of today → WE DON'T KNOW where this will be over the next 12-18 months. It can go either way. In the short-term it seems to be higher for the industry overall.
2) as a result valuations have contracted. If Nebius would hit exactly the numbers I'd expect them to hit by 2027 but right now, the valuation multiple would certainly be lower. Maybe 3-7x not 10x.
So yes, I roughly believe in the same price target, but I have no clue how macro will develop in the short-term.
I have fundamentally come to accept that I can not accurately predict Trump. I think macro is in general hard, but you can roughly predict where things go based on physical realities and interstes in my view. But Trump... above my paygrade ^^
As an active trader I personally try to trade around these things, but if you're a long-term investor, I really think you should not care too much about this volatility, because in the long-term you will most likely see Nebius' business develop insanely well WHILE the ARR multiple could very well be volatile af and go anywhere from 5 in a panic to 20x in a mania. It simply will happen in both directions.
For example when Nebius was $300 earlier this year I sold (at $284) while still believing in a 2x higher price target by next year, simply cause I was trading the volatility and expected the market to be in a short-term mania. Did happen and I bought back lower. Cool to add more shares, but NOT NEEDED for long-term gains.
I'm sorry for this long ass post, but since a lot of people here have a lot of their hard earned money on the line and Nebius has a lot of hardcore bulls with very high % concentration, I felt like writing out my thoughts as detailed as possible.
Feel free to agree, disagree or make up your own mind. Just sharing my full thoughts here.
This post is not financial advice, I obviously could be completely wrong and maybe we do in fact go to zero and all the bears are right.
Do your own research and make your own decisions 🤞
$meta by far the most expensive asset in this portfolio
i've got $ACMR at 13x 27E - just entered a buy order and canceled because never go full retard
$ICON and cpo en fuego would be a seller if was long term gains
first big earnings report of the year for me is tonight $wdc short as a hedge against $stx dont love the positioning but has been a great hedge over last 3 weeks
want to add $hpe here tbh but stepping into rising macro / commodity uncertainty not my m.o.
37% cash
competitive dynamics are getting bruuuutal
$SPCX just trashing $CRWV and $CBRS
Gotta assume - I’d call it a near 100% probability - either $SPCX $META or $GOOG announce huge primary equity offerings leading up to Anthropic IPO
If you don’t have cash at scale in the game or models or datacenters you
can’t compete
I don’t own much $NBIS . It’ll either be a rough ride down or a major strategic asset for someone and I frankly don’t know which way.