there are two main strategies among emerging VCs right now: "pickers" and "pricers".
both groups are chasing alpha, but they disagree on where it comes from. if you look at venture math – it's very simple: your return = company value at exit x your ownership at exit, and the first group bets everything on the first multiplier, the second – on the second.
> the key idea of "pickers" is to find the 0.0001% of founders with the highest potential on the market, without regard to ownership or valuation. their logic is like if you hold a stake in the "new anthropic" at exit, even under 0.05%, that’s still 3x+ on a sub-$50M fund.
but the main problem is that the top 0.0001% of founders are visible to a lot of players, especially given how dense VC networks are in hubs like SF/NYC. competition there is for access (not discovery), and in practice, even if an EM has a relationship with an [openAI research scientist] who once randomly mentioned possibly starting a company, they can still end up as a small ticket in a party round at a price set by a large fund (for whom an early check at 3x price, and the whole seed portfolio, is a tiny % of AUM).
that makes them a price-taker. the "even 0.05% of the new anthropic returns the fund 3x" argument is mathematically correct, but the I think the main question is how many times that manager actually gets into those rounds, bc otherwise you end up with a consensus index with 2/20 on top.
> the core strategy of "pricers" is to find underdogs in markets with much less competition, where you can actually "control ownership" through check size and valuation.
the main risk here is adverse selection. a cheap valuation outside the hubs sometimes reflects not a market inefficiency, but a genuinely lower probability of a big outcome. on top of that, late-stage capital still sits in SF/NYC, so the company either relocates (and the arbitrage closes) or has a harder time raising follow-on rounds. and ownership still has to be defended (given how hard reserves modeling is and where pro-rata stands in today’s market).
so in my view, both strategies can work, but in practice the first sells to LPs much better: logos and fast markups produce a strong TVPI going into Fund II.
the second sells on a model and a spreadsheet, and markups come slower, so it looks worse on early numbers, even if it may end up delivering more DPI.
Tim Draper says late-stage VCs are really just investment bankers.
@timdraper: “There are all these late-stage venture funds who are probably going to be eliminated by AI fairly soon, but they’re making 2 and 20 on $20 billion… They’re just saying, ‘Hey, don’t do an SPV. You need $10 million? Here’s $100 million.’ And they’re kind of ruining companies.”
“I hope the LPs are smart enough to say those were not venture capitalists. Those were investment bankers. We should not throw more money at them.”
“The investment-banker venture capitalists have probably seen their final days.”
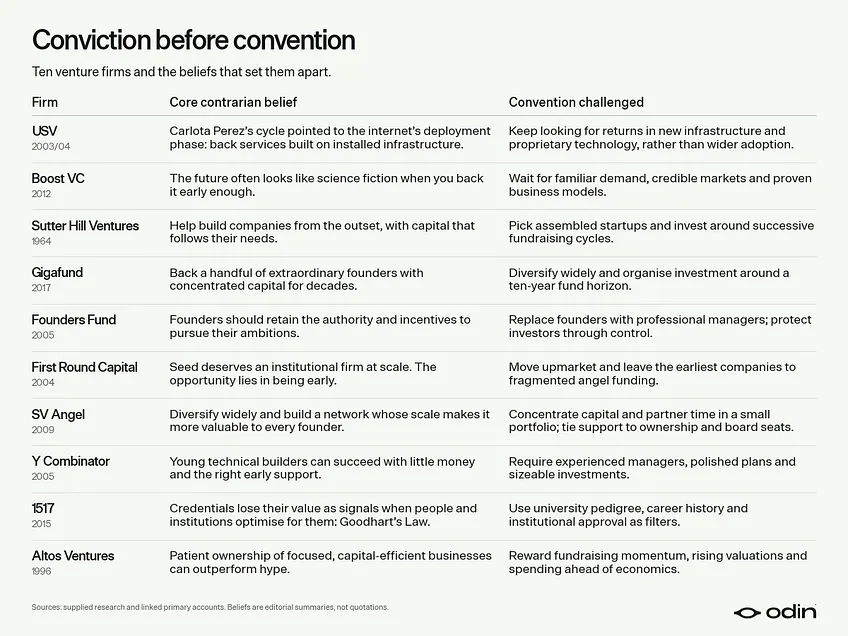
Successful venture capital firms share a few features with successful venture-backed startups.
Generally, both are built on contrarian beliefs.
In fact, the early-stage venture market is dependent on a broad base of contraians who open the aperture for downstream investors.
A few examples:
what’s the point of being the first check LP?
I spoke with a bunch of LPs in NYC last week and the consensus opinion is that nobody wants to be in the first close.
everyone wants to be the last LP, bc technically there is no incentive to go early. when you invest in a startup, the whole point is a lower price per share (which depends on check and valuation [cap]) and more ownership, and if you miss the round, next time you pay more, so that’s why all VCs battle to be the “pre-pre” check and get as much ownership as they can at the lowest valuation possible.
as an LP you get a stake in the fund without that price link, and most benefits actually come through SIZE, not SENIORITY (e.g. the biggest anchor gets a side letter for co-investments with discount), so you can always pass on Fund I and join the next fund. yes, there are cases where you join the first close and get a mgmt fee discount, but for most LPs it’s not a trigger.
imho, being the first LP actually matters, especially now.
after 2008 we saw the first true early-stage VC era, and the number of managers kept growing (with small fluctuations in market corrections). for most EMs any LP’s check would still be taken today, but the key difference is the following:
> AI catalyzes the creation of new GPs (exited founders, operators, researchers), driven by potential super-returns in the era of the biggest tech revolution. yes, fund formation is down vs 2021 today (post-ZIRP lesson), but I’d bet this is what turns it back up.
> LP competition will grow, as belief in EM alpha is becoming consensus (smaller funds tend to outperform bigger ones at the top of the TVPI distribution per Carta + 50% of EM-focused fund of funds were founded after 2020).
> although most capital goes to mega funds, there is a barbell inside the EM market: (а) the best emerging GPs raise pretty fast and (b) don’t want hundreds of LPs. they choose one anchor, a few more FOs and (in the best case) X% allocation for FFF.
as the number of GPs grows, so does the dispersion of quality inside the pool (more first-timers, more unknowns), and the best managers get more LP demand than they have capacity for. when capacity is capped and price is fixed, allocation goes by relationships (not by check size), so that’s why being the first check LP matters:
1/ you actually get into the fund (and the best funds only take certain number of LPs).
2/ you build conviction in a very narrow market where everyone knows each other, which starts a referral loop and builds your reputation.
3/ which lets you see MORE managers and see them EARLIER than anyone else.
4/ which brings you back to the 1st point. and yes, the loop only works if you pick the right GP to be first with.
There is about to be one less private unicorn soon, and it is a special one. A good moment to look at the private unicorn landscape before Anthropic’s IPO changes it forever.
As of October 1, there were 2,030 privately held unicorns in the world, with a combined post-money valuation of $9.0 trillion. Northern America and Asia account for 81% of them by count and 88% of their value. Europe has 14% of the unicorns and 9% of the value.
The reason is a handful of very large companies. Anthropic ($965 billion PMV) and OpenAI ($850 billion) are each valued above all European unicorns put together. The two of them make up 20% of global private unicorn value.
If Anthropic’s post-IPO value holds up through the lock-up period, many VC investors will hope that the other $8.0 trillion can be unlocked the same way Anthropic’s roughly $1 trillion is about to be. That would ease the profound illiquidity in the VC world and transform the entire US VC industry.
P.S. The chart shows every private unicorn with a known valuation, sized by post-money valuation and grouped by region. We will update it after Anthropic’s IPO.
Most LPs default to the consensus branch because it is easier to underwrite, while the pre-consensus layer does the discovery for the whole market on the smallest share of capital.
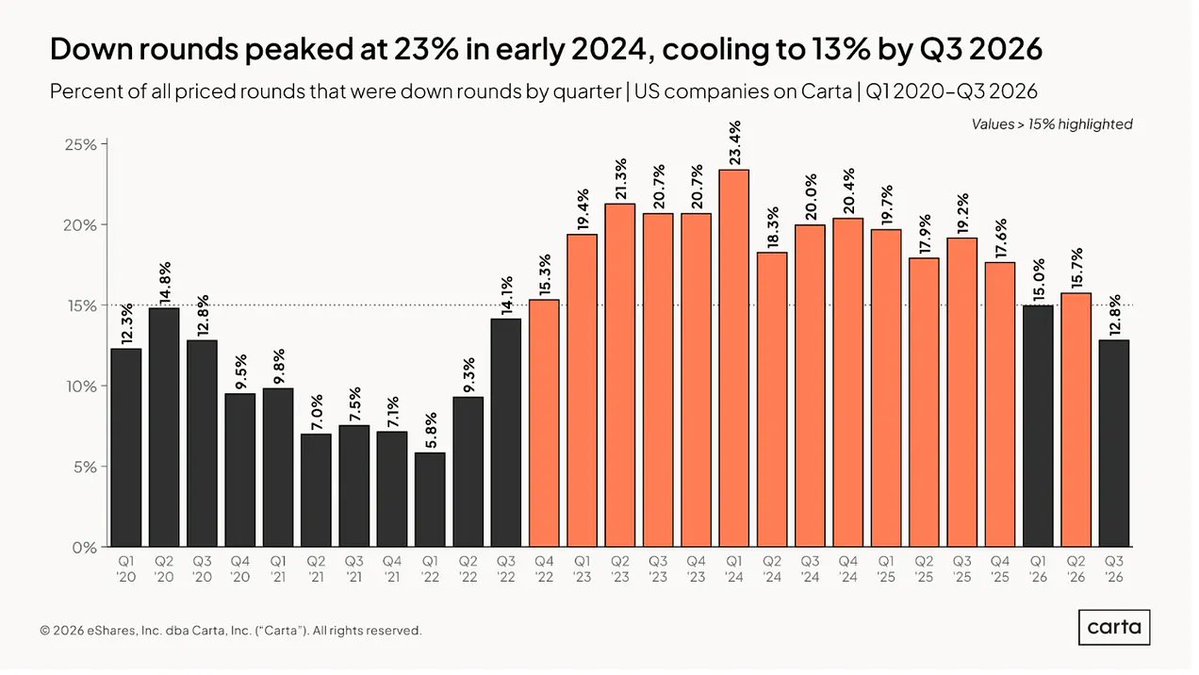
Per @TheFundCFO, year-end marks season comes with down rounds at 12.8%, participating preferred in 10%+ of rounds, FASB’s new lockup rule, and draft estimates better done before the holidays.
Year-end marks don't have to wait for January.
▫️ 12.8%: Q3 down rounds, a four-year low, per Carta
▫️ 10%+: Q3 rounds with participating preferred, so check the terms behind the price
▫️ 2028: when FASB's new lockup rule (ASU 2026-03) is required, with early adoption open now
▫️ 1 memo per material holding: method, inputs and why the mark moved
Estimates before Dec 31. Final marks in January.
https://t.co/vG2JWQvUbM
When do you start your Q4 marks?
#VC #FundCFO #Valuation
@atomico's State of European Tech 2026: ~100 funds close a year at a median of $70M, $81B invested with 12 $1B+ exits, 18.5% net annual returns over 10 years, and just 7 tech IPOs this year.
This 2026 State of European Tech report has just been released by @Atomico.
As usual, it's a comprehensive look at the growth and development of Europe's venture capital ecosystem, with some insightful comparisons to the US.
A particular theme in this year's report is the need for stronger exit markets.
This, I believe, should be a higher priority for policy makers than trying to push more capital into growth-stage companies.
Broadly, Europe's tech sector has two problems:
- At the base, where the cost of admin and compliance makes running a small venture fund prohibitively expensive, which limits the surface area of venture capital. The success of US VC is built on a huge network of angels and microfunds who lead discovery.
- At the top, where the exit market is simply more attractive in the US. Europe lacks the depth of capital for young tech companies going public, so it's a typical story that the greatest success stories feel they need to look to the US for an IPO.
There's a naive belief amongst politicians that the solution is to drive more of Europe's institutional capital into VC. I dare say this would be a mistake; Europe would end up with the same problem of market concentration and stagnation as the US. Large institutions are fundamentally misaligned with the venture strategy.
A better solution (aligned with initiatives like the Mansion House reforms in the UK) would be to create products which drive institutional capital toward new tech IPOs. This solves the mismatch between European institutions and VC illiquidity and fees, lowers the risk of investing in tech, accelerates liquidity, and creates a more attractive local exit market.
It would be a real mistake to just look at headline funding numbers and believe that Europe should blindly try and match the US, without acknowledging the cracks that are emerging in an oversized, overconcentrated US VC market.
tl;dr — If you fix entry, and exit, and the middle should broadly work itself out in a healthy market.
There is plenty of work to do to make Europe a better environment for tech companies, which represents a huge opportunity for legislators.
Reading the SOET report is a good place to start.
Thanks to @twehmeier for inviting me to contribute this year; and for giving me the near impossible task of writing about VC market concentration in <300 characters.
Get the report: https://t.co/SJ8Xo0ZIQA
The Mess of Pottage
Pro-rata used to be the law for almost 2 centuries, and in today's venture it's a favour. At @murphcapital we went down the rabbit hole, traced the right from its roots in American law to current investor agreements and put a price on it: where it came from, what it's worth to an emerging fund, and why it stopped being honoured.
Key takeaways from our deep dive:
1/ Pro-rata went from a negotiated perk to standard paperwork. The clause appeared in 26% of venture-backed IPO filings in 2001-07 and 59% in 2013-21, while @ycombinator moved it from the SAFE to an optional side letter in 2018.
2/ For a typical $31M emerging fund the first follow-on cost less than 10% of its reserve in 19 of 26 winners, while keeping up in every round would have cost more than the whole fund in 16.
3/ Pro-rata is worth next to nothing until it's worth a fortune. In a winner even later follow-ons pay off: @figma's seed shares returned 376x at the IPO, Series B 100x and Series C 30x.
4/ Two-price rounds give the lead the cheap seat. In 7 recent deals @sequoia came in at an average $110M valuation, while investors a month later paid $3.4B. Early investors get a paper markup or a pricier seat, and their LPs lose the upside they paid for.
5/ Honour systems end when the biggest players outgrow them. The average US VC firm is now almost 8x the median, up from 2x in 1988. Venture can make pro-rata real, with a price for every waiver, or drop it, and either beats today's in-between.
Read the full deep dive on our Substack: https://t.co/u54I6q5Arf
BREAKING: @serenawilliams and @bethferreira launch Starfire Ventures, targeting $200M to back seed to Series A tech-enabled and AI-native companies across health and wellness, financial management and the experience economy
The world’s richest female athlete has already backed more than 100 startups through Serena Ventures but now wants to build something that doesn’t have her name attached—and can last long after her.
Read more: https://t.co/uGXeA89QDZ
📸: Jamel Toppin for Forbes
@MeghanKReynolds on the Anthropic IPO reversing liquidity logic: late-stage venture set to return capital in under 2 years, LPs comped on IRR rewarded for speed, and venture growth becoming the shorter-duration asset next to PE.
Heard from VC LPs this week: 😳 🫣
Lots of silence thanks to a wild news cycle, a MSFT outage and a lot of breath holding for the Anthropic IPO. So many VC LPs are comped on IRR. Both the scale of multiple on early rounds and speed to exit will make for many happy LPs. Most LP $$ in < 2 years. Will be good for sustained allocations to VC Growth, particularly as PE performance lags.
BREAKING: @mandeepsinghuk joins @TapestryVC as a Partner, investing in European deeptech and AI founders at the earliest stages across London and San Francisco
@pluralplatform raises €1B, split between Fund III and follow-on investments, backing European founders in energy, AI infrastructure, defence and health.
Per @leehower, public markets show a VC-style power law: buy-and-hold in a single stock lost money about 60% of the time over the past century, and roughly 4% of stocks produced all of the market's net gains.
We think of VC investing in private tech startups as being dramatically different than public markets. Maybe that's wrong.
VC is a power law where most startup investments lose money and a tiny handful generate the vast majority of positive return. The public stock market on the other hand generates a lower but more consistent "beta" return.
But that's not really been true in the last couple years, and it turns out that's not really been true for the last century. In the last 3-5 yrs, a handful of public companies account for a large portion of the gain of the broader market indices.
And if you look back a century this pattern holds (see paper below). Buying and holding a particular stock was a money losing investment ~60% of the time. Roughly ~4% of stocks generate produce all of the net gains of the market. Sound like a familiar pattern?
I have some thoughts on why this may be. Will try to write in more depth soon.
https://t.co/9LEJWcyOHL
Venture returns come from underwriting uncertainty, and too much capital per partner leads to overpaying for plain risk and losing the tail of the power law.
Venture capital is dead (again).
More money is being raised by fewer investors. So far in 2026, funds over $1 billion have taken 72% of all venture money raised. Last year it was 34%. Ten years ago, it was 16%.
Even firms famous for staying small, like Benchmark and Union Square Ventures, have caved. Benchmark’s five partners raised $425 million in 2024. This June, they raised $2 billion.
When a fund has too much money per partner, they are forced to cope by either making bad deals or by taking on less uncertainty. The former is bad business, the latter is not venture capital.
The last time this happened was the 1980s. A decade when money per venture investor tripled, median returns fell from above 30% to 8%, and firms moved into buyouts and rollups. Even Sequoia dabbled in LBOs. By 1994, Marc Andreessen called Silicon Valley “dead in the water.”
In his latest essay, Colossus contributing editor @ganeumann explains what happened next, what’s likely to happen now, and which firms are best placed to win.
https://t.co/Z1OR1m795B
Introducing Norwest 18, our largest fund ever. This $4 billion is for every stage of the journey.
The path to building a successful company is rarely linear, especially when you're building something that's never existed.
We backed @raincards when the company was just a Notion doc and the big idea to bring stablecoins to everyday commerce. We led @ICON3DTech’s Series B to help usher in a new era of construction. And we were the first institutional investor in @vuoriclothing years before it became the $5.5B apparel brand it is today.
Having a diversified strategy means we can back companies at any point in their lifecycle — an approach that has shaped our work with more than 750 companies over 65 years, and we’re proud to carry it forward with Norwest 18.
@_AlexMenn's fundraising cheat sheet for Fund I/II in 2026: a pipeline split into 3 LP groups, a year of pre-launch relationship warming, $1M of small tickets behind $15M+ total capital, and an edge written out against 10 direct competitors.
Personal update: today we’re launching Mission Street Capital.
@SurbhiTodi and I met as housemates at Mission Control, the oldest hacker house in SF, where we lived, breathed, and cooked with the best founders well before anyone knew them.
As hacker houses rise in popularity, they’re becoming talent clusters for exceptional hackers to meet and work together.
Our fund’s thesis is in identifying brilliant oddball builders emerging out of these talent clusters. Builders recognize other builders.
Our fund is backed by hacker house alumni, technical leaders from OpenAI and Anthropic, and GPs, partners, and emerging managers at the most iconic funds (a16z, CRV, Emergence, Uncork).
Thank you to our LPs including @AriX@thedanigrant@KevinUnkrich@tanzealous@ashvinair@mgrczyk@nikhilthota@SoheilK@jamdac@caitlinbolnick1@anamitra@DOitChoco@v_maini@aaronligon@crapshoot101@PachexMix