🚨 INSTITUTIONAL ACCUMULATION ALERT 🚨
STATE STREET JUST REVEALED A $292M POSITION IN $IREN
• 6.39 MILLION SHARES
• $292M REPORTED VALUE
• +143.84% SHARES
State Street is one of the world's largest institutional investors, with $57.9T in assets under custody/administration and $6.3T in AUM.
Another major institution loading up on $IREN. 👀🐋
$IREN was built for this exact moment.
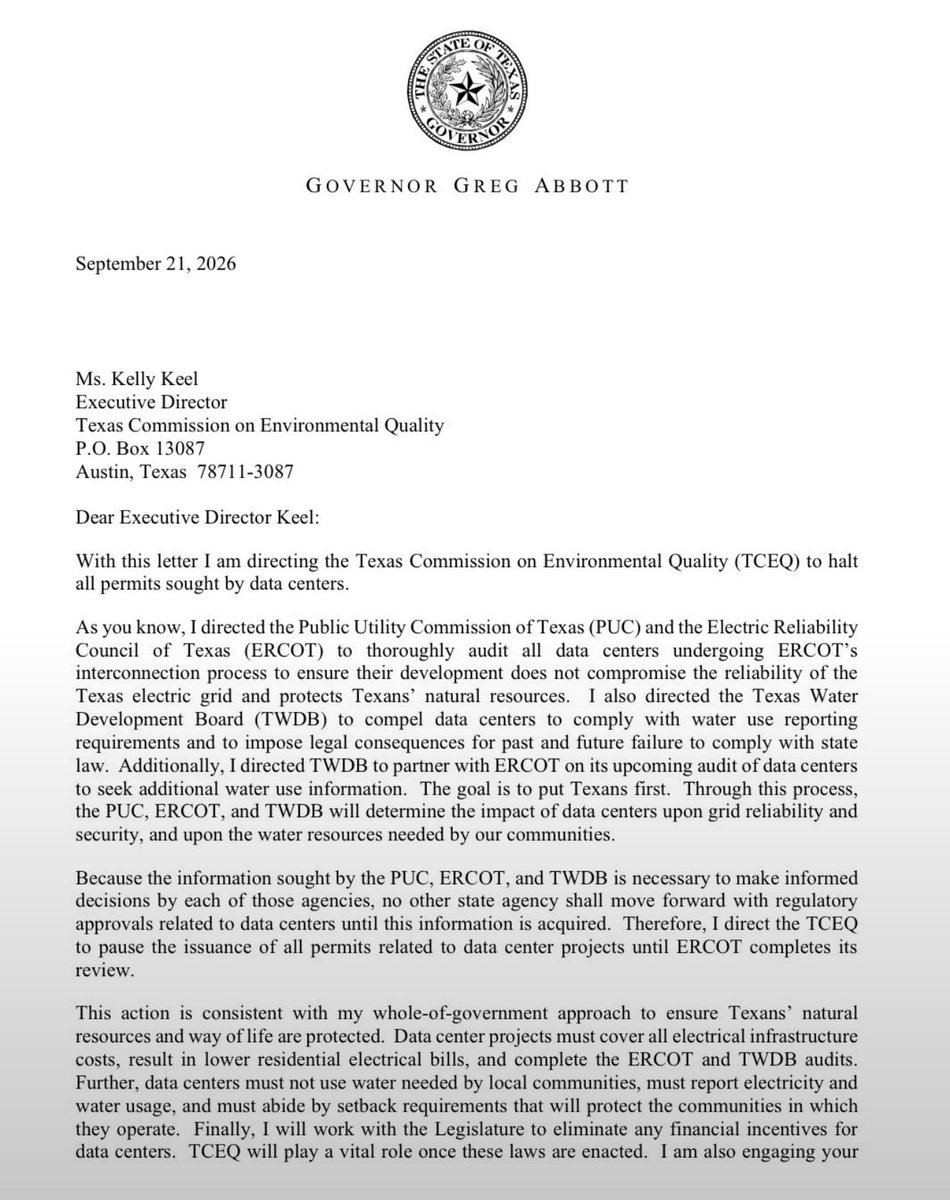
Texas is raising the barriers to entry for data centers.
$IREN already owns the land, power infrastructure, and critical assets- with active power capacity and massive sites already under development.
As establishing new supply becomes more difficult, the company’s advanced infrastructure- now a scarce resource- gains significant value.
That is $IREN’s advantage. 👇👀
#AI #AIInfrastructure #DataCenters #Power #IREN
#IREN #AI #ArtificialIntelligence #AIInfrastructure #AICloud #CloudComputing #DataCenters #DataCenter #GPU #GPUCloud #HPC #NVIDIA #Microsoft #Hyperscalers #Neocloud #Inference #AICompute #GenerativeAI #MachineLearning #TechStocks #GrowthStocks #NASDAQ #WallStreet #Investing #FutureOfAI
I've been in $IREN for almost two years.
Watched it go from a Bitcoin miner pivoting to crack AI to a $4B contracted ARR AI Cloud platform with Microsoft, NVIDIA, Perplexity, Figure, Together AI, Fluidstack, Fireworks, potentially Anthropic, backed by 5GW+ of power.
But something feels different now.
I've never seen the excitement this high.
Chamath names $IREN among the winners of the open-source AI shift.
JPMorgan flips Underweight → Overweight.
0 analyst Sells, targets stretching toward $99.
NVIDIA has warrants on 30M shares at $70.
And now the operating story is catching up.
Horizon 1 delivered and accepted by Microsoft. H2 commissioning, H3 and H4 behind it. 2026 capacity basically sold out. 2027 building toward 1.2GW.
Demand is strengthening. Pricing is improving.
The market used to price $IREN like the AI story was something that might happen.
It's happening. Demand, pricing, customers, infrastructure, execution, narrative all converging at the same time.
I think the run into year-end could be very special.
My Friday $IREN musings… 2027 EOY price targets.
$IREN is targeting ~800MW of AI capacity by YE2027. If it executes, and new capacity is contracted near the $20M+/MW economics IREN is currently seeing, I estimate the company could exit 2027 at roughly $14B in ARR and ~$6.5B in annualized EBITDA.
Using reasonable assumptions for debt, dilution and valuation multiples, my rough YE2027 scenarios are:
Bear: $75/share
Base: $155/share
Bull: $245/share
The path to the base case is straightforward to track: H2–H4 delivered → $4B+ ARR operational → H5/H6 and Sweetwater on schedule → 2027 capacity contracted around $20M+/MW → financing secured without excessive dilution → ~800MW operating by YE2027.
The wild card: this gives very little credit to IREN’s 5GW+ power pipeline beyond 2027.
Execution is everything, but if IREN delivers what it has publicly laid out, the numbers get very big, very quickly. $IREN.
Enjoy your weekend $IREN Fam. Get outside. Be with friends and family. Go Gators!🐊 Go Rays! Go Bucs!
$IREN is the next 10x stock.
Fiscal 2027 expected: revenue 2.82B (299% growth)
Fiscal 2028 expected: revenue 7.2B (156% growth)
And these are low.
Don’t fall over valuation. Run projections and you’ll see it’s still a STEAL for its 15B market cap.
Chart from @stock_analysisx
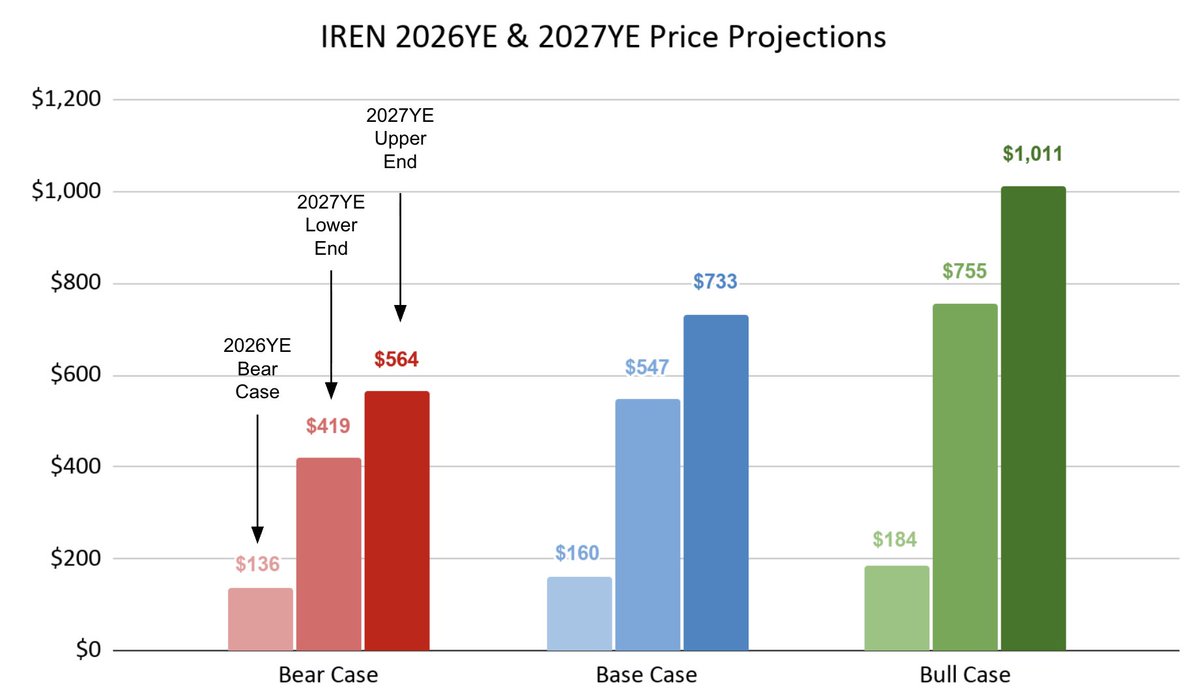
It's about time I release my $IREN price predictions by Q1/2028 based on monetizing and operating their 2027 year end target of 1,210 MW. These price targets will for sure come off as bullish to many based on how others are evaluating $IREN in this space, so I'll explain my reasoning and my math. One thing I've noticed though is that many investors aren't bullish enough considering the scarcity in the supply of AI compute to meet the demand side.
First and foremost, I assess my price projections based on two key variables:
1) Execution
2) Pricing power ($ per IT MW)
To make things simple, I make a somewhat bold assumption that $IREN will execute on their 2027 guidance with no delays, especially since execution moving forward is largely de-risked because of the partnership with NVIDIA to accelerate GPU deployment (up to 5 GW), as well as completing Horizon 1-4 for Microsoft by the end of this year.
For pricing power, I've mentioned before that $ per IT MW is in an exponential trend and has compounded 10% per month since November of 2025 to arrive at $25m per IT MW as of August, 2026. For evaluating potential pricing terms that we can see throughout 2027, my bear case assumes zero increase from $25m per IT MW (HIGHLY UNLIKELY), whereas my base and bull cases assume compounding at 5% and 10% per month, respectively. The recent GPU rental rate increases essentially validate the likelihood of something close to this happening, so I calculated a blended $ per IT MW for contracting additional 2027 MWs for each case.
- Bear: $25m per IT MW
- Base: $36m per IT MW
- Bull: $54m per IT MW
ARR Projections
I do think $IREN can hit $4.9b ARR by year end 2026, so layering this on top of what management can potentially contract throughout 2027 provides the following year end ARR projections based on contracting an additional ~454 IT MW out of the ~494 IT MW they've guided for in 2027. Since they've already contracted ~40 IT MW (60 MW gross) with NVIDIA at their Childress site, this accounts for $680m ARR for each case.
- Bear: $16.9b ARR
- Base: $21.9b ARR
- Bull: $30.1b ARR
Enterprise Valuation
Enterprise valuation multiple is always an interesting topic to me since I don't assume $IREN will experience multiple compression beyond 2026, however, many others do for different reasons. I assume multiples of 15-20x EV/EBITDA and my reasoning is rooted in how management addresses 4 major risks faced by every company across this industry.
1) Secured Power Capacity
2) Revenue Concentration
3) Shareholder Dilution
4) Capital Efficiency
My reasoning:
1) All of 2027 capacity guided by $IREN has secured grid interconnects.
2) 2026 contracts have diversified customers with contracts falling in the 3-5 year range. Management guided to maintain this approach when negotiating new contracts in 2027.
3) Overhang of further major dilution was removed given a current funding gap of $3b-$8b to meet their funding requirement for 2027 buildout. Hard to believe that a large portion of this comes from dilution when they can use other means of funding like debt and revenue.
4) ROIC (return on invested capital) for newer contracts are projected to be 15%+ while significantly outpacing the company's WACC (weighted average cost of capital) of < 5% for 2027. IREN's value creation is quickly increasing as pricing power is substantially increasing.
Equity Valuation & Shares Outstanding
I assumed $IREN would require a maximum of $8b in additional funding for their 2027 buildout where $2b of that would come from dilution. This would generate ~50m shares if raised at today's prices. Moreover, NVIDIA's $2.1b investment in $IREN at $70 per share would generate an additional 30m shares. Add these to the 380m shares outstanding as of Q2 earnings and it equates to 460m shares -> round up to 500m shares for conservatism. I assumed the other $6b in funding would come in the form of debt (no revenue for conservatism), which assumes $7.6b + $6b = ~$14b in debt. Also assumed cash position remains the same as reported in Q2 earnings, so $6b. Factor this into calculating equity valuations for each case and divide by 500m shares.
- Bear: $419 to $564
- Base: $547 to $733
- Bull: $755 to $1,011
I know these prices seem crazy given IREN's current stock price but that's what happens when you invest in scarcity, especially when the company is currently being valued like they're making colocation contracts, yet they're negotiating contracts with $ per IT MW terms multiples beyond any colocation contract out there. Asset prices can compound at levels most investors don't think is possible and the current imbalance between supply and demand of AI compute, factoring in the power bottleneck on top, greatly support this thesis. I genuinely think we can see $IREN trading above $600 per share (MY BASE CASE EXPECTATION) once quarterly revenues from achieving ~$22b ARR hit Q1/2028 earnings. That's at least a 13x from today's prices in under 2 years, which is why I say $IREN is a generational opportunity. But remember, this is simply my opinion where I try to keep things simple and logical at the same time.
Open to hear constructive feedback from anyone. @BitcoinAIGuy@bitcoinbutcher1@Agrippa_Inv@StockAnalystPro@mcF_dan@Stemulite23@GlobalCollapse
Citibank TMT: "lasers and optical fibers are being positioned as the "next HBM."
I've been talking about lasers like $LITE / $AAOI since 2025... and architectural shifts toward CW, ahead of the current industry consensus.
And fully agree with Lightmatter/Citi.
Just for reference:
For lasers: $LITE / $SIVE / $AAOI / $COHR / $MTSI / Furukawa / Sumitomo are your better known ones.
For fiber: $GLW / Furukawa / Fujikura / Sumitomo are your more well-known exposure (obviously a lot more in the supply chain) *disclosure, personal exposure to theme
With added commentary that: "Tight supply conditions will support a scarcity premium for these assets."
We're already seeing price hikes with lasers as seen with $SIVE channel checks at CIOE 2026 Shenzhen today + $LITE commentary from earnings.
So I think the 2027–2028 photonics supercycle will look a lot like memory did in 2025–2026.
Especially as optical content/GPU-ASIC goes up significantly per Goldman Sachs revised estimates...
Ojalá el Elche CF reconsidere volver a instalar las barandillas en las escaleras. El primer partido ayude a una señora a subir y ayer a un señor.
La accesibilidad también debe formar parte de la mejora del estadio y para muchos buenos abonados, esto es un mundo. @elchecf 🤝
$IREN remains my highest-conviction pick for the rest of the year, and with four months still to go, I think there is a very good chance we see this stock double from here. There will obviously be volatility along the way, but I believe the setup going into year-end gives IREN a real shot at $80 and beyond.
$IREN: The Good, The Bad, & The Ugly
We just released our new $IREN deep dive into last week's earnings results.
I've spent the past week going through everything; the call, the deck, the 10-K and the filings around it, and I can say this with full confidence....
I haven't seen a single sell side report or X post that covers these earnings anywhere near as comprehensively as this piece does.
As some of you may already know from my recent post, the biggest takeaway from $IREN's Q2 (FYQ4) earnings was the company's emerging financing flywheel.
$IREN has quietly built a structure of GPU financing, customer prepayments, and soon data center refinancing, all working together to fund the build-out without leaning on the equity market the way the company used to.
This report goes several levels deeper than that post, breaking down $IREN's evolving financing strategy piece by piece and showing why it's turning into a genuine moat that very few competitors can replicate. It fundamentally changes the dilution math this stock has been punished over for years.
I firmly believe this is the most important development since the company committed to building its own cloud, and most investors still haven't fully grasped what it means.
The entire first section covering the financing flywheel is free to read (no paywall). If you're on the fence, start there & get a sense of the depth you can expect from the rest.
The report also covers what genuinely disappointed me this quarter, from the Q4 2027 liquid-cooled timeline and what it says about $IREN's standing with $NVDA, to the soft AI Cloud print, to an IR track record that keeps undercutting one of the strongest stories in the sector.
Throughout it all, I'm reflecting on my broader $IREN thesis at large, so this is as much an assessment of where the company stands today as it is an earnings breakdown.
We also made a dozen custom graphics for this report, because topics like the flywheel are far easier to grasp visually, with supporting imagery, than through text alone.
As always, it's written so that virtually every investor can follow it. Whether you hold $IREN, cover it, or are considering a position, I'm certain you'll derive great value from this one.
Once you've read it, I'd love to hear your feedback in the comments. Thank you very much!
Enjoy! ✌️
https://t.co/hH5ZE40ehS
3. Koltuk sırtından başlığı çekin ve sonra çıkarın onu
4. Çelik uçları kullanarak arka camı kırın ve camı mutlaka çıkarın..
Araba,Tasarım ve Mühendislik gereği yüzmeye uygun şekilde yapılmıştır ve arka cam her zaman dışarıya bakacak şekilde duracaktır.
Bu,Sizin hayatınızı kurtarabilir..