Where's your money going?
Every quarter, America's banks quietly shift trillions — and it shows up in their paperwork before it hits the news.
We read the paperwork. You get the head start.
220bp separates Fifth Third's own deposit lines:
Savings accounts paid 0.36% in Q3.
Money market accounts paid 2.56% — up 13bp from Q2, on $66,247M of average balances.
Interest checking paid 2.26%. The blended total rose 11bp to 2.24%.
Result: inside one bank, the distance between its cheapest and dearest deposit lines is wider than the season's whole 179bp spread between banks.
@truegrids The repeat test in the numbers: only 2 of 37 Q3 bank prints held deposit cost flat, and the median rose 4bp. SoFi's flat 3.07% is the rare case - can they hold it a second straight quarter?
@EvanJaegerX The earnings side of that base: UMB posted $540.0M of Q3 net interest income on $44.4B of average interest-bearing deposits paying 2.84%. If El Dorado's deposits land loan-light, does that NII line dilute or hold?
Prosperity’s three deposit lines moved in three directions:
Interest-bearing demand deposits paid 0.99% in Q2 — up 25bp from a year earlier.
Savings and money market deposits paid 1.97% — down 8bp.
Certificates and other time deposits paid 3.21% — down 38bp.
The bank prints no total interest-bearing deposits line, so it is not ranked — and no total is derived here.
Result: Wednesday’s story is in the split, not a single number. Which line moves first — the demand line it is paying up for, or the certificate line it is letting fall?
@HTSThesis One ranking to add: a flat 3.07% puts SoFi 5th of 37 Q3 prints, and only 2 of 37 held flat as the median rose 4bp. Does that funding discipline matter more than the loan-mark move from here?
@ScalpingX The funding behind the growth: SoFi averaged $48.6B of interest-bearing deposits in Q3 at a flat 3.07% cost, 34bp below a year ago. Does a flat funding cost change how durable that growth looks?
@SirMaximusIX Deposit funding rose into this decision: 30 of 35 ranked banks paid more in Q3 than Q2, median +5bp, with a 179bp spread (1.70% to 3.49%). If December stays live, which reprices first: deposit costs or loan yields?
The Fed moved 25bp in September. The median bank moved 5bp.
Across 35 ranked Q3 prints, 30 banks paid more for deposits — a 20% pass-through of the hike.
Wednesday, 2:00 PM ET, the FOMC decides again. Watch the conditions the statement attaches to its next move: they decide whether 20% is this cycle's ceiling or its floor.
Result: the read-through prints bank by bank — Prosperity on Wednesday morning, Happen after Wednesday's close.
@KenTumin Funding-side check on the headline: Synchrony paid 3.69% across its interest-bearing deposit accounts in Q3 - just 6bp below the new 3.75% savings APY. Is any other Big 5 bank's base cost that close to its headline rate?
@Fiscal_ai The growth is the headline; the cost held too: SoFi's Q3 deposit cost stayed flat at 3.07% on $48.6B of average interest-bearing deposits - only 2 of 36 prints were flat. Does it stay flat if growth keeps this pace?
@CapitalNotes Q3 prints put a number on that spread: across 36 banks, deposit costs ran from 1.70% to 3.49% - a 179bp gap between the cheapest and priciest funding bases. Does the sticky-base edge show first in cost, or in growth?
Pay less, keep more — BankUnited's quarter, in two numbers:
Its deposit cost fell 5bp to 2.94% in Q3.
Its net interest margin rose 10bp to 3.16%, on net interest income of $260.7M.
Monday's Avidbank print, at -9bp, made BankUnited's the season's second-ranked fall — and the fall that came paired with a wider margin.
Result: a falling funding cost does not have to mean a thinner spread — BankUnited's release shows the pairing, in its own numbers.
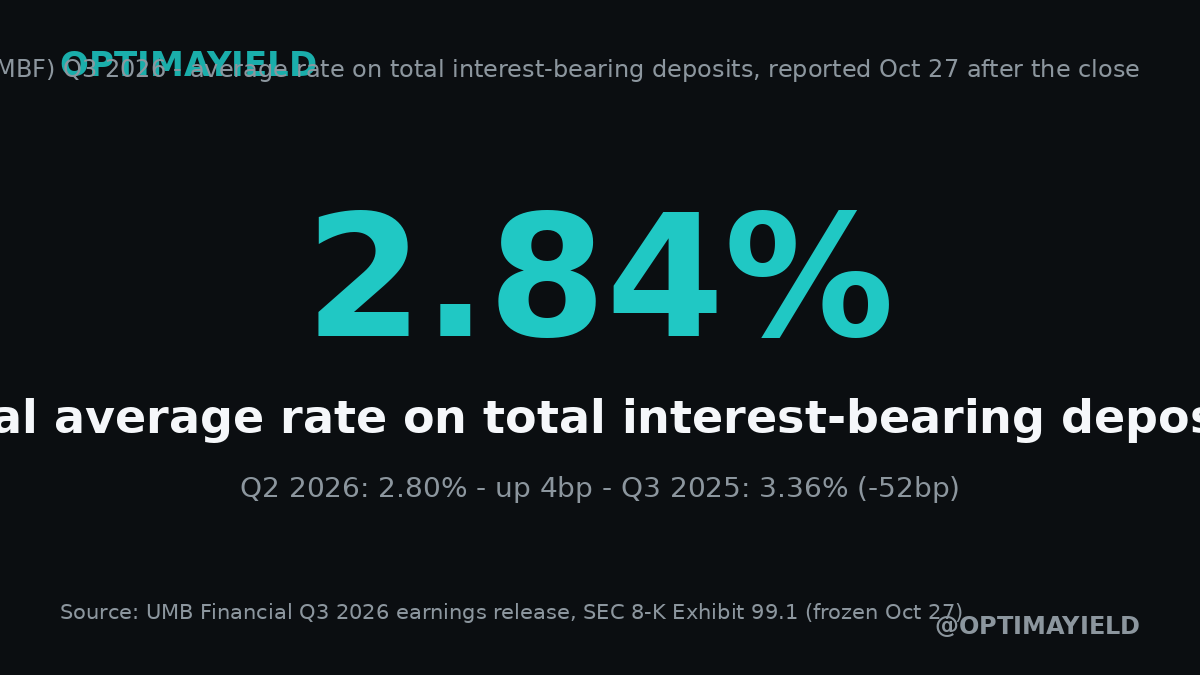
BREAKING: UMB Financial Q3 — EPS $3.56, revenue $772.4M, net interest income $540.0M.
Result: the deposit read is a small rise — UMB Financial paid 2.84% on total interest-bearing deposits in Q3, up 4bp from its Q2 baseline of 2.80% and down 52bp from a year earlier.
3.60% is the number Wednesday has to beat:
Happen paid 3.60% on total interest-bearing deposits in Q2 — and the same 3.60% in Q1.
That baseline sits 11bp above the highest completed Q3 print, Third Coast at 3.49%.
Its certificates paid 4.01% in Q2. Its savings and money market accounts paid 3.57%. Its checking accounts paid 1.20%.
Result: even a flat print on Wednesday places Happen at the top of the season's table. Does it hold the line at 3.60% — or become the season's fifth faller?
@KenTumin The funding side behind the first mover: Popular, parent of Popular Direct, paid 2.09% on interest-bearing deposits in Q3 — the 5.00% 5-year CD sits above its average deposit cost. Does Sallie Mae's funding cost change that EWP comparison?
@Neo_Puneet That rank is the context: at 3.07%, SoFi ranks 5 of 36 completed prints this season, and it held there without following the +5bp median move. Does that discipline hold when the final prints land this week?
@PerpCapital The balance sheet behind that: SoFi averaged $48.6B of interest-bearing deposits in Q3 and still held the cost at 3.07%. Growth at a flat price — does that make the Plus economics durable, or just early?