Microsoft is an absolute beast of a business.
$38B of net income +60% YoY
Meanwhile stock is down 19%.
Of the hyperscalers, $MSFT is the most hated despite owning 27% of OpenAI.
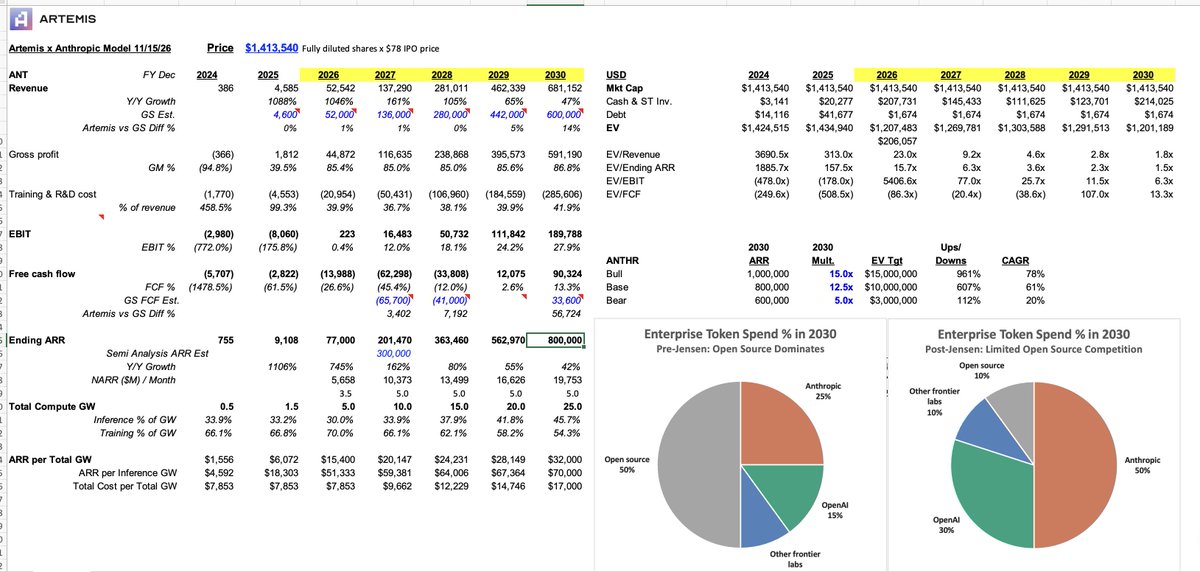
UPDATED ANTHROPIC MODEL: We revise down our Anthropic 2030 ARR to $800B ARR down 20% given @SemiAnalysis_ revision on AI capex.
View: Anthropic will go public this week and I believe $ANT trades end of week at $2.8T (2x from IPO price) with $800B ARR '30 and $1.6B total revenue from 2027-2030 that offsets the $900B of compute already committed. Implies 9.2x '27 revenue / 4.6x '28 revs.
Thesis: Anthropic is the #1 winner of enterprise AI and agents are still early on the adoption curve (<1% business adoption globally). Growth mode makes sense.
We believe Anthropic gets to $800B ARR in '30 w/ 50% marketshare for enterprise token spend and with Anthropic Direct, can get to 13% FCF margin and 28% EBIT margins in 2030.
Context: Biggest threat to Anthropic was open source tokens being significantly cheaper than SOTA models e.g Fable / Mythos and enterprises shifting spend.
But... with Jensen out at $NVDA = BAD for open source since less chips to train / distil = GOOD for $ANT marketshare.
Here's our updated model:
- 2026E: $81B ARR Oct'26 +14x YoY -$14B FCF
- 2027E: $201B ARR + 149% YoY at -$62B FCF
- 2028E: $363B ARR +80% YoY at -$33.8B FCF
- 2029E: $562B ARR +55% YoY at +12B FCF
- 2030E: $800B ARR + 42% YoY at +$90 FCF
Here are our base case assumptions:
1. REVENUE: $1.8T of Enterprise spend in 2030 up 10x from 2026 Estimate of '26 $180B ARR of AI Enterprise spend from @MenloVentures
> Fortune 5000 go from 0.1% token spend of OPEX to 10% and agent adoption goes from <1% to 10%+
NOTE: our base case doesn't account for $ANT Ode with Anthropic (take rate on services), drug discovery / life sciences, other areas ... we just project out token spend to replace / augment knowledge work. Can easily add another $500B ARR to 2030.
2. REVENUE: ANT owns 50% of enterprise spend in AI in 2030 -- we think open source is no longer a strong threat.
> OpenAI is the biggest credible threat at 30% market share (Open Source we have as <10%)
3. COST: Anthropic Compute Assumptions
- $70B ARR per inference GW due to token efficiency
- $17B Cost per GW driven by Anthropic Direct and owning / leasing data centers directly - less $ and faster time to launch
- 25 GW secured by EOY 2030 requiring another 15 GW in addition to $900B already committed.
KEY: we believe $ANT will generate $1.6B of revenue next 4 years which pays back the $900B of compute Anthropic has for leases that run through 2036....
Get the full model here: https://t.co/Q7k12MoV1D
Thesis: $HYPE will do $4B of revenue in 2030 (up 8x from ~$500m run rate today) and be valued at $230/token (up 3.5x from today) NOT as a better crypto exchange but as the #1 winner of RWA perps.
Take: Market is missing that Hyperliquid is NOT JUST a crypto exchange but is becoming THE default venue for investors trading global markets 24/7 from equities and commodities to FX, indices and pre-IPO companies -- taking share from ICE / CME (combined ~$17B of annual revenue) not Binance.
Price Target: We believe Hyperliquid will be a $230/token in 2030 (up 251% from today) with $4B revenue in 2030 revenue.
$4B of revenue at 25x P/S implies $104B in outstanding market cap & $230B of FV in 2030.
Core Assumptions:
> Hyperliquid becomes a generational business from the growth of RWAs perps not crypto.
> Assume $HYPE captures 0.50% of entire 2030 Notational Trading Volume, taking share from CME and ICE.
> Hyperliquid processes ~$21T of annual RWA volume by 2030, at roughly 1.6bps blended take rate (perps is 2 bps, HIP-3 is 1 bps), that generates approximately $3.2B of transaction revenue
> HIP-3 is the #1 growth driver of $HYPE revenue moving forward (50%+ of transaction revenue, up from 15% today)
> Market is missing stablecoin revenue which will contribute another ~$1B annual revenue with $25B of supply and 4% reserve yield.
Full memo to drop tomorrow at 10am ET
Happy Hyperliquid Summit Day in NYC.
Hyperliquid.
The first Thesis by @artemis is out!
Thesis is an investing show where analysts, investors, and founders come on to defend one clear market view.
Our first episode is with the stablecoin / fintech goats @HadickM@ElBarto_Crypto.
We talk about who wins and loses from $OUSD and what Open Standard means for $CRCL.
Bonus: Rob nailed the prediction on the USMNT win over Bosnia :)
Enjoy 💜
Free Cash flow for Hyperscalers inflect in 2029E
Street has Hyperscaler FCF going down in 2026 and then growing exponentially in the years after spending on CapEX.
.@wallstreetbets is doing it again.
For a decade, Wendy’s on r/wallstreetbets meant one thing:
You blew up your account.
The joke was simple: lose everything trading options, and your next stop is living behind the Wendy’s dumpster.
It was never really about $WEN.
Until now.
Year-to-date, our Reddit data shows ~16,800 comments mentioning “Wendy’s” across r/wallstreetbets, r/stocks, and r/investing.
Most of that was culture.
Roughly 1 in 6 comments literally mentioned a “dumpster.” Thousands more referenced working there, the drive-thru, or Frostys.
The actual cashtag, $WEN, barely showed up.
In other words, 95%+ of the Wendy’s conversation was the meme.
Then the stock broke.
$WEN came into this setup near a 52-week low, down more than 45% over the past year. The business was under pressure from slowing traffic, higher beef costs, weaker consumers, and ugly same-store sales.
The Q1 print told the story: U.S. same-restaurant sales fell 7.8%, net income dropped, and adjusted EBITDA declined 10.6%.
The stock got cheap. The dividend yield pushed toward distressed-value territory.
Then the activist angle entered the chat.
Nelson Peltz and Trian own roughly 16% of Wendy’s and have reportedly explored funding for a potential take-private bid.
No formal offer has been made, but the ingredients are there:
A broken stock.
An activist with a large stake.
A new CEO.
A new CFO.
A turnaround narrative.
A possible take-private.
A heavily shorted float.
Reddit noticed.
And this week, the meme finally crossed over into the ticker. Reddit $WEN mentions exploded to 602, by far the biggest spike of the year. At the same time, the stock ripped to $7.40 after-hours on June 23, up 18%.
Is this the next Gamestop?
Took a small position in $UBER recently
-AV risk to Uber is less than people think, given @Uber loyalty
-Their membership program has been increasing and has more members than @Walmart
I just wrote an article about the SaaSpocalypse and why I think the market is wrong on $CRM $NOW and $WDAY on @artemis. Please see below
https://t.co/6GSwAYNyN6
Coinbase is the winner of AI-native finance.
We believe $COIN can be a ~$300B+ company (6x from today)
Artemis open sources the BEST Coinbase financial model using onchain data.
You can now build models like the BEST analysts.
We believe Coinbase is WINNING in stablecoins, agentic commerce – not just as a crypto exchange.
Here’s the core assumptions
> Stablecoin supply reaches ~$3T in 2031 (~US Treasury official estimates)
> USDC is 30% of stablecoin supply
> Agentic Commerce ~$7.5T in yearly spend in 2031
> Coinbase Agentic Commerce is able to monetize and captures 1bp of the entire TAM
> Net transaction revenue grows 11% CAGR
> Subscription & Services goes from 40% of total revenue to 65% of revenue in 2031
In our bull case, Coinbase does ~$23B revenue in 2031 with ~$10B of net income.
At 30x PE that assumes ~$300B of marketcap (6x+ from today)
Full 12 page thesis drops at 5pm ET 👀
. $BIRD — Contrarian LONG.
Thesis: Cash-Return Setup with Free AI Stub
Trades at $5.68. Strip out the Q3 2026 special dividend ($4.00/sh in cash) and you're paying ~$1.68 for the NewBird AI stub.
Assumptions:
• $39M sold to American Exchange Group sale → $35–$36.2M net proceeds
• $35M / 8.71M shares out → $4.00–$4.15/sh special dividend
What's left in the stub (~$1.68/sh)
• $50M convertible
• $2.75M signed GPU lease
• = a real, funded AI shell — not vapor
Why $BIRD is mispriced
~70% of the current price is a near-deterministic cash return; the AI shell is effectively a free option on top.
The market is still pricing this as a meme/risky name when the fundamental setup is closer to a cash-stub arb with optionality.
Neobanks spent 15 years handing rent to sponsor banks, but now they don't have to.
In the past 4 months:
- @coinbase applied for a national trust charter
- @nubank received approval to create a US bank
- @krakenfx got a Fed Master Account
They can now access legacy payment rails.
At the same time, traditional fintechs are plugging into global crypto rails:
- @SoFi launched SoFiUSD
- @stripe acquired @Stablecoin , @privy_io and launched @tempo
- @RobinhoodApp is launching Robinhood Chain
The stack is getting crushed from both ends and the winners will own both sides of it.
Let's dive into what's happening 👇
https://t.co/TqLoiJ1YLM now trades for 1.4x ARR 🥶
- $1.3b ARR
- 25% YoY
- 25% FCF
Down 50% YTD. ALL in on AI Sidekick, Vibe, AI workflow, etc.
Do we not think Monday could be a Claude Cowork competitor?