I never introduced myself.
A few months ago I started writing investment theses.
No audience. No noise. Just research.
I came to X for one reason.
I’m not here to sell hopium.
I built a concentrated portfolio with a single target:
10x in the medium term.
Not 40 tiny positions hoping something works.
Not chasing whatever is trending this week.
Asymmetric bets.
Position sizing.
Timing.
What actually moves capital.
The same edge.
Here, in public.
I don’t chase stocks.
I hunt them.
— Pulse Capital
Everyone is laughing at $AAOI's stock price right now. The bears are celebrating, the shorts are getting louder, and suddenly everyone seems convinced that the entire investment thesis is falling apart.
It's funny how quickly sentiment changes when a stock starts going down. The same people who were excited about the company's growth prospects a few months ago are now questioning whether there's even a future here.
But I'm not investing in $AAOI based on what its stock price does this week, next week, or even next month. I'm investing based on what I believe this company could become over the next 12–18 months.
If $AAOI manages to scale toward $500M in monthly revenue next year, we're talking about a potential $6 BILLION annualized revenue run rate. That's an entirely different business from the one investors are looking at today.
And the opportunity isn't coming out of nowhere. AI infrastructure spending continues to accelerate, hyperscalers are investing billions into networking capacity, and the transition toward higher-speed optical connectivity is creating enormous opportunities for suppliers capable of scaling production.
Of course, execution matters. Manufacturing capacity needs to ramp, customer demand needs to translate into shipments, and margins need to improve alongside revenue. None of that is guaranteed.
But that's precisely why these opportunities exist. The market wants certainty, and by the time everyone agrees that the growth is real, a significant portion of the opportunity could already be priced in.
Maybe I'll look like an absolute idiot for being this bullish while everyone else is laughing.
But if my thesis plays out and $AAOI delivers anywhere near the numbers I believe it's capable of, I'll look like the GOAT.
And I'm perfectly comfortable being laughed at until then.
Mid-2027 management framework is ~$5.65B annualized run-rate (not full-year revenue), vs ~$2.6-3B street consensus for FY27.
If they hit it, $68 looks cheap vs Meta Prometheus-scale optics demand — but it all hinges on execution of the 650k-unit ramp, yields, and no major dilution/competition issues.
What if @aleabitoreddit posts again that he’s buying another 0.5% - 1% of the $SIVE float during the Halloween shopping season?
Could we see the May & June days come back and $SIVE back to $10 USD? 🚀
We’ll find out soon what Sivers management is cooking.
One thing is certain, the next surprise could shock the chart watchers once again with an unpredictable parabolic move.
$LITE $AXTI $LITE $COHR $SIVE $AMD
Citadel just fully covered their short in $SIVE (0.55% → 0%).
This is not random. While the market is still panicking on AI names, the actual business is starting to deliver:
• Strategic LiDAR customer just placed first production orders. Shipments begin in Q4, volume production in 2027. $53-138 M lifetime potential is no longer just a design-win — it’s moving into real revenue.
• Yesterday’s EGM locked in a new management incentive plan and switched auditors to EY. Classic setup for a US dual listing in 2027.
Short interest remains high (~6%), the stock has corrected hard, and the photonics ramp (LiDAR + AI datacenters) is finally happening.
Smart money is covering into the inflection. The R/R is getting better, not worse. NFA
PS: long $SIVE
@Citadel has exited $SIVE completely - from 0.55% to 0%.
What do they know that’s coming that could send $SIVE to the moon?
Could the November earnings call reveal:
New hyperscaler connections - $AMD / $NVDA?
New Chinese plug-and-play partners?
More major Photonics customer announcements?
Further progress toward a U.S. listing?
Everyone will find out soon…
$IREN x $NVDA
This is the kind of thing people miss when they’re only looking at headline risk.
NVIDIA just dropped Minerva, an AIOps platform built for AI factories. It watches the GPUs, the network, the storage and the actual jobs running on them, then flags problems before they waste compute.
IREN is already using it.
Their CTO basically said the goal is to spend less time firefighting and more time keeping the GPUs productive. In a market that’s suddenly obsessed with utilization and whether all this AI spend is worth it, that matters.
It also fits the bigger picture. IREN already has the Microsoft contract, Exemplar status on GB300s, and the strategic NVIDIA partnership. Being early on Minerva just puts them deeper in the preferred stack.
Not the most explosive headline on its own, but a quiet signal that the operators who can actually maximize what they already have are the ones that should come out of this stronger.
PS: Still LONG and BULLISH on $IREN
NFA
$IREN is partnering with $NVDA to launch its new Minerva AIOps platform on IREN AI Cloud helping catch problems before they disrupt GPU workloads.
That could help IREN generate more revenue from its existing GPUs without needing to spend more on hardware.
$NBIS $SNDK $TSM
Hedge funds just had their worst day since COVID and retail is aggressively buying the dip in these three.
This isn’t the AI thesis breaking. It’s overcrowded funds being forced to deleverage hard.
Meta announced a new share class to fund more AI capex and the market read it as “this is getting expensive.” Result: forced selling across the sector.
Meanwhile:
• TSMC just reported another record quarter and says AI demand is still outstripping supply.
• Sandisk is in a real NAND shortage for data centers (not a phone cycle).
• Nebius is pure neocloud with hyperscaler deals.
When institutions sell on positioning and retail buys the actual bottlenecks, it’s usually an opportunity.
Are you buying or waiting for the war to ease?
Pretty crazy Reuters piece on the global selloff.
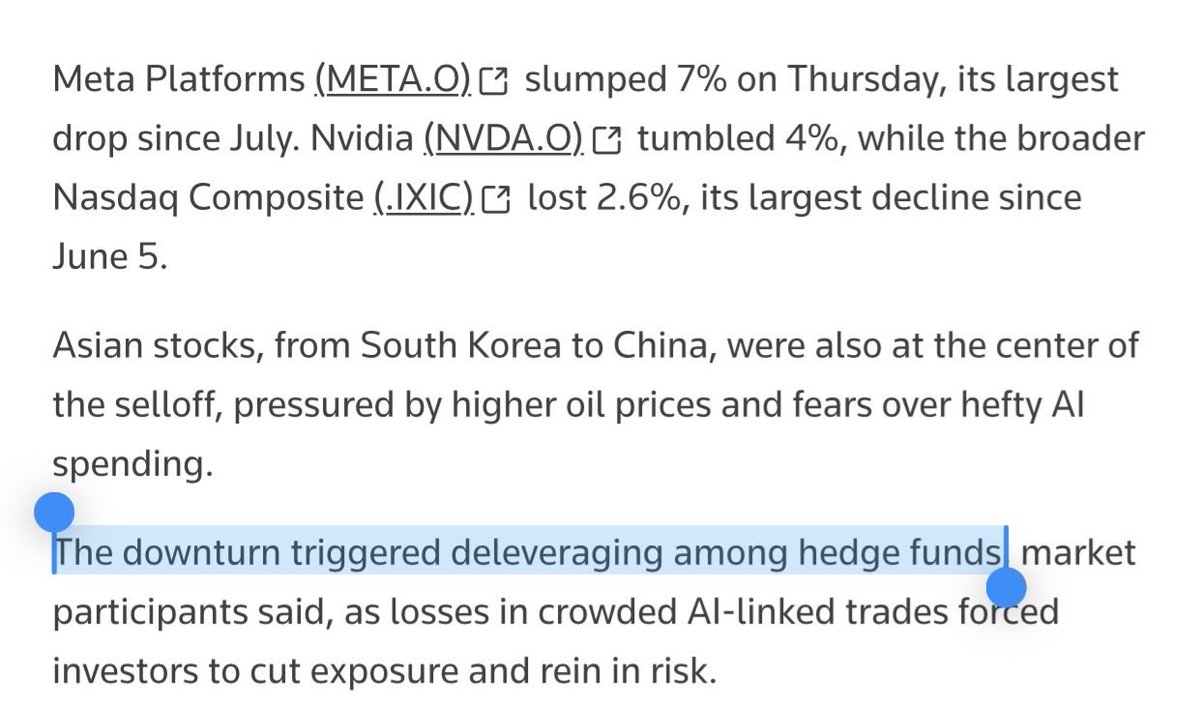
- October 22 marked the 1st time since the COVID crash that long/short, systematic, and multi-strategy hedge funds tracked by Goldman Sachs ALL lost more than 1% in a single day.
- Tech-focused hedge funds: down ~10% in October
- Asia-focused hedge funds: down ~9% in October
There’s separate interviews where Citadel/JP Morgan have been saying retail has been the ones buying the dip in semiconductor, neocloud, and memory stocks.
And the stocks bought by most retail were $NBIS, $SNDK, and $TSM.
Reuters stated this downturn triggered institutional deleveraging events among hedge funds.
Quite the divergence, I do think there’s been a ton of irrational selling now, hedge fund deleveraging seems to be a major contributor.
This post is going very viral. The #1 question I’m getting:
“What if competitors just flood the market with laser capacity and kill $SIVE and $AAOI?”
They can’t. Not in the timeframe that matters.
1. InP is the real constraint. Specialized epi, yields and process IP that don’t scale like silicon. Even $LITE and $COHR are still constrained.
2. Capacity takes years. $LITE already ramped 12x and is sold out through 2029, missing big chunks of demand. New capacity is 18–36+ months.
3. Qualification stickiness is extreme. Hyperscalers don’t switch laser suppliers casually once qualified.
4. The leader has no clear path. $LITE is fully booked, stopped taking orders, and lacks concrete expansion plans.
$AAOI is already ramping 1.6T + in-house lasers with demand exceeding supply through mid-2027.
$SIVE is the pure-play scaling to 100M+ CW DFB lasers/year.
Next-gen TPUs in 2028 are deeply optical. The overflow is real.
2027 can be a huge year for both. We are positioned.
NFA.
Been thinking about this comparison to the late 90s a lot lately.
Serenity just dropped the cleanest breakdown:
Memory names under 6x fwd P/E with multi-year LTAs. $MU alone has 26 strategic agreements covering >35% of revenue through 2030, $32B in customer prepayments, and more than 75% of next year’s output already committed. Some talks even extending past 2031.
Optical compressing hard despite 500-1000%+ growth. $LITE is effectively sold out through early 2029 on key products, with a large portion of next year’s demand still unmet.
$NVDA , $AVGO and $TSM are printing real cash while hyperscalers are guiding $700B + in Capex this year alone, most of it locked into the supply chain.
1999 was 100-600x+ on NOTHING while 2026 is EARNINGS + CAPACITY locked in.
Which of these are you adding on weakness?
$NVDA $MU $LITE $COHR $AAOI $AVGO $TSM $AMD
AI names are backed by actual earnings and contractual demand.
Memory names are under <3x fwd P/E, with LTAs extending 5-10 years from your richest companies in the world like $GOOGL.
Optical names are compressing to <10x fwd P/E despite 500-1000%+ growth next year
Back in the day companies like Cisco/Yahoo were in 100x-600x+ earnings range.
As I said, everything comes down to oil.
Today made it obvious. $SPCX and $META just posted some of the strongest earnings in their history, AI exploding and turning profitable; Meta raising FY26 capex to $135-145B and staying ultra-aggressive on the buildout.
Both confirming the AI infra supercycle is accelerating.
And $QQQ is still -1.6%.
Until the US starts thinking for himself instead of being a puppet, we’re cooked. Higher oil keeps inflation sticky, rates elevated, and financing tight.
That’s not a broken AI trade. That’s oil and rates overriding everything else. The setup hasn’t changed. Only the price has.
Stay disciplined and take advantage of dips.
NFA.
$META JUST EXPLODED AFTER HOURS 🚀
Our members saw how the Whales moves BEFORE:
🟢 Trump
🟢 Funds
🟢 Analysts
🟢 Lobbies
$BE tomorrow. $MSFT, $GOOGL, $AMZN next week.
Next print is tomorrow. Don’t miss it.👇🏽
$META $META $META
Everyone’s staring at the EPS miss.
They’re missing the real story.
Meta just printed $64.6B in revende, up 26% YoY and a clean beat. The $3.83 EPS (+265% YoY) only looks weak because of the one-time $9.9B AG charge. Take that out and it was roughly $7.40.
Ad pricing up 14% YoY, Family DAP at 3.64B, and Q4 guidance of $73-76 B. Muse and Muse Wonder are out too.
Stock is green after hours for a reason.
Who else is still long here? NFA
$IREN WILL MAKE MORE REVENUE IN 2028 THAN THEIR MARKET CAP TODAY AND TURN EPS POSITIVE
$SPCX just said there is a HUGE DEMAND FOR COMPUTE and they are pricing at 50 M/MW
This company is being valued like they are about to default but when you run the numbers:
contract pricing going up to 20-25 million per mw
1000 mw will likely be brought on during CY 2027 and 2028 in addition to the 300 mw brought on this year
Contracts with more hyper scalers and leading ai frontier labs like anthropic
almost the same amount of cash as debt
45-55% customer prepayments
ONLY A 2.4 PRICE TO BOOK RATIO vs competitors are 4.5 and 7 price to book ratio, the re rating will happen with execution of Horizon 2-4 delivery, "anthropic" deal announcement, and early 2027 deal announcements
So you're telling me $SPCX.
- Will be my car
- Will be my company's workforce via Grokbot
- Will be my internet
- Will be my cell phone provider
- Will be my Uber driver
- Will be my chef and cleaner with Optimus
Yeah it's not priced in guys...
$IREN $NVDA
Honestly this is one of the more BULLISH things IREN has done lately and the stock is still acting like nothing moves.
They just announced IREN Europe at NVIDIA GTC Berlin, put former Santander CEO Ángel Corcóstegui in charge of the board, and got the civil works license for the 300MW site in Badajoz. Power was already secured and they’re targeting first operations in 2028. It’s also set up for NVIDIA’s DSX platform.
That’s not another slide in a deck. That’s actual POWER and PERMITS in Europe, which is usually the hardest part. And with the Mirantis software layer they can actually handle the data residency and control stuff European customers care about.
The Real Madrid AI Cloud partnership a few days ago fits the same picture. They’re not just talking about Spain, they’re building there.
Market is still focused on financing noise and sector fear while the company keeps converting megawatts into real capacity.
IREN is advancing sovereign AI in Europe, bringing together its European data center capacity and managed cloud services for customers seeking more choice over where their AI workloads run and how their data and infrastructure are managed.
Announced today at NVIDIA GTC Berlin, IREN has established IREN Europe and appointed Ángel Corcóstegui as Chair of the newly established board of directors.
IREN also secured the civil works license for its planned 300MW campus in Badajoz, Spain. Following the completion of its acquisition of Mirantis, IREN’s software capabilities include workload isolation and operational controls that can help customers address data residency, security and governance requirements.
Read more: https://t.co/46hRxoIDu0
BULLISH $AAOI at these levels.
At ~$77 (down >65% from highs) this is a clear buy on the extreme fundamental/valuation divergence.
Demand for 800G/1.6T remains supply-constrained through mid-2027. Capacity is ramping hard: ~200k units/month now → 650k by YE26 → >930k by YE27 (>50% US).
Q3 guide $255-290 M (vs $192M Q2) with 800G expected ~5x sequential. $200M + 1.6T order already locked in.
SMCI just raised guidance massively to $18.5-19.5 B (from $14.5-15.5 B) — the procurement acceleration is real and visible.
You’re looking at a ~$6.5B company on a path to well over $1B this year with a much bigger ramp coming. The market is pricing in an AI capex collapse that the data doesn’t support yet.
Earnings Nov 5. High conviction setup.
What am I missing?
PS: very long $AAOI . NFA
Divergence between fundamental demand and valuations are now at extreme levels.
You're seeing accelerating procurement from $SMCI to $SPCX vs. collapsing equity prices on $AAOI to colo players.
After ERs, I think Oct 2026 will be seen as a DeepSeek / April tariff opportunity
$ANET $LITE $COHR $AAOI $AXTI
ARISTA'S ANDY BECHTOLSHEIM JUST PUT THE NEXT FULL OPTICS UPGRADE ON THE CALENDAR: TWICE THE SWITCH BANDWIDTH, SAME LANE COUNT, EVERY LANE MOVING UP TO 400G
Last month in Riga he said the industry can't build enough lasers for this year's modules. Now he's asking every one of those links to run twice as fast.
His Oct. 20 slides at PECC go from 204.8 Tbps on 1,024 lanes at 200G to a potential 409.6 Tbps on 1,024 lanes at 400G, with first silicon projected for 2028 and volume ramp in 2029, according to Converge Digest's report from the room.
He also lined up Arista's ($ANET) own XPO module, 25.6 Tbps with a 500 W design thermal envelope, against the NVIDIA and Cisco USFP at 6.4 Tbps and 100 W. In his measurements both connectors look like a credible path to 400G PAM4. XPO is Arista's design, so that part is his case for his own module.
The Riga numbers: OSFP demand this year of about 150 million units against just over 120 million shipping, because module makers can't get enough lasers. Lumentum ($LITE), Coherent ($COHR) and Applied Optoelectronics ($AAOI) make the indium phosphide lasers that go into these modules, and AXT ($AXTI) sells the InP substrates they're grown on. The roadmap he showed keeps the lane count at 1,024 and doubles what each lane carries, so I'd expect the laser makers to stay at the center of this through the 400G generation. Their 400G lasers should be ready in volume by the time that switch silicon shows up in 2028.