@deepakshenoy@athreya49 Wouldn’t the 85bps interest rate differential show up in lower dividends to govt. in coming years. Also, is it there a chance of the money leaking into the real world and causing asset inflation. Ruchir Sharma’s entire argument in his latest book is this
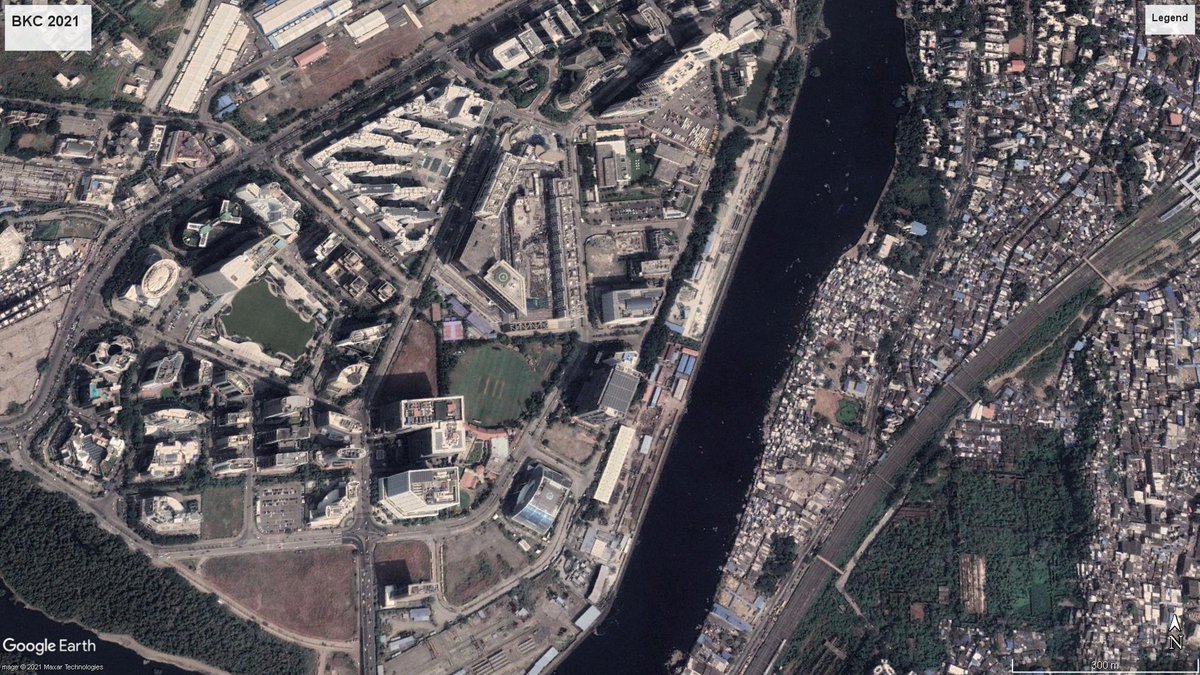
This is a real estate project masquerading as an "infrastructure project."
A project that should never have even been conceived at ₹1,722 crore - given how the State claims fund shortage for BEST buses.
Nevertheless this will be knock-out punch to Bandra as we know it.
Kind attention, folks. Prem's account has been hacked. It's not like him to buy a car like this one and brag about it here. He has asked me to post a warning here. Kindly RT for reach.
I used to love a web tool called StumbleUpon. Added a button to your browser that would take you to random blogs and websites. Found so much fascinating stuff that way, and it was the antithesis of today’s winner-take-most centralised web.
Attention @mybmc@ShelarAshish Building coming up on Carter Road -all the cement slurry being shoved into drains. In a few weeks when the monsoon comes we will suffer the flooding on roads.
Pathetic criminal conduct by this builder. Please take action
@Dev_Fadnavis 🙏🏼
#Mumbai
#WATCH | "Thank you for the gift", tweets Prime Minister of Italy, Giorgia Meloni
She says, "Prime Minister Modi brought as a gift, a very, very good toffee- Melody"
(Video Source: Giorgia Meloni/'X')
@veira_veira@FastandUp_India@TCSWorld10K Appreciate all the yeoman service @FastandUp_India does away from the limelight like the free hydration for runners on the EEH. These quiet gestures are why I reach for FnUp. Your commitment shows up in places not covered by cameras and branding 🧡
🚨 India is the only major market in Asia that hasn't bought rights to the 2026 World Cup.
FIFA's ask has dropped from $100m+ to ~$35m. The market is at ~$20-25m.
In between sits a $30m loss from 2022, vanished edtech/RMG money, major timezone issues, and a cramped calendar.
The Credit-Deposit Ratio—A Primer
Some of the recent commentary around the high banking Credit-Deposit (CD) ratio seems to miss a basic point: deposit growth is largely an outcome of credit creation, currency withdrawals, and foreign currency flows — not an independent driver.
Growth in overall banking deposits is a dependent variable, that is mathematically a result of:
• (+) Growth in banking loans
• (+) Net FX inflows
• (+) Growth in bank and RBI lending to the government (that is spent by the government)
• (-) Growth in currency in circulation
• (-) Retained profits & capital raises of banks and RBI
The Takeaways:
1. Loans funds themselves (systemwide): The banking system creates deposits when it extends credit. Counterintuitively, at a systemic level, a "lack of deposits" is not a structural constraint to lending. Individual banks, however, still have to compete for funding stability - more on that later.
2. Headline statutory reserves (SLR/ CRR) are not a constraint: With banks holding significantly excess SLR/ liquidity, the system is not constrained by headline SLR/ CRR statutory reserves.
3. The "Raising Deposits" Myth: When we exhort the banking system to "raise deposits," look at the above equation. What is actually under banking control? Ironically, the easiest way for the banking system to create more deposits is by lending more! Individual banks can compete for a larger slice of the deposit pie with better rates, but that doesn't grow the overall pie itself.
4. Mutual Funds are not a "Leakage" of bank deposits: When households invest in mutual funds, insurance, or pensions, the money remains within the banking system — it simply moves between accounts.
5. The real possible constraint for bankers: A shift from long-term deposits to short-term or demand deposits, particularly away from retail and into wholesale, can impact banking LCR (Liquidity Coverage Ratio) and NSFR (Net Stable Funding Ratio). This can be the real constraint to banking business. This is a nuance of duration and stability, not a "loss of deposits”, and has to be articulated and debated as such. If all this boils down to banks needing more long-term deposits, especially from households, the discussion points could well be around fair interest rates (is there financial repression?), banking efficiency, and the need for a level playing field across household savings into fixed income and equity.
In the current context, net FX outflows and relatively high growth in currency in circulation are the primary reasons deposit growth is trailing, leading to the optically high CD ratio. But the real policy discussion should focus on liquidity drivers and funding stability, not the headline ratio alone.
#Banking #Macroeconomics #RBI #MonetaryPolicy #Finance #IndiaEconomy
How did Karnataka, Kerala gain the most and MP, UP lose in the new Finance Commission formula. @Roshanjnu and I have a long answer to the question. This first part published y'day explains the balancing act the 16th FC needed to pull off 1/2 https://t.co/Q1KOM8IGVr
This is still not resolved. This is so incredibly frustrating. I can’t believe that there is no sense of accountability. Can they just get away with anything #eurekaforbes@EurekaForbes
@EurekaForbes Bought an Aquaguard in Nov after an Eureka Forbes tech visited, measured my space & recommended the model.
Delivered. Installer says: doesn’t fit.
2 months. Purifier unused. Endless calls. Same excuse: “emailed corporate.”
Absolute incompetence #eurekaforbes
Update: Company DM’d, took all details, claimed an agent was “assigned”.
Reality: No agent. No call. No action.
This is not incompetence. This is contempt for customers.
A complete disgrace of a company. I hope none had to go through this ordeal. Never ever think of buying