@kirawontmiss Fuck off with your tacky promos. Fake money supplied from the company, none of it is genuine. And you’re probably getting paid just $50 for this tweet
Grade A loser
@Marketmakemkc@aleabitoreddit It’s actually something he has address fairly recently. Sive announced fab expansion increase to 100m laser capacity per year. Sive CEO said they’re focusing on 2:1 ratio of foundry to fab capacity
Which means 200m laser capacity through foundries, 100m through fab. 300m total
Mizuho on opticals:
We see CW laser capacity ramping sharply from ~83M units in 2025 to ~427M by 2029E (Ex-7), driven by SiPho pluggables at 1.6T/3.2T and the initial NPO/CPO transition into 2027-2029E as we see yields improving.
We see $COHR profitability lagging as we believe it relies on external lasers for it's leading-edge products (also sourced from LITE) and its business model remains more transceiver-heavy which is lower-margin vs LITE, which we see as more laser-oriented. On margins, LITE continues to ramp GMs sharply from low-30% in early 2024 to the low-50% range in 2026-2028E, while COHR rises more gradually to only the low-40s%, resulting in a 10-11ppt gap.
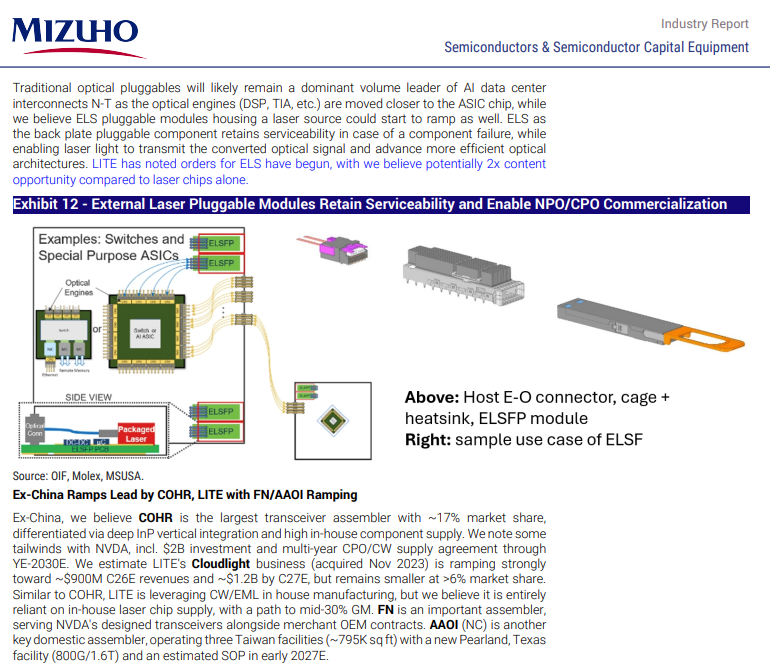
We believe ELS pluggable modules housing a laser source could start to ramp as well. ELS as the back plate pluggable component retains serviceability in case of a component failure, while enabling laser light to transmit the converted optical signal and advance more efficient optical architectures. $LITE has noted orders for ELS have begun, with we believe potentially 2x content opportunity compared to laser chips alone.
Ex-China, we believe COHR is the largest transceiver assembler with ~17% market share, differentiated via deep InP vertical integration and high in-house component supply. We note some tailwinds with $NVDA, incl. $2B investment and multi-year CPO/CW supply agreement through YE-2030E. We estimate LITE's Cloudlight business (acquired Nov 2023) is ramping strongly toward ~$900M C26E revenues and ~$1.2B by C27E, but remains smaller at >6% market share. Similar to COHR, LITE is leveraging CW/EML in house manufacturing, but we believe it is entirely reliant on in-house laser chip supply, with a path to mid-30% GM. FN is an important assembler, serving NVDA's designed transceivers alongside merchant OEM contracts. $AAOI (NC) is another key domestic assembler, operating three Taiwan facilities (~795K sq ft) with a new Pearland, Texas facility (800G/1.6T) and an estimated SOP in early 2027E.
@revoAIution It appears that swedish investors and institutions have a deep underlying problem with valuing companies in the future and put a very large emphasis on the financial numbers as of today. Baffling
@ssrof1970@revoAIution Well I think you’ve answered your own question on that last one there. They will get orders, it’s inevitable. Every optics CEO has stated that lasers are supply constrained. Whatever gets built will be sold
@2147mill So irresponsible, for the sake of £30 - high risk low reward. If you’re going to go down this route, then show some transparency and acknowledge the losses
@BananaPrinciple Capacity is crucial yes, hence why they’ve secured further capacity via two foundries…
It’s sensible management. Why would they spend a majority of their raised capital on expansion? It makes no sense, they may use funds for M&A
@BananaPrinciple Huh? Maybe so they don’t burn cash. 100m production + 200m via foundries is huge laser production capacity. They’re a 1b company, not a giant like $COHR & $LITE.