

Top Tweets for #SEDEMAc

📊 2026 IPO report card: ESDS +181%, Indo-MIM +165%, Shadowfax +133% (it listed below issue). At the bottom: Aastha Spintex −81%, Turtlemint −61%, Annu Projects −59%. Listing day isn’t the final verdict. Not investment advice.
#IPO #IPO2026 #ESDS #IndoMIM #Shadowfax #SEDEMAC #TonboImaging #Multibagger #StockMarketIndia #Nifty


10 Small Cap Stocks that witnessed an increase in FII holding in Q2 FY27
#fii #smallcap #skipper #sedemac #tfc #diamondpower #cyientdlm #morepen #bodal #modison #birlacable #financeamber #amber


#SEDEMAC
Most were busy extrapolating the results and posting reactions.
Meanwhile, me, who guessed the PEAD right and chose to stay SILENT. 🙂
#QuestioningConvictionMuscle
Cheat code
When AI scores management sentiment as cautious or neutral,
but the underlying business model remain strong...
As a contrarian investor, you know what to do. 😉

#SEDEMAC
SEDEMAC’s growth is coming with a more demanding cash profile. Q2 revenue rose 𝟯𝟵.𝟴% year on year to ₹𝟰𝟬𝟬.𝟲 𝗰𝗿𝗼𝗿𝗲, but EBITDA margin fell to 𝟭𝟵.𝟬% from 𝟮𝟭.𝟳%, while H1 operating cash flow turned to an outflow of ₹𝟮𝟬.𝟰 𝗰𝗿𝗼𝗿𝗲. The quarter shows strong mobility revenue growth and programs moving through ramp-up; it also shows how much working capital, pricing execution and new capacity now matter to the quality of that growth. The September 2025 comparative figures were board-approved but were not audited or subjected to limited review.
1) Mobility is doing the heavy lifting. Q2 mobility revenue grew 𝟱𝟮.𝟲% to ₹𝟯𝟲𝟲.𝟰 𝗰𝗿𝗼𝗿𝗲, while Industrial revenue fell 𝟮𝟲.𝟮% to ₹𝟯𝟰.𝟯 𝗰𝗿𝗼𝗿𝗲. Mobility was 𝟵𝟭.𝟭% of H1 sales. The segment mix makes the growth story clear, but it also leaves the consolidated result more dependent on mobility execution while the smaller Industrial business remains weak. Management linked softer North American genset EFI demand to a weaker hurricane season and said it was seeing recovery signs; the accounts do not quantify how much of Industrial’s decline that explains.
The company’s control-intensive ECU count reached 𝟰.𝟲𝟬 𝗺𝗶𝗹𝗹𝗶𝗼𝗻 on a trailing-twelve-month basis, up 𝟰𝟰.𝟮%, alongside TTM revenue growth of 𝟰𝟳.𝟴%. Management says this subset of ECU volumes correlates fairly strongly with revenue, but it also sells other ECU types and has not provided a price or mix bridge. The figures are consistent with volume-led expansion, not a complete explanation of it. Sequentially, Q2 revenue was 𝟮𝟵.𝟯% above Q1, while the EBITDA proxy rose 𝟮𝟲.𝟵% and margin eased from 𝟭𝟵.𝟰% to 𝟭𝟵.𝟬%; that comparison is not seasonally adjusted.
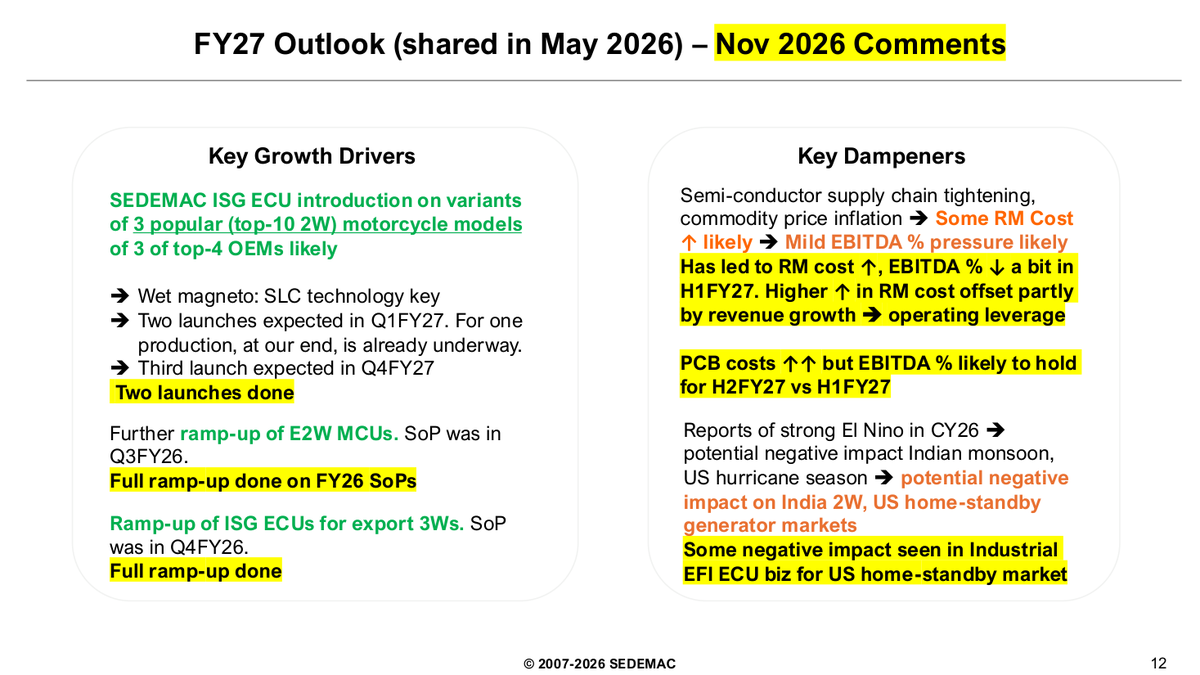
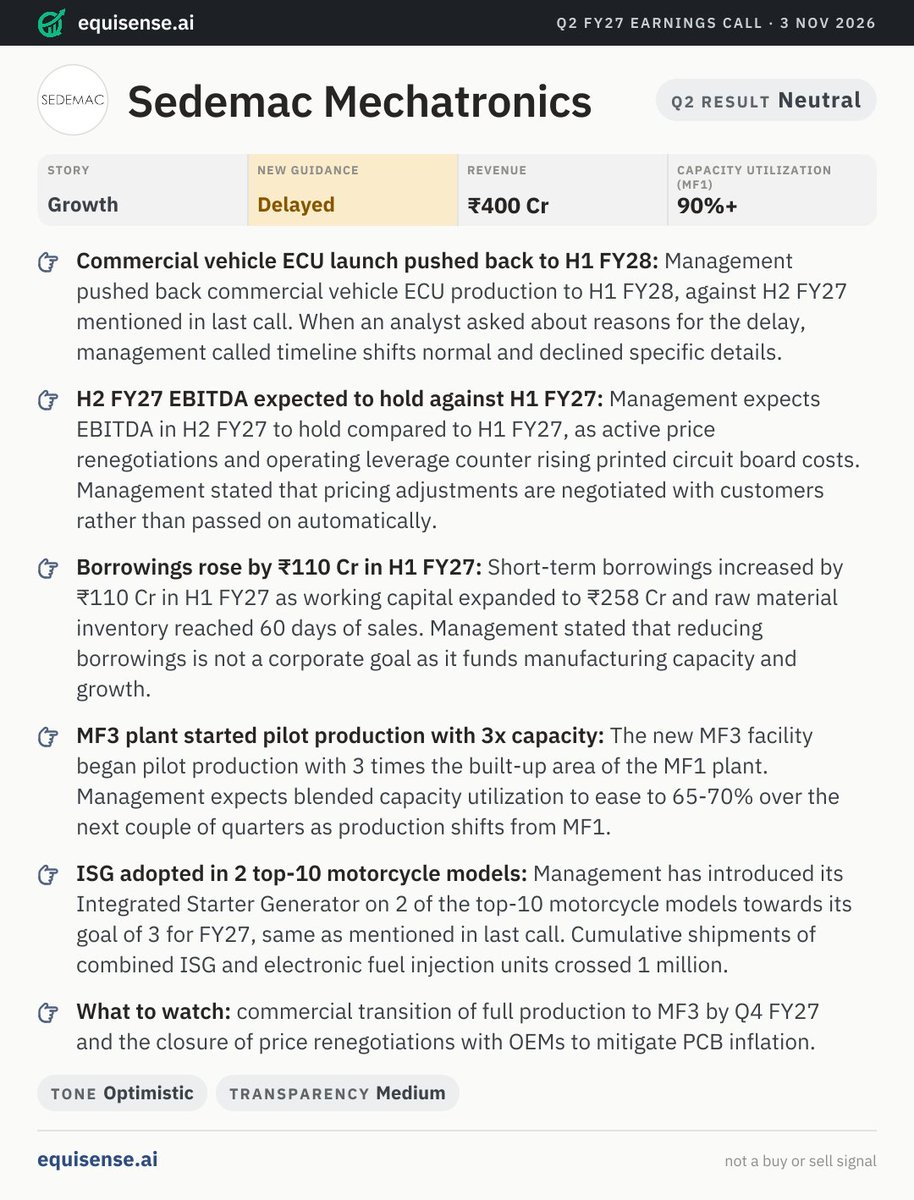
2) Launch execution is progressing, while the next layer remains conditional. Management says the export ICE three-wheeler ISG and FY26-launched electric two-wheeler MCU are fully ramped. Two of the three planned top-ten motorcycle launches are also fully ramped; the third remains expected in Q4 FY27. ISG plus EFI shipments have exceeded one million since October 2024, but management declined to give a current run-rate, so the past shipment pace is not a forecast.
A European two/three-wheeler OEM program has been won, with start of production expected in H1 FY28. Commercial vehicle controllers and a power-tool MCU broaden the pipeline, but should not yet be counted as growth drivers. The CV aftertreatment controller’s expected start moved from H2 FY27 to H1 FY28, and management did not disclose why. Power tools are earlier still: management says both success and eventual scale are unknown. These programs offer possible future growth, not current revenue support.
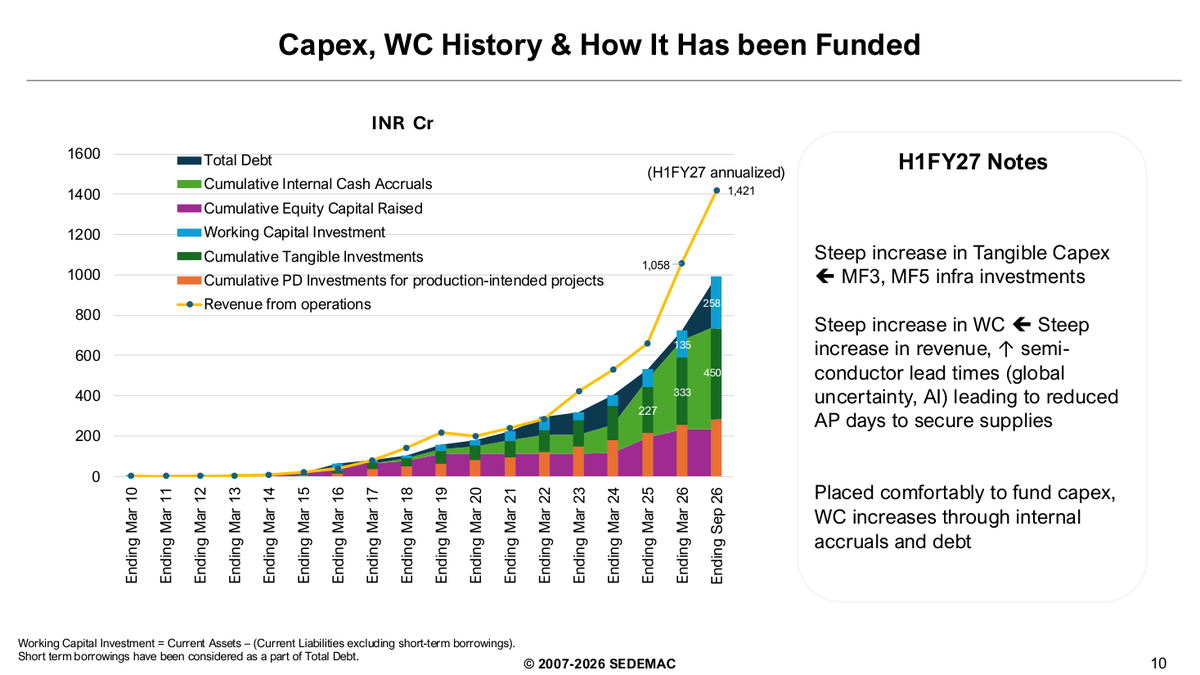
3) Capacity is arriving before its economics are visible. MF3, a 120,000-square-foot facility around three times MF1’s size, has begun pilot production; it is not yet in full production. Management estimates that MF3 could be 𝟲𝟱–𝟳𝟬% utilized if fully populated at today’s revenue, versus 𝟵𝟬%+ utilization at MF1, and expects a substantial shift by FY27 end while describing the timing as flexible. That is a scenario, not achieved utilization. TTM ROCE has meanwhile eased to 𝟯𝟰% from 𝟯𝟴%; management attributes the decline to investment ahead of the plant becoming operational. The return case depends on filling the capacity and converting it into earnings.
4) The margin and cash questions are now connected. H1 EBITDA margin was 𝟭𝟵.𝟮%, against 𝟮𝟭.𝟰% a year earlier. Management attributed the pressure mainly to raw-material inflation, partly offset by operating leverage, and said PCB costs would add pressure in H2. Its prepared remarks say H2 EBITDA is expected to hold versus H1 without specifying whether that means amount or margin; the same-day investor presentation says EBITDA percentage is likely to hold. These are management expectations, not guarantees, and the difference in wording leaves the spoken metric ambiguous. There is no automatic raw-material pass-through: the CFO said price changes are negotiated, with discussions ongoing. Price recovery therefore remains an execution variable, not a built-in offset.
Working capital, by the company’s definition, rose from ₹𝟭𝟯𝟱 𝗰𝗿𝗼𝗿𝗲 in March to ₹𝟮𝟱𝟴 𝗰𝗿𝗼𝗿𝗲 in September. That is about 𝟭𝟲.𝟭% of annualized Q2 revenue, or 𝟭𝟴.𝟮% using annualized H1 revenue, so the ratio depends on the denominator. CFO Shashi Suryanarayanan said the increase primarily reflected revenue growth and did not expect the situation to change substantially. He described the ratios as not very different, but his rounded comparison of ₹𝟮𝟱𝟬 𝗰𝗿𝗼𝗿𝗲 against annualized Q2 revenue of ₹𝟭,𝟲𝟬𝟬 𝗰𝗿𝗼𝗿𝗲 and ₹𝟭𝟯𝟱 𝗰𝗿𝗼𝗿𝗲 against Q4 revenue of ₹𝟮𝟴𝟳 𝗰𝗿𝗼𝗿𝗲 annualized gives about 𝟭𝟱.𝟲% versus 𝟭𝟭.𝟴%. That arithmetic does not support the description; management’s explanation and outlook remain separate from the balance-sheet calculation. Earlier, management also cited longer semiconductor lead times, lower payable days and advance buying, and estimated inventory cover at roughly 60 days of sales. The balance sheet confirms the build, but not how quickly inventory and receivables will convert back to cash.
H1 operating cash flow was negative ₹𝟮𝟬.𝟰 𝗰𝗿𝗼𝗿𝗲, versus positive ₹𝟭𝟮𝟬.𝟳 𝗰𝗿𝗼𝗿𝗲 a year earlier, with inventory and receivables absorbing cash. Borrowings increased to ₹𝟮𝟰𝟱.𝟲 𝗰𝗿𝗼𝗿𝗲 from ₹𝟱𝟬.𝟲 𝗰𝗿𝗼𝗿𝗲 at March, while cash and other bank balances fell to ₹𝟭𝟬.𝟵 𝗰𝗿𝗼𝗿𝗲 from ₹𝟲𝟰.𝟰 𝗰𝗿𝗼𝗿𝗲. Borrowings less those balances are ₹𝟮𝟯𝟰.𝟳 𝗰𝗿𝗼𝗿𝗲, a simple proxy that excludes ₹𝟭𝟬𝟲.𝟱 𝗰𝗿𝗼𝗿𝗲 of lease liabilities and is not company-defined net debt. Management said borrowing supports growth and facility readiness, and that reducing debt in isolation is not its objective. It also expects H2 capex to be lower than H1, mainly because MF3 capex should decline as the plant nears readiness; it gave no exact estimate. This does not by itself establish lower borrowing or the overall cash-flow outcome. The cash-flow and balance-sheet movements make conversion and returns important to follow, without by themselves establishing financial distress.
The near-term test is whether negotiated pricing and cash recovery keep pace with input costs and capacity investment. If the filed H2 margin expectation is delivered while working capital begins to convert and MF3 ramps, growth could look more self-funding; if not, strong sales may continue to require rising financing. The launch milestones show execution; the question is whether pricing, cash conversion and MF3 utilization can turn that execution into earnings and returns before financing needs keep rising.
Not a recommendation. Just tracking.


HSBC on #SEDEMAC Mechatronics | BUY | TP: ₹4,000
Upside potential 25% 💥
Key takeaways -
✅ HSBC believes the premium valuation is justified, with its ₹4,000 target price implying 64x FY28E P/E.
✅ Q2 revenue was in-line with estimates, while EBITDA margins missed due to higher semiconductor and PCB costs.
✅ Management expects margins in 2H to remain broadly stable versus 1H.
✅ Rising penetration of ISG and EFI ECUs will support ASP expansion and revenue growth.
✅ New business wins in ISG ECU and magneto kits provide additional growth levers.
Increasing ECU penetration, technology-led product upgrades and rising content per vehicle could drive the next leg of SEDEMAC's growth.
#SEDEMAC #AutoAncillary #Electronics #HSBC
#SEDEMAC Technologies: Strong growth, improving profitability & rising ECU volumes! 💥
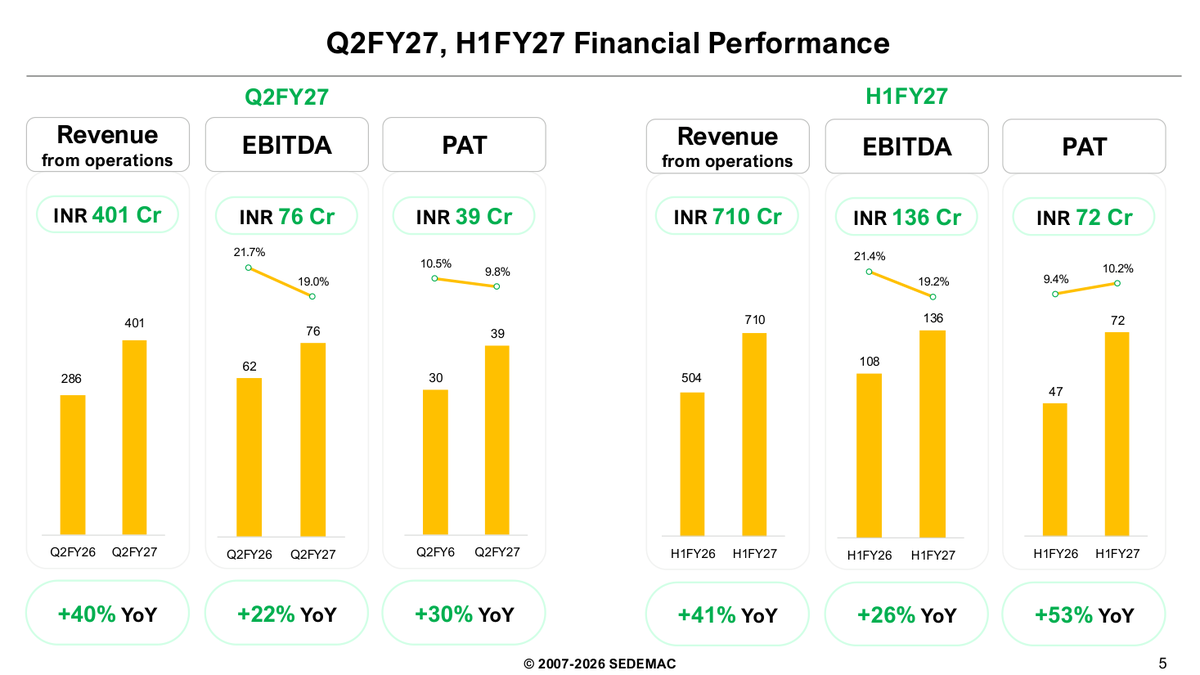
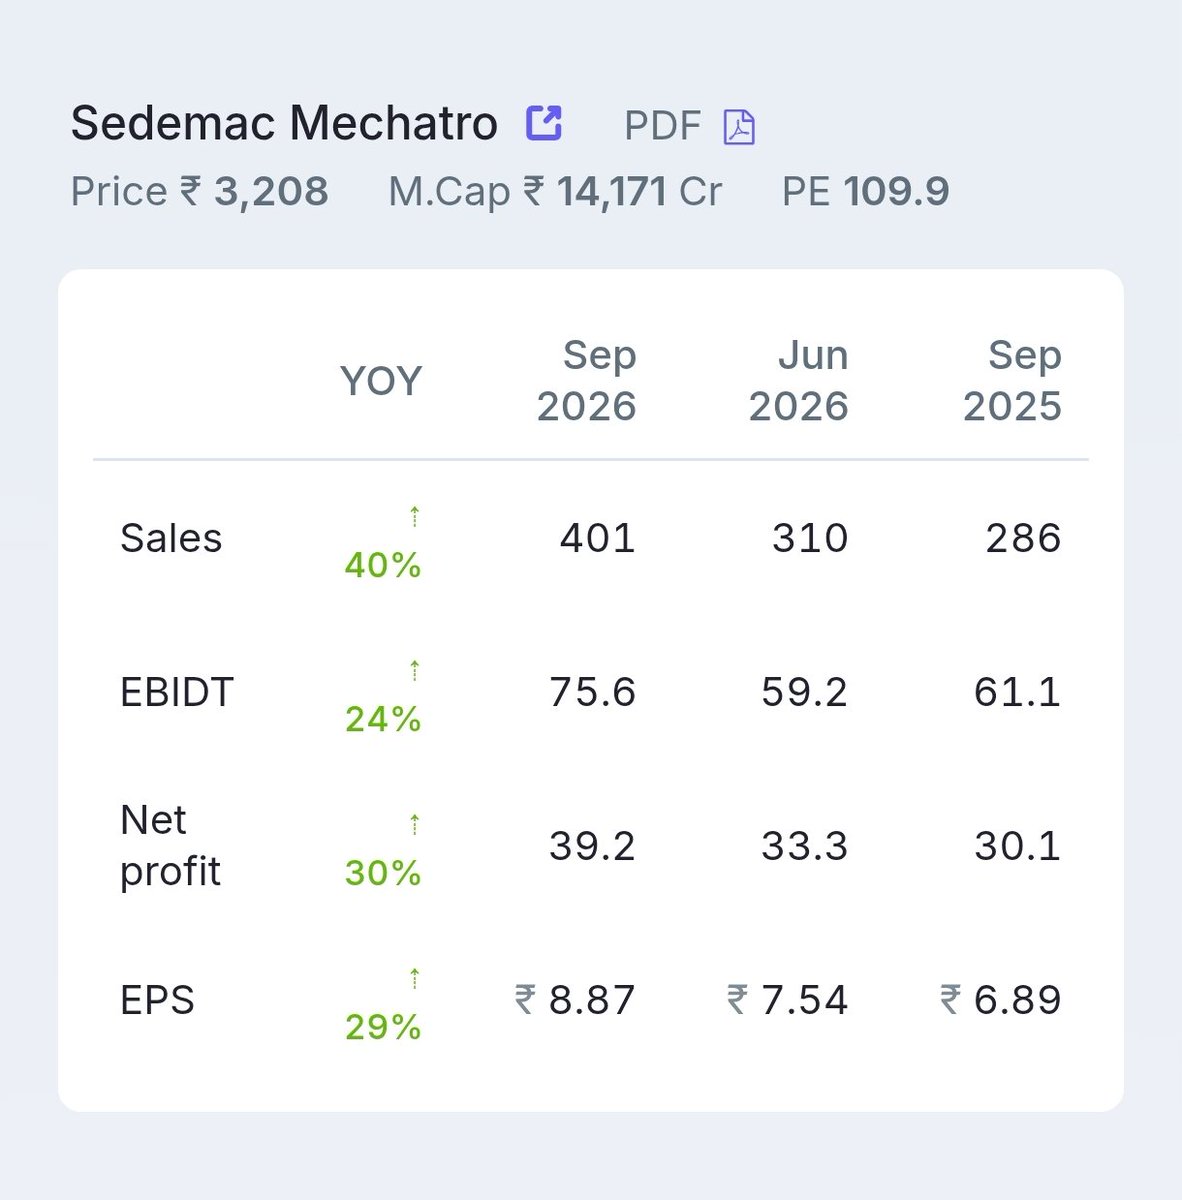
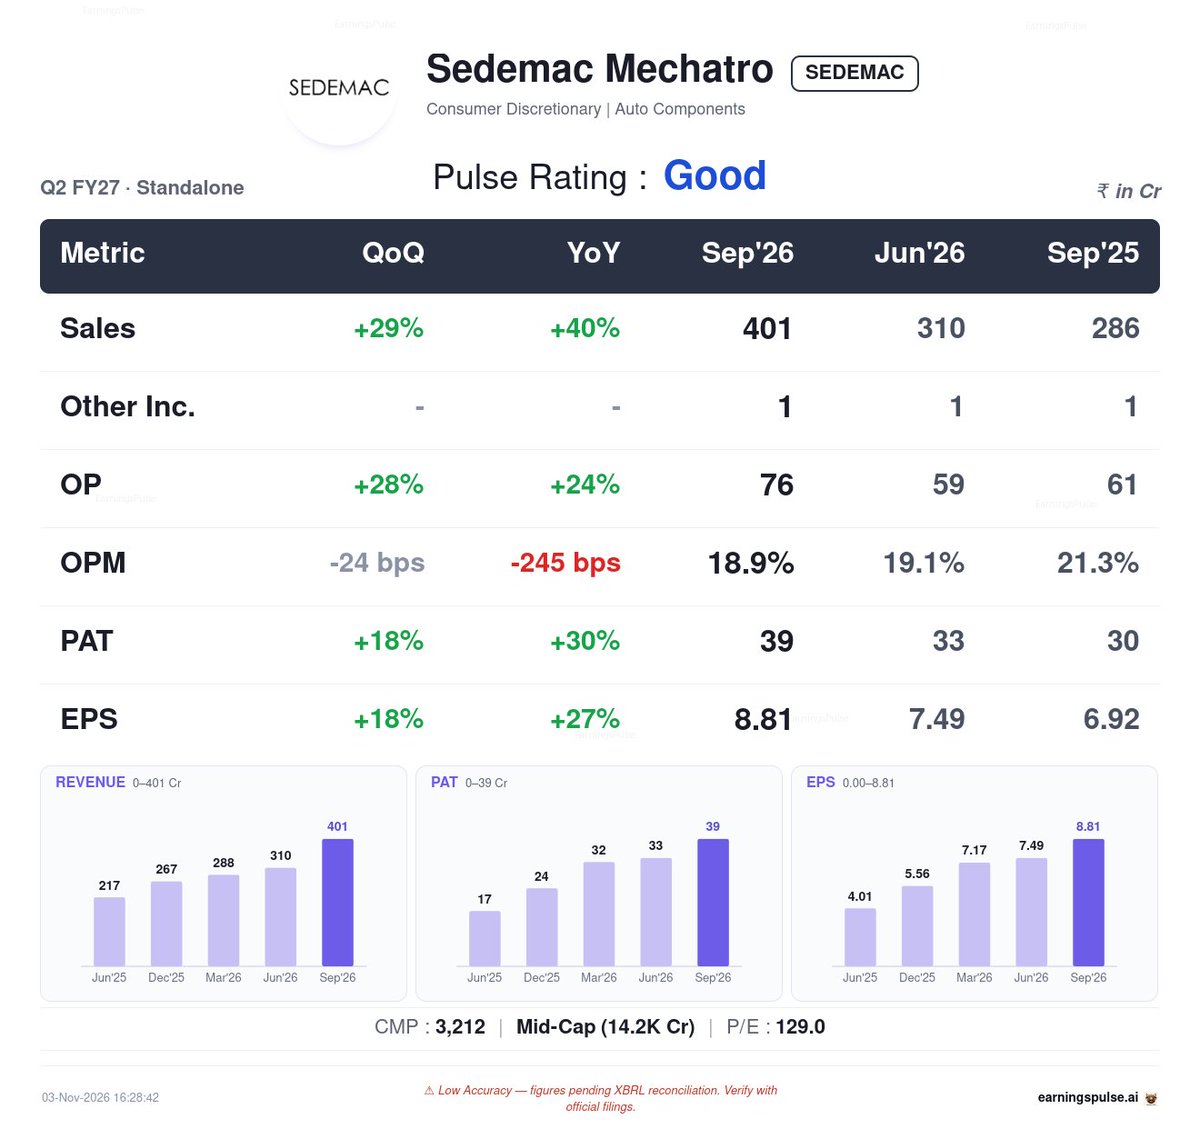
✅ Q2FY27 Revenue: ₹401 Cr | +40% YoY 💥
✅ EBITDA: ₹76 Cr | +22% YoY
✅ PAT: ₹39 Cr | +30% YoY
H1FY27:
✅ Revenue: ₹710 Cr | +41% YoY
✅ EBITDA: ₹136 Cr | +26% YoY
✅ PAT: ₹72 Cr | +53% YoY
TTM Performance:
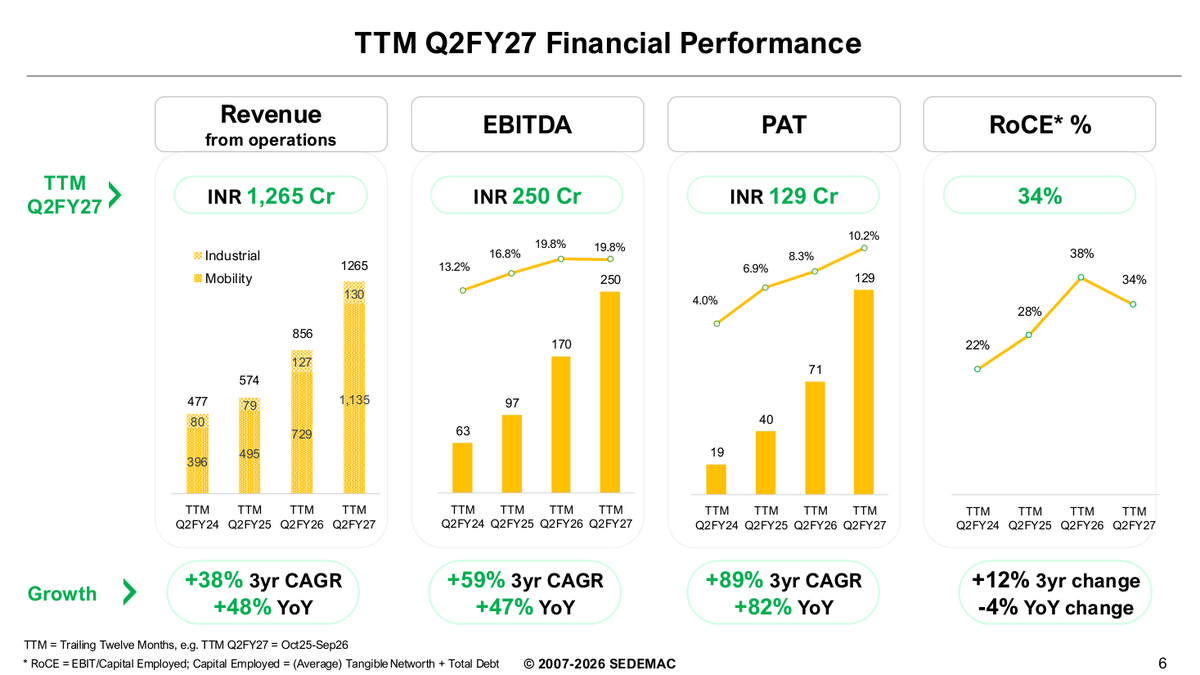
✅ Revenue: ₹1,265 Cr | +48% YoY
✅ EBITDA: ₹250 Cr | +47% YoY
✅ PAT: ₹129 Cr | +82% YoY
✅ EBITDA Margin: 19.8%
✅ PAT Margin: 10.2%
✅ ROCE: 34% 💥
The real story is the growth runway:
✅ Control-intensive ECU sales crossed 14 million cumulatively.
✅ TTM ECU volumes reached 45.97 lakh units vs 31.87 lakh in FY26 — strong volume expansion.
✅ Revenue, EBITDA and PAT delivered 3-year CAGRs of 38%, 59% and 89%, respectively.
✅ ISG ECU for export ICE 3-wheelers has fully ramped up, with 1 million units shipped in approximately two years.
✅ ISG + EFI ECU products are witnessing strong ramp-up, with a European 2/3-wheeler OEM business win.
✅ New business opportunity: ISG ECU + Magneto Kit, with SOP expected in H1FY28.
SEDEMAC is building a differentiated position in mission-critical electronic control systems for mobility and industrial applications.
#SEDEMAC #ElectronicsManufacturing #EV #Automotive #Investing

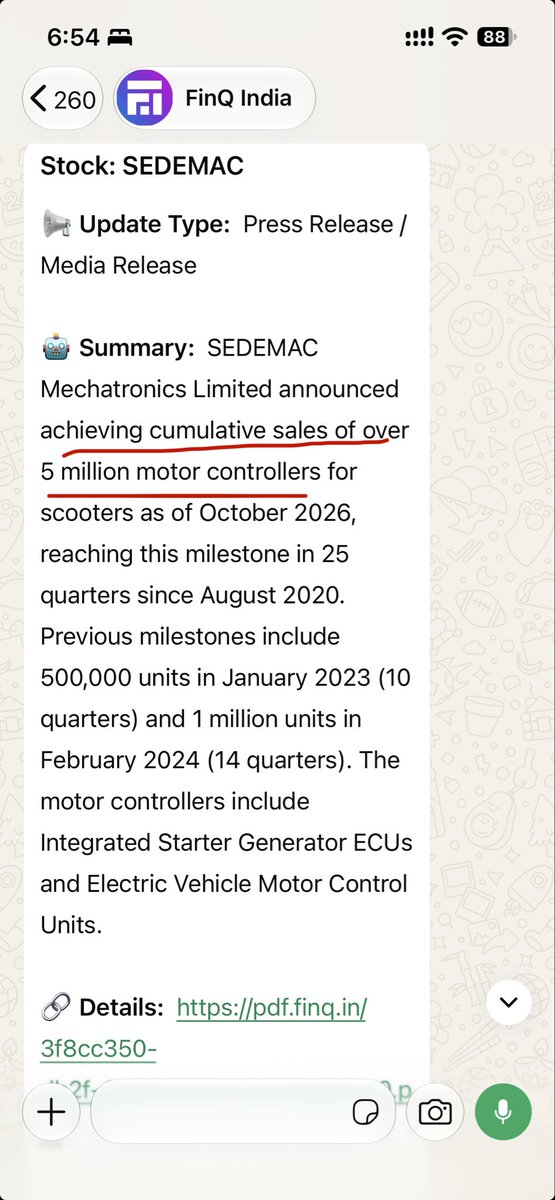
#SEDEMAC Achieved cumulative sales over 5 million motor controller
Get stock alerts on WhatsApp 👉 https://t.co/SEtJkLoEDp


Sedemac concall is the best concall to listen the management guidance is simple, clean and ofcourse professor shashi bashing analysts for asking the obvious questions😂!
PS: The company is founded by IIT bombay students along with IIT Bombay professor shashi!
#SEDEMAc
#SEDEMAC crossed 5 million cumulative scooter motor controllers sold in October 2026.

Good #Q2FY27 updates:
1. Northern Arc Capital #NorthArc
2. Sedemac Mechatronics #Sedemac
3. Manipal Payment and Identity Solutions #MPIManipal
4. Awfis Space Solutions #Awfis
5. Sandur Manganese #Sandur
6. Anthem Biosciences #anthembio
7. JG Chemicals #JGChem

🎙️ SEDEMAC Mechatronics (SEDEMAC) call was streaming live on EquiSense, it just ended. Here is the decode ⬇️
#SEDEMAC #EarningsCall
#SEDEMAC Technologies: Strong growth, improving profitability & rising ECU volumes! 💥
✅ Q2FY27 Revenue: ₹401 Cr | +40% YoY 💥
✅ EBITDA: ₹76 Cr | +22% YoY
✅ PAT: ₹39 Cr | +30% YoY
H1FY27:
✅ Revenue: ₹710 Cr | +41% YoY
✅ EBITDA: ₹136 Cr | +26% YoY
✅ PAT: ₹72 Cr | +53% YoY
TTM Performance:
✅ Revenue: ₹1,265 Cr | +48% YoY
✅ EBITDA: ₹250 Cr | +47% YoY
✅ PAT: ₹129 Cr | +82% YoY
✅ EBITDA Margin: 19.8%
✅ PAT Margin: 10.2%
✅ ROCE: 34% 💥
The real story is the growth runway:
✅ Control-intensive ECU sales crossed 14 million cumulatively.
✅ TTM ECU volumes reached 45.97 lakh units vs 31.87 lakh in FY26 — strong volume expansion.
✅ Revenue, EBITDA and PAT delivered 3-year CAGRs of 38%, 59% and 89%, respectively.
✅ ISG ECU for export ICE 3-wheelers has fully ramped up, with 1 million units shipped in approximately two years.
✅ ISG + EFI ECU products are witnessing strong ramp-up, with a European 2/3-wheeler OEM business win.
✅ New business opportunity: ISG ECU + Magneto Kit, with SOP expected in H1FY28.
SEDEMAC is building a differentiated position in mission-critical electronic control systems for mobility and industrial applications.
#SEDEMAC #ElectronicsManufacturing #EV #Automotive #Investing
#SEDEMAC — Q2 updates -
This is not just “VOLUME GROWTH.”
LOOK AT THE ACCELERATION.
Q2 FY27 control-intensive ECUs/controllers sold: 1.45 Mn units vs 1.06 Mn in Q2 FY26
➡️ +37.5% YoY
But TTM is even more interesting:
TTM Sep’26: 4.60 Mn
TTM Sep’25: 3.19 Mn
➡️ +44.2% YoY
And then comes a milestone worth watching:
1 MILLION cumulative ISG + EFI ECUs
Started: Oct’24
250K: Aug’25 → 10 months
500K: Jan’26 → 15 months
1M: Sep’26 → 23 months
So the High valuation.

SEDEMAC Mechatronics Q2: Profit rises 18%, revenue up 29% sequentially
@Navneetvats0009
https://t.co/mIUxJKWM4Q
#SEDEMAC #Q2Results #Earnings #AutoComponents #StockMarket


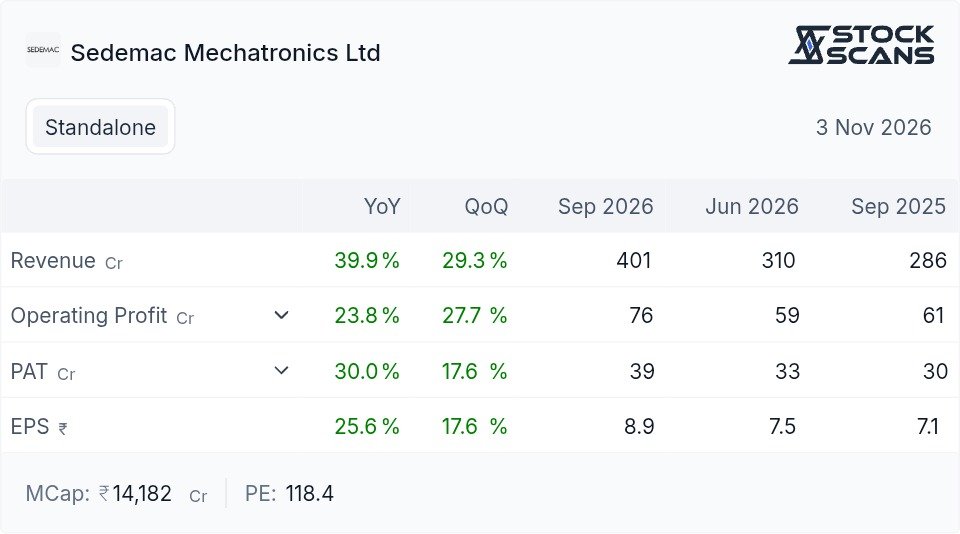
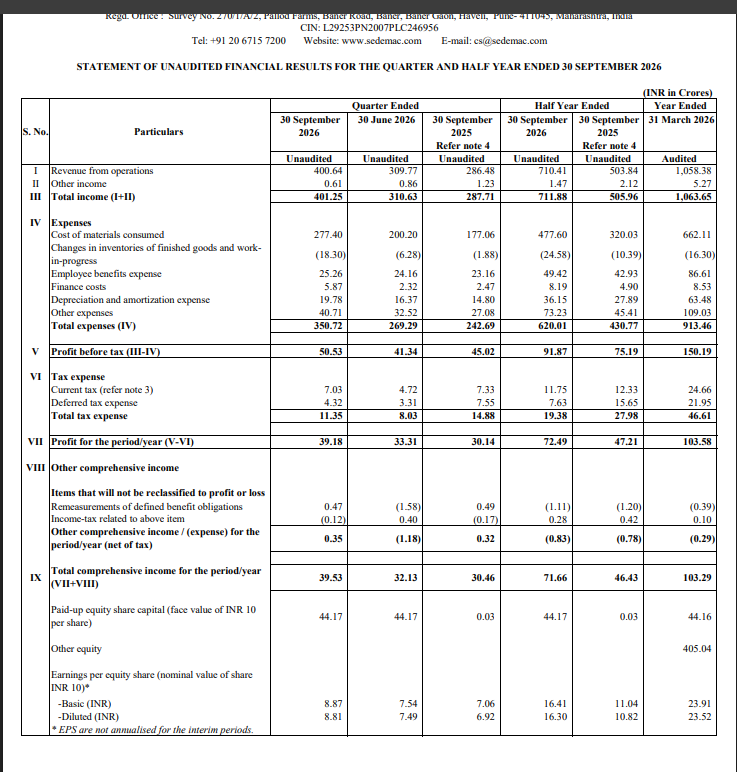
Sedemac Mechatronics — Q2FY27 Results 🔔
#Q2Results #Q2FY27 #Sedemac
Revenue ₹400.64 Cr vs ₹286.48 Cr
(+39.85% YoY┃+29.33% QoQ)
EBITDA ₹75.57 Cr vs ₹61.06 Cr
(+23.76% YoY┃+27.72% QoQ)
EBITDA Margin 18.86% vs 21.31% YoY & 19.10% QoQ
PBT ₹50.53 Cr vs ₹45.02 Cr
(+12.24% YoY┃+22.23% QoQ)
PAT ₹39.18 Cr vs ₹30.14 Cr
(+29.99% YoY┃+17.62% QoQ)
Other Income ₹0.61 Cr vs ₹1.23 Cr YoY & ₹0.86 Cr QoQ



Last Seen Hashtags on Sotwe
Ennisdelmar #JackTwist
Seen from Sweden
ifşa sarhoş
Seen from Turkey
hijabi video
Seen from Belgium
男主
Seen from Japan
موجب_اجنبي
Seen from Saudi Arabia
madreinfiel
Seen from Argentina
HONGEUNCHAE
Seen from France
omeglegame()
Seen from United States
realmomson
Seen from Turkey
mgai
Seen from Greece
Most Popular Users

Elon Musk 
@elonmusk
240.8M followers

Barack Obama
@barackobama
118.7M followers

Cristiano Ronaldo
@cristiano
114.5M followers

Donald J. Trump
@realdonaldtrump
111.9M followers

Narendra Modi
@narendramodi
107M followers

Rihanna
@rihanna
98.7M followers

NASA
@nasa
92.2M followers

Justin Bieber
@justinbieber
91.8M followers

KATY PERRY
@katyperry
90M followers

Taylor Swift
@taylorswift13
84M followers

Lady Gaga
@ladygaga
75.5M followers

Virat Kohli
@imvkohli
73.4M followers

Kim Kardashian
@kimkardashian
70.8M followers

YouTube
@youtube
68.7M followers

Neymar Jr
@neymarjr
66.4M followers

Bill Gates
@billgates
65.2M followers

Selena Gomez
@selenagomez
63.1M followers

The Ellen Show
@theellenshow
62.2M followers

CNN
@cnn
61.7M followers

X
@x
60.6M followers