$TOAI followed my chart prediction from last week almost perfectly 💪. Smashing through trendline resistance and hitting 1.4m market cap today ✅.
Traceon AI $TOAI is one of the very few projects that has been performing well this week. It's up 2x from my quoted post 6 days ago🚀, and up 6x from when I first called the project 27 days ago😎.
The chart might consolidate a little now and build support 800k - 1m market cap. Then see continuation higher. Accumulate on the dips is the best play📈.
@Traceonai_eth recently announced their next product PhishTrace is coming. PhishTrace is TraceonAI’s decentralized threat intelligence engine. It’s built to stop phishing at the domain level before fake sites even go live.👀
Site https://t.co/isHWJ0wYXT
TG https://t.co/9msAq0ktTH
X https://t.co/VQJmUDyljU
Docs https://t.co/3DqXcX7axX
CA: 0xed291c4ea45be02481e7f8359caada27d5909f42
This is it bros…we found the missing peice that confirms @altcoinist onchain identity solutions theory mapped out in exquisite detail below.
This is a snippet from an interview with @mickymalka from 4 years ago. FOUR WHOLE DAMN YEARS AGO!!!! He had been thinking this up for awhile back then, and now add four years on top of that.
$tibbir is such a slow cook, that this is going to absolutely blow all of our minds when it finally gets released…
From idea → prototype → production ready aApp in <1 day.
Instantly available for purchase by every crypto community on Telegram in 2 clicks. It doesn't get easier than that.
The time from idea → generating revenue has never been quicker.
🚀 New Listing 🚀 #XTListing@avm_codes
📢 #XT will list $AVM (Agents Virtual Machine) in the Innovation Zone.
✅ Deposit: 07:00 on June 18, 2025 (UTC)
✅ Trading: 07:00 on June 18, 2025 (UTC)
✅ Withdrawal: 07:00 on June 19, 2025 (UTC)
Trade NOW ⤵️
https://t.co/M0KCnNnkHw
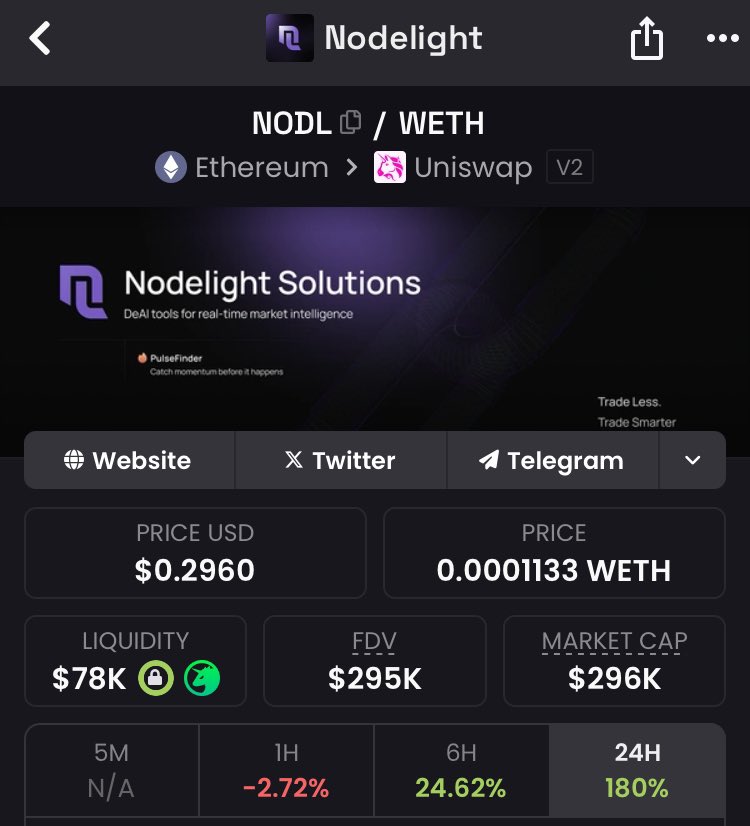
$NODL x $PRIVIX
@Node_Light x @privixtoken Official Partnership Announcement
Nodelight announces their integration of the Privix Nexar API as an official white-label partner.
Through this collaboration, NodeLight now offers next-level privacy swap functionality built directly into our platform. This means faster, safer, and more decentralized access to swapping tools, all while protecting user privacy at every step.
What this means for users:
• Integrated privacy-first swaps
• Seamless and secure user experience
• Enhanced decentralization across the NodeLight ecosystem
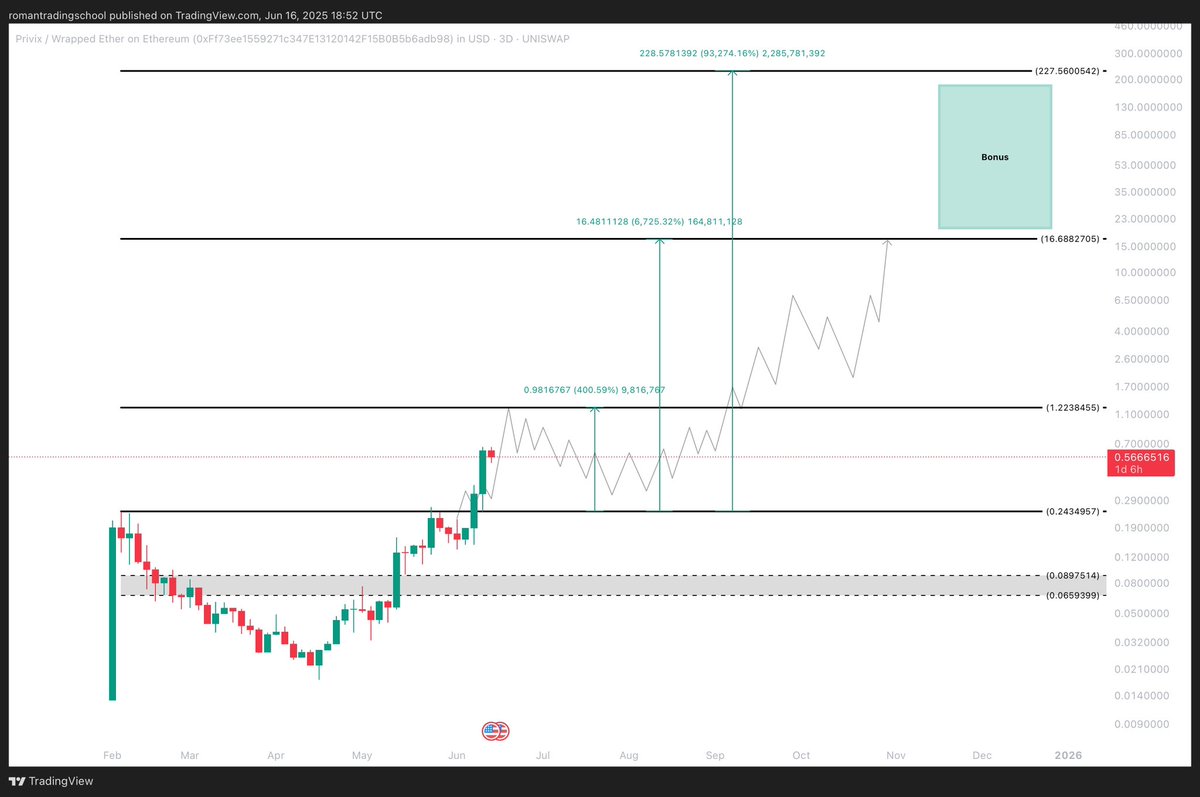
Both $NODL and $PRIVIX have broken their all-time highs (ATH).
Ticker: $NODL
MC: 250K
CA: 0x63a4faa0edc59811f9d3fd8b9aae5131a9488437
Ticker: $PRIVIX
MC: 5.5M
CA: 0xafb942e2a12ac0861ad81b5c37682f588912c1d9
#NodeLight #Privix #NexarAPI #PrivacySwaps #Web3Privacy #DecentralizedFinance #DeFi #CryptoSecurity #NodeLightEcosystem #BlockchainInnovation
$AVM — My official Investometer 📀
AVM is the runtime Infrastructure for the agent economy: a secure, scalable compute layer that turns agent reasoning into real-world execution.
A supercomputer for AI agents.
But is @avm_codes a good investment or not?
Lets find out now 👇🧵
Technology: 🤖
One Standard Interface
Works out-of-the-box with Claude, GPT-4, Cursor, and any agent using MCP or function calling.
Secure, Auditable Execution
Every task runs in a sandboxed container, with outputs like stdout, stderr, and exit codes returned to the agent.
Zero DevOps Overhead
No servers, no scaling logic just hit the API or SDK and start executing.
Enterprise-Grade Performance
Autoscaled, containerized runtimes optimized for ML, cryptography, and agent workloads.
Flexible Pricing
Pay-per-run with support for fiat, crypto, and X402 payment rails.
Workflow:
1. Agent: generates code through your LLM
2. MCP Server: routes the execution job
3. AVM Node: executes code in isolated sandbox
4. Returns: structured output: stdout, stderr, exit code, and metadata
➡️ 100% score — perfect.
Tokenomics: 📊
- circ. supply: 50M (50%)
- total supply: 100M
- 4/4 tax (eventually 0% tax)
- 30% TGE for investors
- 3-18 month vesting
- market cap: $11M
➡️ 82% score — very good.
Community: 💪
- 3.5k+ twitter followers
- 6k+ average views
- 1.6k+ telegram members
- 144K+ engagements (24h)
- 176+ creators (24h)
- social dominance: 0.05%
➡️ 77% score — good.
Narrative: 📢
- AI agent narrative
- ex-binance team
- DEXLaboratory incubated
- Alex Becker on board
➡️ 100% score — perfect.
Team: 👥
- Nik: Strategy & Ops
- 16 years in banking
- ex leadership at Binance
- 7+ team members
- partly doxxed
- legit company
➡️ 93% score — amazing.
Backing: 🧪
- incubated by @DEXLaboratory4
- previous projects:
- $NEURAL ($170M ATH)
- $VERTAI ($110M ATH)
- $TAOBOT ($65M ATH)
- $EDGE ($60M ATH)
- $KOL ($27M ATH)
➡️ 100% score — perfect.
Investometer Score: 91% 🔋
Conclusion:
Yes, $AVM is an amazing play in my opinion.
Lots of big people involved, ex-binance team members, incubated by a chad, real tech that even other founders (SERV for example) are bullish on.
I've been watching it since launch and was trying to catch dips but this thing is pretty much only up - vertical accumulation.
But either way, topblasting seems like a good option in this case because I think $AVM will be at $50-100M soon.
NFA & DYOR 😁
----------------------------------------------------------
Other accounts to follow to keep up with AVM:
@AltcoinMoe | @CryptoFellaTx | @KRYPTO_MASTERS_ | @nordin_eth | @ZssBecker | @crypto_popseye | @polski_degen | @abu_crypto1 | @Oli_Oli_crypto | @DeFiDecoder_ | @marvellousdefi | @OnlyHades_ | @0xlav7 | @DegenKenn | @YusufGemz | @xProfGonzales | @CryptoJonesRC | @ElonTrades | @Jimbotrading | @Alaouicapital | @CryptoFullSendr | @HasTrades | @MoonKing___ | @ZenaXBT | @leo_wh1 | @dontbuytops | @BullishB34R | @MetaverseRanger | @Karamata2_2 | @NobleIrons7de | @Bull100xeth | @dippy_eth | @teachingcrypto | @CryptoMeags | @Going4ward | @CryptoExpert101 | @aeincient
Sorry if I forgot you someone lol
----------------------------------------------------------
Thanks for reading frens 🩶
All engagement much appreciated as these always take forever!
Follow to never miss my high effort content 🤝
mikro out 🫡
A "Secret" Whitepaper Of The Next Trillion-Dollar Fintech Stack 🐸
What if I told you...
- CT is sleeping on the most alpha Whitepaper
- The entire world (except @RibbitCapital and its partners) is sleeping on the next trillion-dollar opportunity in fintech & crypto...
Is the Whitepaper a secret? Not exactly.
But only if you’ve gone deep enough into the $TIBBIR, I mean the Ribbit Hole....
Buried in plain sight: a 22-page “identity letter” from January 2024.
(the highlighted section predicted the reason why @stripe acquired @privy_io , coincidentally after Ribbit cap led an investment round for them...)
I’d argue this letter is more than a thesis.
It’s the whitepaper for a game-changing product, the key to ---- the future of money.
A product already moving in stealth, backed by 30+ partners, and tied to the greatest stealth-launched token ever: $TIBBIR.
Fintech’s rebel VC - or better yet, its most ambitious startup?
Ribbit Capital (founded 2012 by @mickymalka ) has a legendary fintech track record – early bets on @RobinhoodApp , @coinbase , @RevolutApp , @nubank and even Bitcoin in 2012 – growing into a $12B fund atop the Forbes Midas List.
Now this kingmaker has its sights on a new arena.
“Identity is the new money”
In a 2024 letter to investors, Ribbit declared digital identity the next frontier – the missing layer to give money context. Transactions aren’t just numbers anymore but information about who and why. Upgrading identity could unlock massive value in fintech’s $16 trillion market – enough to merit a decade-long bet.
Turning KYC into a new form of business
Today banks burn $100M+ on KYC/compliance with little to show. Ribbit’s thesis flips this – make identity an asset, not a cost. Think Reusable ID credentials that banks and fintechs issue once and get paid every time another institution verifies them. In short, turn compliance into a revenue stream (just as Visa turned payments into $185B for card issuers).
Frictionless finance via a “digital backpack”
The vision is a portable, user-controlled identity layer – a digital backpack of your credentials that you carry to any app. No more repetitive sign-ups or redundant ID checks: one trusted login unlocks all. Identity becomes an invisible force that smooths every transaction, collapsing onboarding friction and personalizing finance globally.
Assembling the frog army... 🐸🐸🐸
Ribbit is quietly aligning 30+ portfolio allies around this shared identity stack.
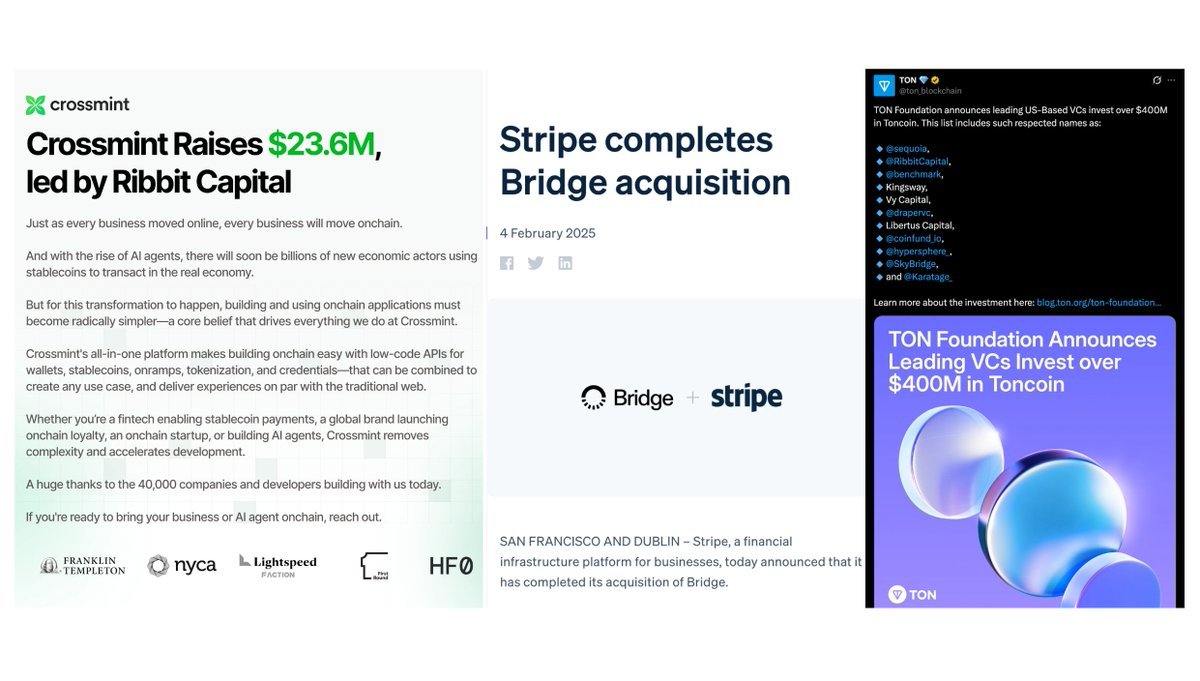
From consumer platforms like Coinbase, Robinhood, Revolut, Telegram (via TON) to infrastructure players like Chainalysis, Privy, Crossmint, Persona and more – all are converging on a unified ID protocol.
This stealth whitepaper in letter form hints at a cross-platform standard – a network of networks where verified identity data flows seamlessly (and privately) between services.
Not just theory – it’s happening: Behind closed doors, the pieces are moving. Ribbit-led funding is fueling identity startups (see Persona’s “trust layer” for web interactions and Crossmint’s onchain IDs for businesses & AI). Even Telegram’s 1B users are coming online via TON, where Ribbit and others just invested $400M+ in its crypto-integrated ID ecosystem.
The frog isn’t predicting the future – it’s building it, in stealth.
The Fintech Rebel Turns to Identity
Follow the frog. For over a decade, Ribbit Capital has played the fintech game on its own terms – and won.
This is the venture firm that bet on zero-commission trading when Wall Street scoffed (Robinhood), on crypto exchanges when banks ignored them (Coinbase), on neobanks rising from emerging markets (Nubank), and more.
Led by the iconoclastic Micky Malka, Ribbit earned a reputation for seeing around corners. Now, with a $12B war chest and a Midas touch portfolio, Ribbit is making its boldest bet yet – one that could redefine finance all over again.
That bet is digital identity. In a January 2024 letter to investors, Ribbit proclaimed what many in crypto suspect but few VCs openly say: “Identity is the new money.” In other words, the next era of fintech won’t be won by whoever moves dollars fastest or cheapest, but by whoever adds the most meaning to those dollars. Money is becoming contextual – every payment, trade, or transfer carries a story: who’s behind it, what’s it for, can it be trusted.
Today’s financial plumbing can’t capture that context; a thick layer of analog bureaucracy sits between our digital lives and our money.
Ribbit’s message: fix identity, and you fix finance.
Why now? Because the stakes are trillions.
Financial services is a $16 trillion industry, and it’s increasingly bottlenecked by antiquated ID processes. Think about it: whenever something breaks in fintech – a payment gets blocked, an account signup takes weeks, fraud alerts freeze your funds – nine times out of ten it’s an identity problem at the core. “Identity is the invisible force enabling or hindering almost everything that happens (or doesn’t happen) in digital finance,” Ribbit observes.
Yet we still rely on uploading passports and utility bills like it’s 1999. The opportunity is vast:
whoever streamlines digital identity stands to upgrade the entire financial system, even by small percentages – and capture enormous value in the process.
Ribbit is so convinced that it’s willing to spend the next 10 years (and untold capital) to make it happen.
From Cost Center to Profit Center
One of Ribbit’s most radical insights is flipping the script on compliance and KYC. Banks today see compliance as a sunk cost – hundreds of millions wasted on verifying IDs, with no competitive advantage to show for it. Ribbit asks: what if, instead, identity verification became a revenue generator?
In their letter, they draw a parallel to the credit card networks.
Creating Visa and Mastercard turned payments into a massive $185B/year industry for card issuers, who earn fees by handling transactions.
Ribbit envisions a similar model for identity:
a network where “identity issuers” (banks, fintechs, even crypto exchanges) make money each time they vouch for a user’s identity to a third party.
Imagine a bank that has KYC’ed you (thoroughly verifying your ID for an account) could issue a digital credential attesting “Yes, Alice is a verified person.”
When Alice wants to sign up at another fintech or crypto platform, that platform can ping the network and pay the bank for instant KYC verification, instead of doing it all over again from scratch.
Suddenly KYC isn’t just a compliance headache – it’s an asset.
As Ribbit puts it, a major bank could turn a “cost center into a significant source of revenue” by monetizing these ID checks.
The beauty of this model is incentive alignment.
If identity data becomes a product, everyone has reason to collaborate on standards – just like banks unified under Visa in the 60s to monetize electronic payments. Ribbit’s letter explicitly calls out this analogy, hinting that a card-network for identity could be in the making. It’s a world where an Amazon or Coinbase might pay small fees to “identity providers” (say, JPMorgan or even a crypto KYC firm) to instantly verify users, rather than making users repeatedly submit documents. Compliance turns from drudgery to API call – and a profitable one at that.
Building the Digital Backpack 🐸🎒
How do we make such an identity network real?
By creating what Ribbit insiders are calling the digital backpack – a unified, user-centric identity layer for the internet.
The concept is simple but powerful: you carry a portable identity wallet that you control, filled with verified credentials (government IDs, financial profiles, reputations, etc.).
You can instantly share bits of this identity with apps and services as needed – proving who you are, without endlessly refilling forms or re-uploading documents. And just as importantly, you can revoke access just as easily, maintaining privacy and control.
Ribbit’s letter lays out a framework for this. It describes “reusable identification wallets” that let customers aggregate their identity info and bring it with them to different products – much like a passport you can use in any country.
This digital backpack isn’t a single app or company, but an interoperable standard across many players.
Think of it as an identity layer that all fintech and crypto services plug into – a network of trust underlying everything. If done right, users gain freedom (one identity for all apps), businesses gain confidence (instant trust about who they’re dealing with), and regulators get better oversight with less overhead.
Here’s where Ribbit’s master plan comes into focus. They aren’t just theorizing about this; they’re assembling an alliance to build it.
Consider the roster of companies that Ribbit has invested in or is closely aligned with, and you see the outlines of an identity super-network:
@Coinbase – a crypto giant with millions of KYC’d users and a growing identity brokerage (think Coinbase Wallet, onchain reputation).
@RobinhoodApp & @RevolutApp – consumer finance platforms that thrive on seamless UX; a portable ID could let them onboard and cross-offer services with near-zero friction.
@telegram (TON) – a messenger with 1+ billion users now integrating TON blockchain IDs; it’s the social layer where a user’s “digital passport” could live in chat (Ribbit just co-led a $400M Toncoin round, no coincidence).
@privy_io – wallet and onboarding infrastructure for web3 apps, funded by Ribbit to help developers embed easy crypto/ID login (recently got acquired by the #4 largest fintech company in the world: @stripe )
@Crossmint – building onchain tools for enterprises and AI agents, backed by Ribbit to move every business onto blockchain rails (and crucially, enabling those AI agents to have identity and wallets).
@chainalysis – blockchain analytics and compliance; it links addresses to real-world entities, providing the risk/compliance data to enrich an identity network.
Persona – an ID verification startup Ribbit co-funded, which handles verifications across industries and just raised $200M to build the internet’s “trust layer”.
Others – from banking API providers to AML platforms – essentially every puzzle piece of identity, Ribbit has a stake in it...
It’s as if Ribbit has been quietly investing in infrastructure for an identity stack all along, and now that puzzle is coming together.
The 2024 Identity Letter reads like a stealth whitepaper for this effort
– outlining the vision and architecture (common standards, partnerships, incentive models) without explicitly announcing a product.
But make no mistake: Ribbit and its allies are building the rails for a unified identity layer, likely under the radar until it’s ready for prime time. Insiders even suspect the name “Ribbita” or the frog theme might surface in the branding of this network – a nod to Ribbit’s role in spawning it.
Contextual Money in Action
What does a world with a universal identity layer look like? In a word, magic. Money starts to carry its context with it, everywhere.
Your finance apps and bank accounts suddenly “know” you (with your permission), so they can serve you without endless prompts. It’s one-click to sign up for anything new – your digital backpack provides verified info as needed.
Sending funds becomes rich in meaning: imagine paying a contractor and automatically attaching proof of their certifications, or getting a loan and lenders instantly seeing your reputation and credentials (without you manually emailing PDFs). Friction drops, trust rises.
User experience would leap(frog) to another level.
No more passwords, no more repetitive forms – logging into a new service could be as simple as a cryptographic handshake verifying you are a real, vetted person. It’s the death of the dreaded “please upload your ID and wait 3-5 days” screen.
In Ribbit’s words, money becomes “smarter, more accessible, more personalized” when identity is solved.
Services can tailor products in real-time because they truly know their customer (finally living up to the KYC acronym) – all while the user stays in control of what they share.
Crucially, this identity layer would unlock AI agents in finance. We’re on the cusp of personal AI assistants and autonomous agents handling everything from investing to shopping on our behalf.
But to trust an AI to act for you, or to let it interact with financial systems, you need a way to vouch for its identity and rights. With Ribbit’s identity network, you could delegate a verified slice of your digital ID to an AI agent. Suddenly your AI can, say, open a bank account for you, execute trades, or book travel, all in your name but within limits you set.
Ribbit’s @nshalek underscores this, noting “identity has become the foundation of every digital interaction, and in the age of AI, solving identity will be more pivotal than ever”.
In practice, a wallet that holds your ID credentials might also issue special tokens or keys to your AI assistant, letting it prove “I represent Alice” to various services without exposing your passwords.
This is how money gains programmability with context – your AI or smart contract can carry the context of your identity and preferences into every transaction it makes for you.
The result is finance that operates at the speed of software, but with human-level trust.
Follow the Frog 🐸
Ribbit’s grand identity play is not just another VC thesis – it’s a coordinated campaign to reshape how we trust on the internet.
By rallying its portfolio and beyond to collaborate on a shared identity protocol, Ribbit is blurring the line between investor and builder.
There’s even talk of an incentive mechanism to turbocharge adoption: perhaps a token lurking in the wings...
A stealth-launched token $TIBBIR (Ribbit spelled backwards), whose contract was funded by the 7 year old Ethereum wallet of @mickymalka , the founder of Ribbit Capital, making rounds in crypto circles
– a hint at a native token that could reward participants in this ecosystem (- not unlike - how Revolut uses points to reward user loyalty...)
While still speculative, the idea is that such a token could align stakeholders – users, companies, verifiers – by economically rewarding the growth of the network.
If your “digital backpack” becomes the default login for apps, every party that helped verify or enrich your identity could earn a slice of the value, potentially paid in $TIBBIR...
It would turn the identity network into a self-sustaining economy, much like how Bitcoin incentivizes miners to secure it.
For now, (unsurprisingly) Ribbit and its partners are keeping things low-key.
But the evidence is everywhere for those paying attention: onchain data, fundraising news, strategic partnerships subtly oriented toward interoperability.
"The next wave is coming. Crypto and fintech are merging into a single ecosystem." - @ribbita2012 's bio, followed by the entire Ribbit team
The frog-themed clues all point to the same conclusion – the future of money isn’t just digital, it’s contextual.
Identity is the connective tissue that will make our financial lives seamless, and Ribbit Capital is secretly stitching that tissue together as we speak.
High-conviction? Absolutely.
This is a firm that changed fintech once; they’re poised to do it again, armed with an army of allies and an armor of identity data.
The bottom line for crypto-native readers and $TIBBIR holders: watch this space. The convergence of fintech and crypto via a unified identity layer is the big play for 2024 and beyond.
Compliance, privacy, user experience, AI integration – solve identity and you solve them all in one stroke.
Ribbit’s frog logo might as well be a symbol of transformation: from tadpole ideas to a fully grown revolution in how we identify ourselves online.
It’s sneaky and it’s stealthy, but it’s coming.
So, as the insiders say, follow the frog. The next trillion-dollar protocol might not be a new L1 or DeFi app, but the identity network tying everything together – and Ribbit is already leaps ahead of the pack.
$TIBBIR was stealth-launched on @virtuals_io , Coinbase's L2 @base, the X account is @ribbita2012 followed by 100+ smart accounts. Most people thought it was a drunk chatbot, but in reality, its insider-level tweets predicted the biggest moves in fintech.
(Robinhood's new RWA exchange, Stripe, Revolut news and many more)
Now, Ribbita2012 is automated by @ribbita2025 , an account that represents Ribbit cap's next chapter. Make sure you check the 4 accounts ribbita2025 is following.
Might be breadcrumbs...🔮
cc @MessariCrypto @dragonflyvc@cbventures@paradigm
🔥 The noise has been ongoing at $AVM for the past week despite everyone's concerns about War. After some serious research, I have answered the question:
▶️ Is AVM the ultimate playground for AI in Web3?
I saw most “AI x Web3” projects are just GPT bots with a token, but AVM @avm_codes is different.
@avm_codes is about doing and gives agents a secure space to reason, act, and evolve.
This is the full loop if you might ask me: Think → Act → Observe → Adapt
That means:
- Sandboxed code execution
- MCP-native routing
- Agent state + memory
- Verifiable task output
- Recursive learning loops
▶️ Why I call it a playground?
Because AVM lets agents test, break, and improve themselves in a safe, resource-quota-controlled environment.
Like a gym for autonomous behavior.
- No rogue code
- Real-time feedback
- Safe experimentation
▶️ And this isn’t theoretical, imagine this:
- A supply chain agent wakes at 3AM
- Disaster reroutes half the trucks
- Agent pulls live GPS, weather, wages, news
- Reroutes deliveries
- Sends updates
All while you’re still asleep, that agent runs on AVM.
▶️ Each task runs in its own AVM “sandbox”, think Docker but crypto-native with token-incentivized validation.
This has real crypto rails, the $AVM powers:
- Compute costs
- Secure sandbox access
- Decentralized task validation
- Incentives for solvers + node runners
▶️ Incubations by @DEXLaboratory4 like:
- $EDGE
- $VERTAI
- $NEURAL
- $TAOBOT
- $KOL
A person who pursues genuine utility with thoughtfulness and meticulous care
▶️ With only ~15M MCap and 43% circulating, it's early.
Just like smart contracts needed the EVM to thrive, autonomous agents need AVM to do more than talk.
So is AVM the ultimate playground for AI in Web3?
Yes, because it gives agents the freedom to learn and act, without giving up safety, structure, or crypto-native principles.
The future is smart agents, and I'm comfortable with a big bag here.
Chart: https://t.co/dO43MdkhSQ
Some chads are interested in $AVM: @ZssBecker@ElonTrades@AltcoinMoe@DEXLaboratory4@teachingcrypto@mikroweller@0xlav7@xProfGonzales@Alaouicapital@nordin_eth@crypto_popseye@dontbuytops@CryptoGideon_@Oli_Oli_crypto@ZenaXBT@NobleIrons7de