$NBIS @realDonaldTrump would say:
"THIS IS A GREAT TIME TO BUY"
1.) Private markets are paying massive 22x premiums:
Pure inference provider Fireworks AI (basically Nebius Token Factory) is now reportedly seeking a $30 to $40 billion valuation at an expected $1.6B ARR EOY.
(https://t.co/3agAANZSBs)
The company priced at only $4 billion in October 2025 and $17.5 billion just this July!!!
2.) Meanwhile, public markets are running on Doomium.
$NBIS is trading approximately 50% below its June all time high at roughly a $40 billion market cap as well. 😂
The disconnect is staggering because Nebius is essentially Fireworks PLUS:
Instead of only leasing compute (like Fireworks) Nebius owns the underlying data centers and power infrastructure. They also design their own servers, racks and cooling systems.
-> Able to squeeze margins at every layer
The company operates a fully integrated multi tenant AI cloud (offering way more services) holding a strategic $NVDA investment and $44.4 billion in combined $MSFT and $META contracts.
Nebius pairs this international physical scale with hyperscaler tier engineering talent and a world class, deeply experienced management team.
The broader "Nebius Group" also includes autonomous driving unit Avride and a massive stake in high performance database ClickHouse.
So:
Private smart money is aggressively bidding up a standalone software layer.
Public markets are discounting a full stack hardware + software infrastructure giant. (Token factory also on its best way to $1B ARR)
Article:
https://t.co/190LvLdOIb
Neocloud Map by @sonnet_xu
$NBIS Weekly Review 10/19:
So much happened this week this took me an 1hr+ to cobble together ( ´ཀ` )
🏦 $NBIS Secures $3.5B Citi Credit Facility
- 1YR bridge facility to finance GPU deployment
- Bridge to ABF once eligible collateral is in place
- Capital markets remain open for $NBIS
🔌 $NBIS already with 5GW+ reserved
- Means 800MW+ of sites remain unannounced
🤯 1 GW+ of Veras in 2027
- Majority of capacity for next year is Vera Rubins
- $20-25MM/MW/YR is the pricing floor with blend of GB300s, as Reflection already deploying
- 2027 monetization could be materially higher
⚖️ 50/50 Spot & Auction vs. Longer-term contracts
- Management now targeting a significantly larger share of capacity for short-duration workloads
- Yet another catalyst for 2027 monetization
🔓 $NBIS Removes Spot GPU Price Ceiling
- Customers could potentially pay MORE for interruptible GPUs than for non-preemptible ones
- Compute scarcity is going absolutely bonkers
♻️ $NBIS Capacity-Rebate Pilot Live
- Allows customers to release idle reserved GPUs into the Spot pool
- Customers earn rebates while Nebius monetizes otherwise unused capacity
- Improves GPU utilization and revenue per MW
🕋 $NVDA Announces DSX Run Pod
- Accelerates Vera Rubin deployments
- Modular AI data centers built with ecosystem partners
- Cuts onsite installation from 6 months → 14 days
🇸🇦 50MW Saudi Datacenter
- Located at NEOM's Oxagon industrial hub
- Online starting in Q4 2027
🇺🇸 $BE confirms 100MW live soon for Vineland
- Fuel cells + 123MW gensets
- 200MW live on campus floor by EOY
📊 $NBIS Analyst Price Target Updates
- BofA maintains Buy, $310 PT
🏭 @nebiustf onboards two new models
- MiniMax M3.1 Flash, DeepSeek V4.1 Flash-1017
- Now ~110 models served
⚡ @nebiustf launches prompt caching for public API
- Makes its on-demand inference offering significantly more competitive
- Already seeing a massive surge in tokens processed through OpenRouter
If I knew whether neoclouds will have the same pricing power or more of it than today, I’d start a hedge fund, diversify across neoclouds, and win gold.
I do feel pricing power will go up because my thesis is that the physical world won’t be able to keep up with the demand for automating most of the economy.
Since I obviously don’t know, I prefer to diversify across one cloud stock: $NBIS.
Now you must be thinking, what clown diversifies across one stock in a sector?
For me, it’s diversifying across optionalities. For Nebius, there are two axes of this optionality:
(1) Products: Bare metal, cloud, Token Factory, agentic applications, sovereign AI infrastructure.
(2) Customers: Hyperscalers, AI-native startups, enterprises, software and platform providers, government agencies, and other sovereign AI customers.
And this basically means that if compute stays scarce, Nebius can choose how to monetize its capacity, depending largely on its financing needs.
If they can secure favorable credit facilities like the one with Citi this week, they can focus more on premium short-term cloud and Token Factory deals, taking advantage of higher spot and market prices instead of locking up capacity in long-term contracts.
If this line of financing gets closed for whatever reason, they can sell bare metal to hyperscalers on long-term deals.
And if compute somehow gets overbuilt, they can focus more on the agentic application layer and direct services, utilizing their owned cloud infrastructure and drawing from their 20+ years of institutional knowledge of building elite software.
So for management with a vision, this is a lot of optionality to build around and switch focus when circumstances change.
We already saw this with the switch from long-term bare metal deals to short-term cloud and Token Factory deals, which came just a few months after their massive deals with Microsoft and Meta.
Neoclouds that don’t own this Swiss Army knife set of optionalities – bare metal, cloud, Token Factory, agentic applications, sovereign AI infrastructure, are more exposed if the wind becomes unfavorable, or if a storm comes.
This diversification across Nebius optionality, of course, requires full trust in management’s ability to correctly process signals from the real world, identify new trends, and change the company’s focus before the current one becomes a drag.
And I believe management has consistently shown this ability since their relisting on Nasdaq.
Also, Nebius is basically replaying the NVIDIA playbook of having hundreds or even thousands of people out in the real world, talking to actual builders all the time, talking to investors and lenders, talking to countries that wish to build sovereign AI infrastructure, organizing events, and building human connections.
No other neocloud comes nearly as close to Nebius when it comes to ingesting this real-world information that lets them know what will happen next better than their competitors.
It’s basically dominance through information.
So this is by no means a bearish take on other neoclouds. This is just my reasoning for why I decided to diversify across one.
And it’s not investment advice.
Just saw a note that short interest across $CRWV CoreWeave, $NBIS Nebius, $IREN, $APLD Applied Digital and $CORZ Core Scientific currently ranges betwen 20% to 26% of free float ($17B equivalent of stock sold short)
The irony is - some of the sell-side who are constructive on these names are also stock lenders through their prime desk
With this level of short interest, a reversion is going to trigger a significant squeeze
$NBIS @realDonaldTrump would say:
"THIS IS A GREAT TIME TO BUY"
1.) Private markets are paying massive 22x premiums:
Pure inference provider Fireworks AI (basically Nebius Token Factory) is now reportedly seeking a $30 to $40 billion valuation at an expected $1.6B ARR EOY.
(https://t.co/3agAANZSBs)
The company priced at only $4 billion in October 2025 and $17.5 billion just this July!!!
2.) Meanwhile, public markets are running on Doomium.
$NBIS is trading approximately 50% below its June all time high at roughly a $40 billion market cap as well. 😂
The disconnect is staggering because Nebius is essentially Fireworks PLUS:
Instead of only leasing compute (like Fireworks) Nebius owns the underlying data centers and power infrastructure. They also design their own servers, racks and cooling systems.
-> Able to squeeze margins at every layer
The company operates a fully integrated multi tenant AI cloud (offering way more services) holding a strategic $NVDA investment and $44.4 billion in combined $MSFT and $META contracts.
Nebius pairs this international physical scale with hyperscaler tier engineering talent and a world class, deeply experienced management team.
The broader "Nebius Group" also includes autonomous driving unit Avride and a massive stake in high performance database ClickHouse.
So:
Private smart money is aggressively bidding up a standalone software layer.
Public markets are discounting a full stack hardware + software infrastructure giant. (Token factory also on its best way to $1B ARR)
Article:
https://t.co/190LvLdOIb
Neocloud Map by @sonnet_xu
$NBIS: In the absence of data on Token Factory, we can analyze Fireworks AI.
Thanks to the diffusion and success of open-source models, Fireworks was able to 3x its ARR in less than 6 months, reaching $1B.
On the 20VC podcast, CEO Lin Qiao said the number is on track to hit closer to $1.6B by year-end.
But revenue is only part of the story, what about margins? Lin Qiao is clear: they are in a hypergrowth phase and are not optimizing for margins yet.
Even so, margins should be in the 30-40% range, with potential to expand to 60%+ as the business matures.
One of the main expenses pressuring them is hardware rental across more than 20 suppliers. This is where Nebius may have a crucial advantage, leveraging its proprietary GPU fleet.
Finally, valuation: in July, Fireworks closed its Series D at a $17.5B.
And here we go, Round 3
From Nomura: we’ve seen resumption of “Notable Call Buying” in some of the usual suspect “Core AI” names over the course of the past week which should be monitored
CRWV: $69M premium, delta of 3M shares or $170M
- buyer of 21k Apr 80 Calls for $7.15 (10/22)
- buyer of 25k Mar 85 Calls for $8.07 (10/21)
- buyer of 20k Apr 90 Calls for $8.07 (10/15)
- buyer of 20k Mar 80 Calls for $8.85 (10/14)
NBIS: $25.7M premium, delta of 500k shares or $80M
- buyer of 7.5k Mar 230 Calls for $16.07 (10/22)
- buyer of 7.5k Apr 260 Calls for $18.15 (10/21)
DRAM: $20M premium, delta of 1.9M shares or $85M
- buyer of 27k Apr 60 Calls for $3.40 (10/22)
- buyer of 30k Mar 60 Calls for $3.65 (10/21)
As LLMs become the default first step in investment research, consensus bias is going to get stronger, not weaker.
The models are trained on, and now retrieve, whatever has already been published about a stock. Ask one for a view and you get the weighted average of the sell-side, the press and the message boards, delivered with more confidence than any of those sources had on their own. The model doesn’t add information. It adds conviction to the default view.
Consensus drives short-term price action. Cash flows set terminal prices. So if LLMs compress the dispersion of views, two things follow for anyone running a non-consensus position. First, fewer people will be positioned on your side, so the pain before the thesis plays out gets longer and deeper than it was in the pre-LLM world. Second, when the cash flows arrive and the consensus has to move, it moves with fewer hands already on the other side. The snap-back is more violent.
I see the mechanism every day. When I use LLMs for stock research, the first 90-95% of the background work is largely right. The last 5% is where it goes wrong, and it goes wrong in a specific way. The published view almost always runs on a default: the market assumes X because that’s how it usually works. The model has seen a thousand cases where it worked that way, so it hands you the default with full confidence. The alpha is in the cases where this particular company, contract or regulatory path is different, and a tool built to return the typical answer is the last place that difference will show up. I spend hours pulling raw filings, checking numbers and fighting with the model to get it to reason about the specific case instead of the usual one.
Most investors won’t do that. They’ll stop at 95%, holding the default assumption with more confidence than they had before. Consensus plus conviction is the most expensive combination in markets, and I think it’s where the next few years of mispricings will come from.
AWS with a good chunk of 2028 capacity sold out BTW.
Strength of demand environment is allowing pricing visibility 2+ years out.
$NBIS has fully preserved that upside optionality.
https://t.co/uXUI0m6xtc
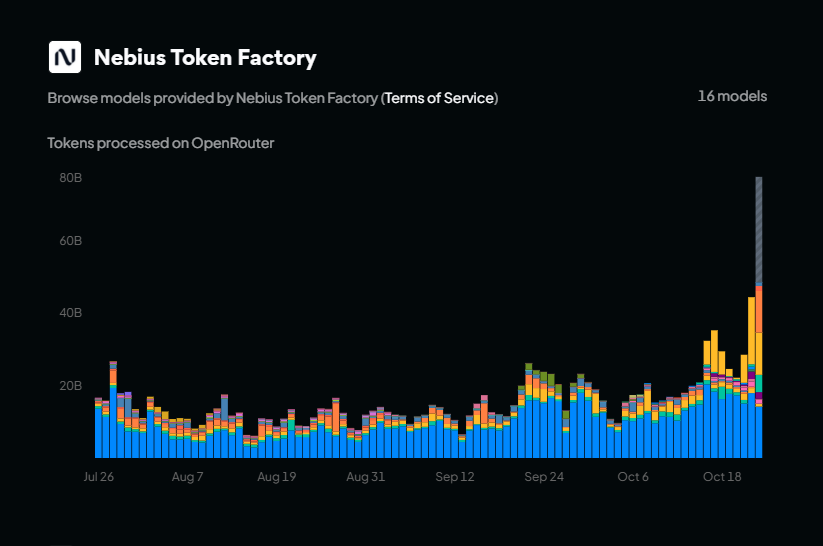
Velocity matters. After a few of us devs explicitly pushed for public endpoint prompt caching on X, $NBIS Token Factory finally shipped it within months and the Open Router volume has gone instantly parabolic (scaling past 80B daily tokens just today). Get ready for $NBIS Token Factory to now take a massive chunk of public endpoint Open Weights Tokens processed from competitors like @FireworksAI_HQ & @togethercompute
Raw serving performance like Latency/TTFT and TBT or Tokens per Minute/Throughput was never the blocker for $NBIS Token Factory. Without public endpoints having input prompts with cached pricing user cost bottlenecks alongside Token Factory simply not being picked as a default routing option on routing platforms like Open Router, $NBIS Token Factory for sure had a massive impact to its true potential token volume as I have highlighted plenty of times before.
That single engineering friction point was holding back production grade volume from providers like Open router, Vercel AI Gateway and more. With $NBIS closing the feedback loop and delivering this as fast as they just did, the instant usage spike on Open Router to $NBIS Token Factory speaks for itself. Keep and eye on this chart as this will continue to balloon.
Software + Hardware Infrastructure execution doesn't get better than this. $NBIS
$NBIS 80B DAILY TOKEN SPIKE !
@nebiustf just introduced CACHED TOKENS ....
and processed Tokens via OpenRouter immediately went vertical.
AI models usually read text from scratch for every single request.
Nebius' Token Factory System now remembers your previous text inputs which helps the servers to skip the heavy computing for anything they have already processed.
This drops the cost for recurring prompts drastically and it fundamentally alters revenue potential and platform visibility for $NBIS.
Here is why 👇
Automated routing algorithms (like OpenRouter or Vercel AI Gateway) hunt for the lowest price.
Before this update, the lack of caching made Nebius quite expensive for these routers to pick by default.
With the pricing barrier now gone, algorithms instantly recognize Nebius as the optimal choice. Raw serving performance like latency was already top tier.
Nebius now combines elite speed with the lowest effective cost. This forces massive token volume directly onto their network.
(like shown by @BKad2005 below)
Nebius is now perfectly positioned to capture massive market share from competitors like Fireworks and Together AI .
For more, read @BKad2005 's post below:
Velocity matters. After a few of us devs explicitly pushed for public endpoint prompt caching on X, $NBIS Token Factory finally shipped it within months and the Open Router volume has gone instantly parabolic (scaling past 80B daily tokens just today). Get ready for $NBIS Token Factory to now take a massive chunk of public endpoint Open Weights Tokens processed from competitors like @FireworksAI_HQ & @togethercompute
Raw serving performance like Latency/TTFT and TBT or Tokens per Minute/Throughput was never the blocker for $NBIS Token Factory. Without public endpoints having input prompts with cached pricing user cost bottlenecks alongside Token Factory simply not being picked as a default routing option on routing platforms like Open Router, $NBIS Token Factory for sure had a massive impact to its true potential token volume as I have highlighted plenty of times before.
That single engineering friction point was holding back production grade volume from providers like Open router, Vercel AI Gateway and more. With $NBIS closing the feedback loop and delivering this as fast as they just did, the instant usage spike on Open Router to $NBIS Token Factory speaks for itself. Keep and eye on this chart as this will continue to balloon.
Software + Hardware Infrastructure execution doesn't get better than this. $NBIS
@Mapago9 Most people are lazy and don't do their DD. This is why they can't tell the potential before it runs and can't buy the dip when fundamentals and sentiment diverge.