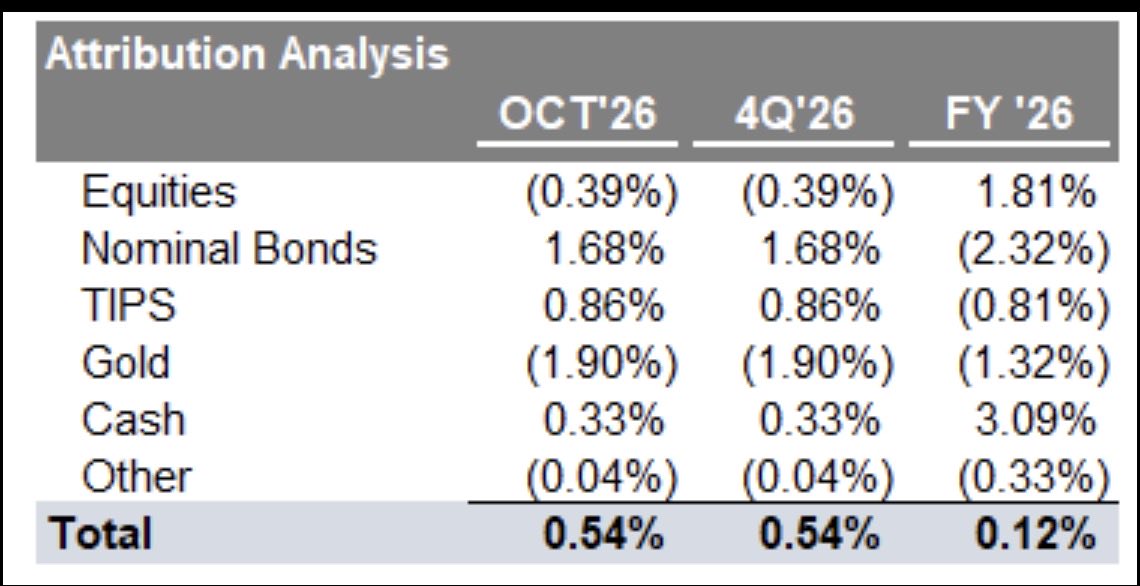
OCT: +54bps
YTD: +12bps
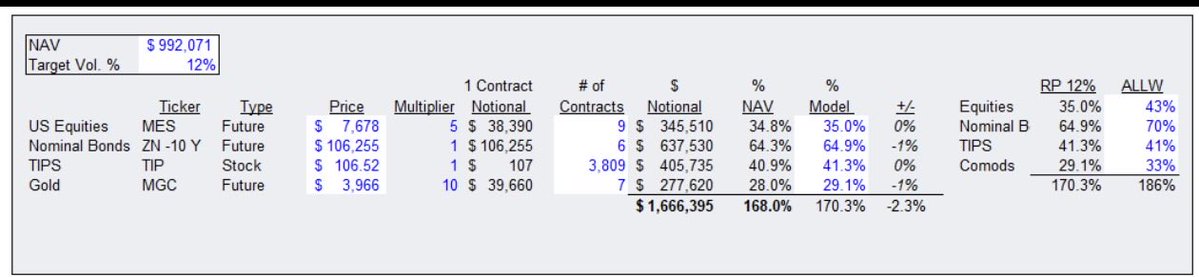
October was a tough market across all asset classes. Our model was moderately positive during the period.
https://t.co/Ix5q7LdoWu
@Alpha_Fox11@BerkelKip I get to 12% IRR over 10 years in my model. I think the CSU team and culture might deliver a 12% for a long time outperforming meaningfully over multiple cycles
RBCs model has EBITDA growing 20% for the next 2 yrs and is more aggressive than mine so my 12% 10yr IRR could be low
@deepvalueco@Richard15322800@agnchls I’ve owned this in the past and sold the small remainder I had left, yesterday. Actually made $ but extremely volatile path. NOI doesn’t seem to go up even though they have acquisition and dev pipe.
Don’t follow the name close enough to understand why NOI isnt growing
@Richard15322800@deepvalueco@agnchls Completely agree. REIT investors accept a terrible governance model & own mostly crappy assets in exchange for preferential tax treatment.
It might work except MGMT frequently knee caps you and better long duration assets are available with superior governance and TSR
@Invesquotes@deepvalueco How mid-priced do you think $CSU.TO is here given the move off the lows earlier in the year and where other software peers trade ?
@Invesquotes Execution has been strong YTD. I’m curious, what long term returns are you modeling for CSU from these levels as the stock price has recovered?
@rarestbarbie Yes….this seems to basically equate revenue and expenses and then just throw the residual deficit into its own pile as if it’s not related to the revenue/spending which is obviously is. Terrible model !
@dollarsanddata People don’t understand that financial assets trade at a discount to future cashflow and you can quite literally own Beta and earn that discount rate as cash flows materialize and the value accretes